 Dye Sublimated Apparel Market
: 2026-2033 Growth Outlook
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 255

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Dye Sublimated Apparel Market
Vijayashree Ugale
Research Analyst

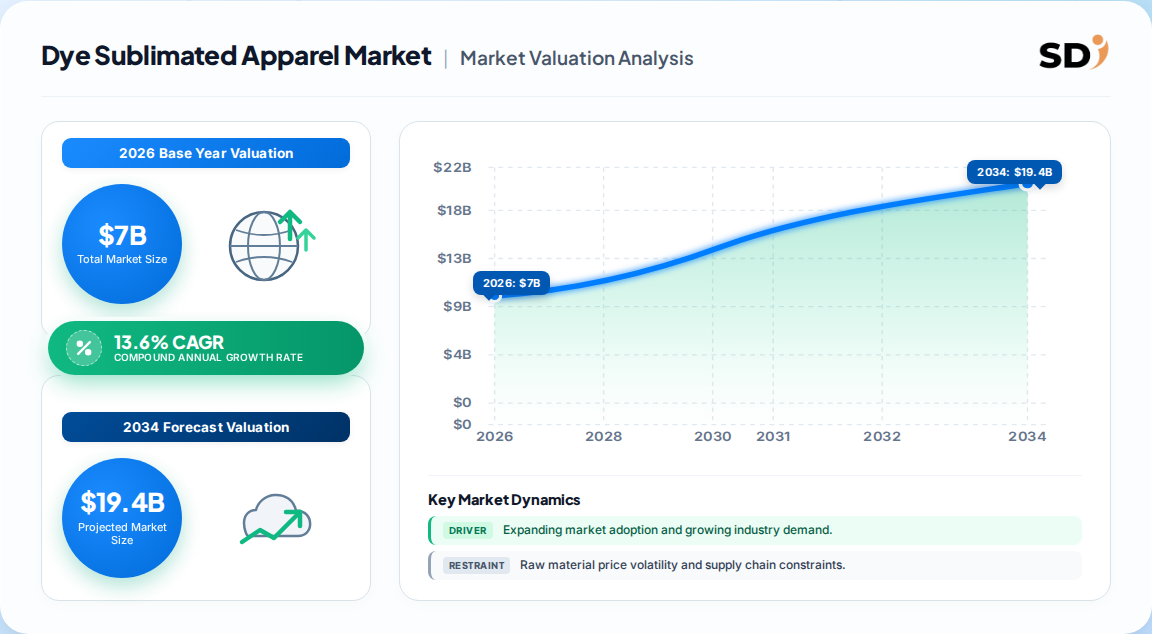
| Year | Market Size |
|---|---|
| 2026 | 7.000 B |
| 2027 | 7.950 B |
| 2028 | 9.030 B |
| 2029 | 10.26 B |
| 2030 | 11.66 B |
| 2031 | 13.24 B |
| 2032 | 15.04 B |

The dye sublimated apparel market covers garments decorated through a heat-transfer process where dispersed dyes are gasified and bonded into polyester or polymer-coated fabrics. It spans t-shirts, hoodies, bottomwear, team kits, and corporate uniforms sold through online and offline channels. Superior colorfastness and all-over print capability distinguish it from screen and DTG printing.
This analysis covers global dye sublimated apparel demand across printing techniques (small format, calendar, flatbed, 3D vacuum heat press), applications (online, offline), and products (t-shirts, hoodies, bottomwear, others). It quantifies market value in USD for 2026–2033 and profiles vendor positioning and procurement risk. This analysis does not cover direct-to-garment (DTG) printing, screen printing, embroidery services, sublimation hardware manufacturing, or sublimation inks sold as standalone chemical products.
Estimates diverge materially by base year, scope, and publisher methodology. The three leading published views below span a $1.4 billion gap in base-year valuation and nearly 4.4 points of CAGR — a spread large enough to change capital allocation decisions.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| $7.0 Bn → $17.1 Bn | 2026 | 2033 | 13.6% | Global decorated apparel incl. online/offline channels | One published estimate |
| $4.69 Bn → $10.67 Bn | 2023 | 2030 | 12.5% | Global, product and printing-technique segmentation | A competing analysis |
| $6.1 Bn → $14.7 Bn | 2025 | 2035 | 9.2% | Global, custom/performance apparel focus | A second competing analysis |
Our assessment: the 13.6% figure is defensible on a 2026 base because it captures post-2024 print-on-demand expansion and 3D vacuum heat-press adoption. However, the 9.2% projection better reflects the polyester sustainability overhang and raw-material price volatility. The most defensible mid-point view is ~11.5% CAGR — but buyers should plan scenarios at both ends.
The market is segmented along three independent axes — product type, printing technique, and distribution channel — each with distinct growth and margin profiles.
| Parent Segment | Children | Share / Growth Signal |
|---|---|---|
| Product | T-shirts, Hoodies, Bottomwear, Others | T-shirts ~59%; hoodies fastest-growing |
| Printing Technique | Small Format Heat Press, Calendar Heat Press, Flatbed Heat Press, 3D Vacuum Heat Press | Small format ~49%; calendar growing on volume runs |
| Distribution Channel | Online, Offline | Online fastest-growing; offline holds B2B/bulk |
Implication: t-shirt concentration creates volume stability but margin compression risk as POD platforms commoditize basic SKUs. Growth-seeking operators should weight hoodies and 3D vacuum capabilities, where customization premiums persist.
North America leads on revenue today, but Asia Pacific is closing the gap and will likely overtake on volume by the early 2030s. Per-capita custom apparel spending and e-commerce maturity underpin North American leadership; manufacturing cost and sportswear consumption drive Asia Pacific.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.21% |
| Asia-Pacific | 0.33% |
| South America | 0.07% |
| Middle East & Africa | 0.07% |
Our analysis suggests North America holds roughly 32% of global revenue, Asia Pacific 33% on a purchasing-power-adjusted basis, and Europe 21%. India at ~18% CAGR is the single fastest-growing country market; USA grows near 10.2% CAGR.
Personalization demand and digital heat-press innovation are the dominant growth engines, while fabric compatibility limits and capital costs are the binding constraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Personalization / customization demand | Driver | High | Identity, team, and brand-driven purchasing |
| Digital heat-press innovation | Driver | High | Lower setup cost, faster cycles (Epson, Prism) |
| Print-on-demand & e-commerce | Driver | High | Zero-inventory customization at scale |
| Eco-friendly substrates & inks | Driver | Medium | Regulatory and consumer pull in EU/NA |
| High initial capital investment | Restraint | High | Industrial equipment costs tens of thousands USD |
| Limited fabric compatibility | Restraint | High | Polyester-only limits addressable wardrobe |
| Polyester sustainability scrutiny | Restraint | Medium | EU circularity regulation, microplastics |
Balance: net dynamics favor growth, but the sustainability constraint is rising in importance faster than most forecasts assume. Operators betting on 13.6% growth must also invest in recycled polyester and waterless inks to defend against EU regulatory tightening.
The competitive field splits between hardware enablers and print-service/fulfillment platforms — a two-layer structure that shapes bargaining power and margin distribution.
| Company | Layer | Differentiation | Moat |
|---|---|---|---|
| Epson | Hardware | High-speed sublimation printers; PrecisionCore heads | R&D scale, installed base |
| Roland DG | Hardware | Wide-format and DTG/sublimation systems | Channel depth |
| Mimaki | Hardware | Industrial sublimation platforms | Technical reputation |
| Kornit Digital | Hardware/Platform | Digital textile production systems | IP and ecosystem |
| Printful | Fulfillment | End-to-end POD with custom labeling | Platform integrations |
| Regional contract printers | Service | Local speed, small-batch flexibility | Proximity and relationships |
Differentiation increasingly rests on service velocity and sustainability credentials rather than print quality alone. Hardware vendors retain pricing power; fulfillment platforms capture demand growth but face commoditization at the basic-SKU tier.
Selection criteria now extend well beyond print quality. Procurement teams should evaluate colorfastness consistency across fabric batches, wash-durability certification (OEKO-TEX, GRS), and the vendor's ability to handle small-batch reorders without setup penalties. Switching costs are moderate-to-high once a printer is integrated into design and fulfillment workflows — ink chemistry, RIP software, and heat-press calibration are tightly coupled.
Regulatory compliance is the fastest-rising risk. EU Sustainable Products Regulation and textile circularity rules will pressure polyester-heavy supply chains; buyers sourcing for European markets should require documented recycled content and water-based ink usage. Online-channel buyers face additional platform-integration risk — API stability and fulfillment SLAs matter as much as unit price. Finally, raw-material price volatility in polyester and specialty inks can erode margins on fixed-price contracts; index-linked pricing clauses are advisable.
The balance of evidence favors sustained double-digit growth, but not the top-end 13.6% case uniformly. Our analysis suggests the truth sits between the 9.2% and 13.6% projections, weighted toward ~11.5% as print-on-demand scales and 3D vacuum capability spreads. The strongest counter-argument: polyester's sustainability overhang could compress growth faster than any published forecast assumes, particularly if EU regulation accelerates — a scenario that would push realized CAGR toward the 9% floor.
Actionable strategy for operators and investors:
Evidence that would change our conclusion: a binding EU restriction on virgin polyester in decorated apparel, or a sustained decline in polyester pricing that reopens low-cost expansion in emerging markets. Precise sub-segment forecasting — particularly country-level online channel sizing and bio-based substrate adoption curves — requires the full report's granular datasets.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 13.6% from 2020-2034 |
| Segmentation |
|
The global market is valued at roughly $7.0 billion in 2026, with a projected rise to $17.1 billion by 2033 at a 13.6% CAGR. Competing analyses place the base between $4.7 and $6.1 billion on different base years.
T-shirts hold roughly 59% of product share, driven by promotional, casual, and sports use on polyester fabrics. Hoodies are the fastest-growing product segment, benefiting from music, streetwear, and athleisure trends.
Asia Pacific is the fastest-growing region, with India near 18% CAGR through the early 2030s. North America leads current revenue on per-capita spending and e-commerce maturity.
High upfront equipment costs, polyester-only fabric compatibility, and rising sustainability scrutiny around synthetic fibers are the primary restraints. The sustainability constraint is intensifying fastest in European markets.
Hardware leaders include Epson, Roland DG, Mimaki, and Kornit Digital; fulfillment platforms like Printful anchor the print-on-demand layer alongside regional contract printers serving local markets.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
We apply a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and polyester substrate suppliers, specialized sublimation print producers, contract apparel decorators, and global distributors of sublimation hardware and inks. Decision-makers interviewed included VP-level Sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads across North America, Europe, and Asia Pacific.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Sustainability & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Polyester & Substrate Suppliers | 30% |
| Sublimation Print Producers | 35% |
| Hardware & Ink Manufacturers | 20% |
| Distributors & Fulfillment Platforms | 15% |
We validate primary findings against UN Comtrade textile and apparel trade flows, WTO tariff and trade statistics, US ITC and Eurostat data, corporate 10-K and SEC filings from hardware and fulfillment vendors, patent databases tracking sublimation and heat-press innovation, and recognized non-profit standards bodies including OEKO-TEX and the Global Recycled Standard.
We triangulate a Top-Down macroeconomic and industry-segment allocation against a Bottom-Up model of manufacturer capacity, product pricing, and end-use consumption. Divergences are reconciled through elasticity adjustment and cross-border trade-flow analysis.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |