 Luxury Leather Goods Market
 Size, Share & Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 223

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Luxury Leather Goods Market
Vijayashree Ugale
Research Analyst

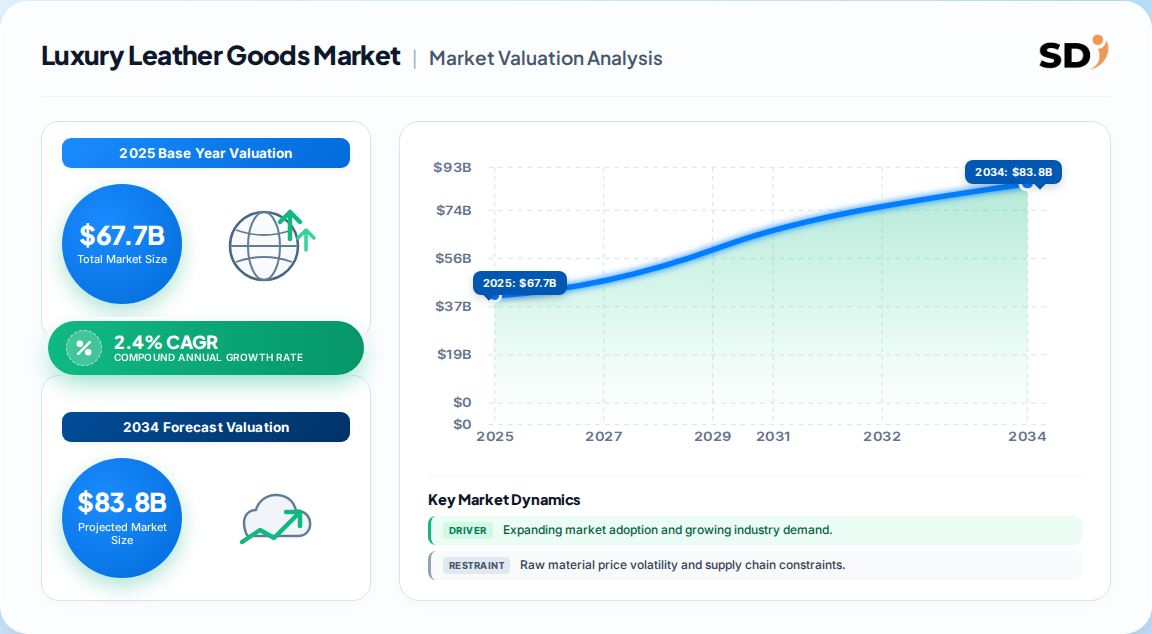
| Year | Market Size |
|---|---|
| 2025 | 67.70 B |
| 2026 | 69.30 B |
| 2027 | 71.00 B |
| 2028 | 72.70 B |
| 2029 | 74.40 B |
| 2030 | 76.20 B |
| 2031 | 78.10 B |

The luxury leather goods market covers premium-branded handbags, luggage, small leather accessories and related craft-intensive items sold at luxury price points, where brand equity, artisanal construction and material provenance drive willingness to pay. It excludes mass-market leather, footwear-led categories and artisanal production unaffiliated with major luxury houses.
This report covers luxury-range handbags, travel luggage, small leather goods (wallets, cardholders, belts) and premium accessories, segmented by product, end user, price tier and distribution channel across five global regions. This analysis does not cover mass-market leather footwear, luxury apparel, leather upholstery, automotive leather, or artisan workshops operating outside the covered luxury houses.
Published estimates diverge sharply because each house draws the luxury boundary differently — pure-luxury bags versus a broad basket that folds footwear and accessories into the total.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 67.7 Billion | 2025 | 2035 (85.7 Billion) | 2.4% | Pure luxury bags, luggage, small leather goods | One published estimate |
| 140.55 Billion | 2023 | 2030 | 5.4% | Adds footwear, apparel and accessories | A competing analysis |
| ~476 Billion | 2026 | 2032 (675.7 Billion) | 5.96% | Full leather goods including mass tier and footwear | A competing analysis |
Our analysis treats the 67.7 Billion figure as the most defensible pure-play luxury benchmark, because it isolates branded leather categories and aligns with reported revenue of the leading houses. The 476 Billion figure is a whole-category leather goods number rather than a luxury measure, and should not be substituted into luxury planning. Buyers should note the 2.4% to 5.4% growth spread implies very different reinvestment cases.
Segmentation matters because margin, growth and channel economics are uneven across the product and end-user split — bags and women's lines fund the portfolio today.
| Parent segment | Children | 2025 read |
|---|---|---|
| Product type | Bags, Luggage, Small leather goods, Others | Bags 36.9 Billion, ~2.7% CAGR |
| End user | Women, Men, Unisex | Women ~59% share, 2.6% CAGR |
| Price tier | Premium, Ultra-luxury | Premium fastest-growing tier |
| Distribution channel | Exclusive boutiques, Specialty stores, Online, Airports | Online fastest-growing; boutiques still dominant |
Bags act as the demand anchor, while small leather goods deliver high-frequency entry purchases and giftable price points. Online and airport channels are structurally outperforming, which compresses the boutique-only operating model.
The geography tree below shows how the market nests — Asia Pacific is the largest revenue pool, Europe the fastest-growing, and the Gulf a high-value travel-retail pocket.
| Region | Market Share (%) |
|---|---|
| North America | 0.22% |
| Europe | 0.24% |
| Asia-Pacific | 0.44% |
| South America | 0.04% |
| Middle East & Africa | 0.06% |
| Region | Share |
|---|---|
| Asia Pacific | 44% |
| Europe | 24% |
| North America | 22% |
| Middle East & Africa | 6% |
| Latin America | 4% |
The Asia Pacific concentration is a double-edged exposure: it underwrites scale but imports Chinese demand volatility directly into group revenue. Our analysis suggests Europe's growth premium is largely a travel-retail and tourist-recovery effect rather than a structural reset of the demand base.
Growth is being carried by premiumisation and emerging-market affluence, while counterfeit leakage and raw-material regulation cap the upside.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising disposable income in emerging markets | Driver | High | Expands first-time luxury buyers |
| Premium and status-driven demand | Driver | High | Supports price increases above volume |
| Sustainability and certified leather sourcing | Driver | Medium | Protects brand licence to operate |
| Digitalisation and e-commerce | Driver | High | Widens access, lowers entry friction |
| Customisation and personalisation | Driver | Medium | Lifts basket and loyalty |
| Counterfeiting and brand dilution | Restraint | High | Diverts spend, erodes exclusivity |
| Raw-material cost volatility | Restraint | Medium | Pressure on gross margin |
| EU chemical and animal-welfare regulation | Restraint | Medium | Compliance cost and sourcing constraints |
The balance favours pricing power over volume. With the pure-luxury base CAGR near 2.4%, growth is arithmetic of mix and price, not unit expansion — a critical distinction for anyone building a five-year plan.
The competitive field is an oligopoly: five houses hold roughly 65% of revenue and set the category's pricing and desirability agenda.
| Company | Portfolio strength | Strategic posture |
|---|---|---|
| LVMH | Louis Vuitton, Loewe, Rimowa | Scale leader; >35% share, vertical integration |
| Kering | Gucci, Saint Laurent, Bottega Veneta | Design-led repositioning, brand heat cycles |
| Hermès | Birkin, Kelly, saddlery | Scarcity and waitlist moat, highest pricing power |
| Chanel | Classic flap, small leather goods | Price harmonisation, direct-to-consumer control |
| Prada | Prada, Miu Miu | Trend agility, younger-client traction |
| Tapestry / Capri | Coach, Michael Kors | Accessible-luxury volume tier |
Moats rest on heritage narrative, controlled distribution and supply scarcity rather than manufacturing scale. The accessible-luxury tier competes on a different axis — replenishment speed and outlet discipline — leaving it more exposed to discounting.
Selection criteria in this category are brand equity, provenance documentation and channel control, not unit price. Procurement teams should require Leather Working Group–certified tannery sourcing and full chemical conformity with EU restrictions, because non-compliance is now a sale-blocking condition rather than a reputational nicety. Switching costs are high and asymmetric: multi-year tannery qualification cycles and artisanal capacity mean supply cannot be flexed quickly when a colourway sells out. Operators should also model counterfeiting leakage as a real revenue deduction in high-growth markets, and treat airport and online channels as separate P&Ls with distinct assortment. Finally, bespoke and monogram services are becoming table stakes for retention; the full report details per-segment channel economics and vendor benchmarking.
The balance of evidence favours a defensive, price-led growth thesis over a volume-led one. The 2.4% pure-luxury CAGR is credible because it reconciles with reported house performance and the oligopoly's deliberate scarcity management; the higher 5.4%–7.0% figures borrow growth from mass and footwear tiers that luxury operators do not monetise. The strongest counter-argument is that Asia Pacific affluence and travel-retail recovery could reaccelerate pure-luxury demand beyond the consensus range — a scenario worth stress-testing, but not one to underwrite as the base case.
Our view is that the winners will be those converting heritage into certified-material and personalisation narratives, protecting price while volume stays flat. Accessible-luxury players face the sharper margin risk: they lack scarcity protection and sit closest to counterfeit substitution.
Evidence that would change this conclusion: sustained double-digit Asia Pacific luxury spend, or a regulatory rollback of EU chemical restrictions, either of which would justify a more aggressive volume-led strategy.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.4% from 2020-2034 |
| Segmentation |
|
The pure-luxury segment grows at roughly 2.4% annually from 2026 to 2035, reaching about 85.7 Billion. Broader leather goods definitions report 5–6%, but those include mass and footwear tiers outside luxury scope.
Bags dominate, generating 36.9 Billion in 2025 and growing near 2.7%. Designer handbags and crossbody styles, amplified by social media and celebrity endorsement, drive the segment's outperformance.
Asia Pacific leads with roughly 44% of global revenue, anchored by China, Japan and India. Europe is the fastest-growing region, supported by travel-retail and tourism recovery.
LVMH leads with over 35% share. Together with Kering, Hermès, Chanel and Prada, the top five control about 65% of the market, reflecting a highly concentrated oligopoly.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our 70/30 primary-to-secondary research split anchors every figure in this study. We conducted in-depth interviews across the luxury leather value chain, spanning certified tannery and raw-material suppliers, specialised atelier and contract producers, hardware and lining component formulators, and global distributors plus travel-retail operators. Interviewees were decision-makers holding VP of Sourcing, Head of Product Development, Technical Director and Commercial Operations Lead designations, ensuring operational reality informed each sizing assumption.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing | 30% |
| Head of Product Development | 28% |
| Technical Directors | 24% |
| Commercial Operations Leads | 18% |
| Company Type | Representation (%) |
|---|---|
| Certified Tannery & Raw Material Suppliers | 35% |
| Atelier & Contract Producers | 30% |
| Component & Hardware Formulators | 20% |
| Global Distributors & Travel Retail | 15% |
We cross-checked primary findings against UN Comtrade leather and leather-article trade flows, WTO tariff schedules, Eurostat and US ITC import data, corporate annual filings and investor presentations (10-K and equivalent), patent databases for material innovations, and recognised technical standards including Leather Working Group certification protocols and EU chemical restriction frameworks.
Top-down allocation from macroeconomic luxury-goods consumption and industry segment shares runs simultaneously with bottom-up modelling of manufacturer capacity, average unit pricing and end-use consumption by region. Divergences are reconciled at category level before final valuation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |