 Us Cashmere Clothing Market
: Size, Trends & Forecast 2025
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 259

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Cashmere Clothing Market
Vijayashree Ugale
Research Analyst
| Year | Market Size |
|---|---|
| 2023 | 574.0 M |
| 2024 | 607.0 M |
| 2025 | 641.0 M |
| 2026 | 676.0 M |
| 2027 | 714.0 M |
| 2028 | 754.0 M |
| 2029 | 797.0 M |

The U.S. cashmere clothing market encompasses apparel made from cashmere goat fibers—sweaters, coats, pants, tees, and accessories—sold through offline and online channels to men, women, and children. It spans luxury to premium price tiers and is shaped by ethical sourcing standards, seasonal demand cycles, and brand-driven differentiation.
This analysis covers U.S. cashmere clothing revenue across product types, end users, and distribution channels. It excludes raw cashmere fiber trading, non-apparel cashmere goods (throws, blankets), and synthetic cashmere-blend apparel where cashmere content is below 50%. This analysis does not cover animal fiber markets beyond cashmere, nor does it address adjacent luxury knitwear categories such as merino or mohair.
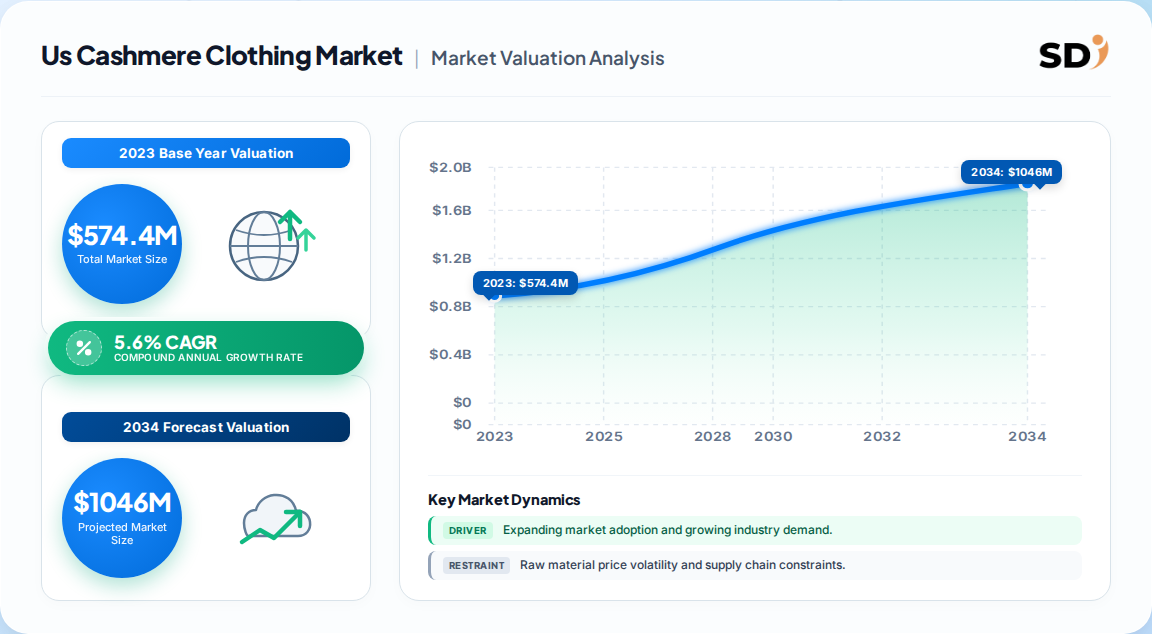
The U.S. cashmere clothing market was estimated at USD 574.4 million in 2023, with one published estimate projecting a 5.6% CAGR to 2030, while a competing analysis suggests global growth at 6.2%—implying the U.S. may grow slightly below the global average due to market maturity.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 574.4 million | 2023 | 2030 | 5.6% | U.S. cashmere clothing revenue, all channels | One published estimate |
| USD 3,545.65 million (global) | 2022 | 2030 | 6.2% | Global cashmere clothing revenue | A competing analysis |
Our analysis suggests the U.S.-specific 5.6% CAGR is more defensible for domestic planning purposes because it reflects localized demand saturation and the maturity of the luxury knitwear category. The global 6.2% figure includes high-growth Asian markets, which inflate the aggregate rate. The divergence implies that U.S. buyers should model conservatively on volume growth while pricing strategy will carry more weight.
The U.S. cashmere clothing market is segmented by product type, end user, and distribution channel, with sweaters and coats dominating revenue and offline retail driving the majority of transactions.
| Parent Segment | Children | 2023 Share | Growth Outlook |
|---|---|---|---|
| Product | Sweaters & Coats, Pants & Trousers, Tees & Polo, Others | Sweaters 53.2% | Tees & Polo fastest at 7.3% CAGR |
| End User | Men, Women, Children | Women 59.8% | Men growing at 6.0% CAGR |
| Distribution Channel | Offline, Online | Offline 63.0% | Online fastest at 7.1% CAGR |
Our analysis suggests the product mix is shifting toward lighter-weight, lower-price-point cashmere—tees and polos—which will pressure average selling prices but expand total addressable market. Vendors heavily weighted toward heavy outerwear must hedge seasonal concentration risk.
The U.S. market is national in scope, but demand concentrates in the Northeast and West, where colder climates and higher disposable income drive cashmere apparel purchasing; the South leads in absolute population-driven volume, while the Midwest shows strongest seasonal concentration.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.24% |
| South | 0.31% |
| Midwest | 0.21% |
| West | 0.24% |
| Parent Region | Child Sub-Regions |
|---|---|
| Northeast | New York, Massachusetts, Pennsylvania |
| South | Florida, Texas, Georgia |
| Midwest | Illinois, Ohio, Michigan |
| West | California, Washington, Colorado |
While precise state-level revenue splits are not uniformly disclosed, spending patterns correlate with luxury retail density. New York and California alone host a disproportionate share of high-end cashmere storefronts. This geographic concentration implies that physical retail strategies should prioritize coastal metro clusters, while digital channels offer the only scalable path to capture secondary markets.
Growth is being driven by rising demand for ethically sourced luxury apparel, expanding men's category participation, and the shift toward accessible cashmere tees and accessories, while high raw material costs and seasonality restrain faster adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Ethical sourcing standards (GCS) | Driver | High | Enables premium pricing and brand trust |
| Men's category expansion | Driver | Medium | Rising demand for coats and trousers |
| Online channel growth | Driver | High | Expands reach beyond luxury retail clusters |
| Raw cashmere price volatility | Restraint | Medium | Compresses margins for mid-tier brands |
| Seasonality concentration | Restraint | High | Limits inventory turns and cash flow |
Our analysis indicates the ethical sourcing driver is the most durable because it aligns with a structural consumer shift, not a cyclical trend. The restraint of raw material volatility is partly offset by long-term supplier contracts, but smaller brands lack that leverage—implying consolidation pressure ahead.
The U.S. cashmere clothing market is moderately concentrated, with global luxury houses and specialized domestic brands competing on brand heritage, sourcing transparency, and design innovation.
| Vendor | Positioning | Differentiation |
|---|---|---|
| Loro Piana S.p.A. | Ultra-luxury | Vertical fiber control, innovation (e.g., CashDenim) |
| Brunello Cucinelli SpA | Luxury | Italian craftsmanship, strong brand equity |
| Autumn Cashmere | Premium | Domestic design, wholesale relationships |
| 360CASHMERE | Accessible luxury | Direct-to-consumer, price accessibility |
| Ralph Lauren Corp. | Premium | Broad distribution, brand recognition |
| Erdos Group | Mid-premium | Raw material integration, scale |
Our analysis suggests the competitive moat is shifting from fiber access to supply chain transparency. Brands that can certify ethical sourcing end-to-end will command a price premium that mid-tier players cannot match without significant investment.
Procurement decisions in the U.S. cashmere clothing market hinge on fiber certification, supplier traceability, and seasonal inventory planning. Buyers should verify Good Cashmere Standard (GCS) or equivalent certifications, as ethical sourcing claims are increasingly scrutinized by consumers and regulators. Switching costs are moderate to high for established brand-supplier relationships, particularly for long-staple cashmere grades. Regulatory compliance around labeling and origin claims is strict, and misrepresentation carries reputational and legal risk. Operators should model lead times of 4–6 months for finished garments and hedge currency exposure for Italian and Scottish imports.
The balance of evidence favors a cautiously optimistic outlook for the U.S. cashmere clothing market, anchored by a 5.6% CAGR that outpaces GDP growth but trails global averages. The strongest counter-argument is that premium pricing is unsustainable as accessible cashmere expands—however, the data suggests ethical certification creates a durable price floor for certified brands.
Our analysis indicates that the most significant strategic shift is the migration of cashmere from exclusive luxury to premium-accessible. Brands that fail to develop mid-tier product lines will cede market share to digitally native competitors leveraging direct-to-consumer models and lower price points.
Investors should prioritize brands with transparent supply chains and diversified product mixes. Operators must invest in digital channel infrastructure to capture the 7.1% online CAGR.
What would change our conclusion: A sustained decline in raw cashmere prices below USD 80/kg or a regulatory shift on animal fiber labeling could disrupt the premium narrative and compress margins across the value chain.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the cashmere clothing value chain, including raw cashmere fiber suppliers, specialized knitwear producers, contract manufacturers, and global distributors. Decision-maker interviews included VP-level sourcing executives, heads of product development, technical directors, and commercial operations leads, ensuring granular insight into procurement, production, and go-to-market dynamics.
We triangulated primary findings against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K and SEC disclosures), patent databases, and recognized industry standards bodies. Non-profit technical standards such as the Good Cashmere Standard (GCS) were referenced to validate ethical sourcing claims and certification trends.
Market sizing was derived through simultaneous top-down and bottom-up modeling. Top-down allocation used macroeconomic consumption data and industry segment splits, while bottom-up modeling incorporated manufacturer capacity, product-level pricing, and end-use consumption estimates. The two approaches were reconciled to produce a defensible base-year valuation and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.6% from 2020-2034 |
| Segmentation |
|
The U.S. cashmere clothing market was estimated at USD 574.4 million in 2023 and is projected to reach approximately USD 845 million by 2030, growing at a 5.6% CAGR, according to one published estimate.
Growth is driven by rising demand for ethically sourced luxury apparel, expanding men's category participation, and the accessibility of cashmere tees and polos, which are growing at 7.3% CAGR.
Leading vendors include Loro Piana S.p.A., Brunello Cucinelli SpA, Autumn Cashmere, 360CASHMERE, Ralph Lauren Corp., and Erdos Group, competing on heritage, sourcing transparency, and design.
The market is expected to grow at a 5.6% CAGR from 2024 to 2030, with online sales accelerating at 7.1% CAGR and men's cashmere growing at 6.0% CAGR, according to one published estimate.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the cashmere clothing value chain, including raw cashmere fiber suppliers, specialized knitwear producers, contract manufacturers, and global distributors. Decision-maker interviews included VP-level sourcing executives, heads of product development, technical directors, and commercial operations leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 40% |
| Product Development Heads | 35% |
| Technical Directors | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Cashmere Fiber Suppliers | 40% |
| Specialized Knitwear Producers | 35% |
| Global Distributors & Retailers | 25% |
We triangulated primary findings against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K and SEC disclosures), patent databases, and recognized industry standards bodies such as the Good Cashmere Standard (GCS).
Market sizing was derived through simultaneous top-down and bottom-up modeling. Top-down allocation used macroeconomic consumption data and industry segment splits, while bottom-up modeling incorporated manufacturer capacity, product-level pricing, and end-use consumption estimates. The two approaches were reconciled to produce a defensible base-year valuation and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
