 Europe Decorated Apparel Market
 Outlook 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 195

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Europe Decorated Apparel Market
Vijayashree Ugale
Research Analyst

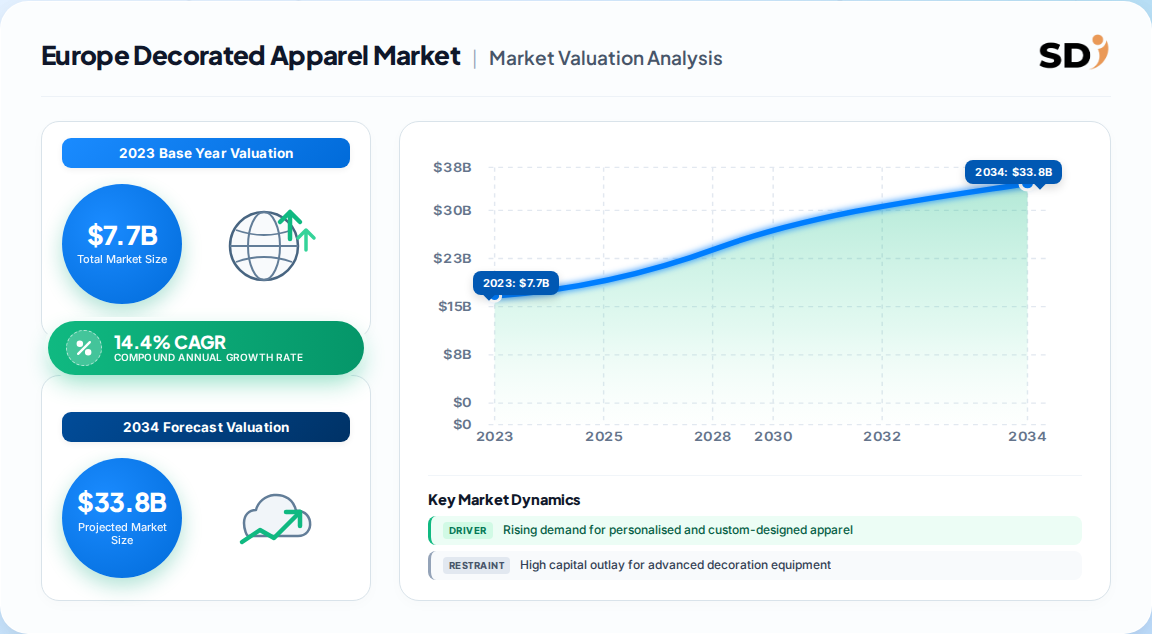
| Year | Market Size |
|---|---|
| 2023 | 7.700 B |
| 2024 | 8.800 B |
| 2025 | 10.10 B |
| 2026 | 11.50 B |
| 2027 | 13.20 B |
| 2028 | 15.10 B |
| 2029 | 17.30 B |

Europe decorated apparel refers to garments embellished with embroidery, screen printing, dye sublimation, digital printing or other techniques for branding, personalisation or fashion. The regional market generated approximately 7.7 Billion in 2023 and is forecast to reach 19.7 Billion by 2030, growing at 14.4% CAGR.
This analysis covers Europe's decorated apparel revenue across embroidery, screen printing, dye sublimation, digital printing and other decoration methods, segmented by end user (men, women, children) and by distribution channel (offline, online). It spans 2018–2030 with 2023 as base year. This analysis does not cover undecorated blank garment manufacturing, textile dyeing as a standalone industrial process, pure apparel retail, or decoration equipment hardware sales.
Europe's decorated apparel market sits at roughly 7.7 Billion (2023), with a forecast of 19.7 Billion by 2030 at 14.4% CAGR — a growth rate that outpaces most global benchmarks and implies Europe is the fastest-growing decorated apparel region, not merely a mature one.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 7,698.4 Million | 2023 | 2030 | 14.4% | Europe region, product + end user, decorated garments only | One published industry estimate |
| 19,723.9 Million | 2023 | 2030 | 14.4% | Same scope, forecast revenue | Same published estimate |
| ~42.3 Billion | 2026 | 2034 | 12.9% | Global decorated apparel, all regions | A competing analysis |
| ~28.7 Billion | 2026 | 2033 | 12.8% | Global, incl. distribution channel split | Another competing analysis |
| ~32.2 Billion | 2025 | 2034 | 7.0% | Global, conservative growth assumption | A third-party benchmark |
Our analysis suggests the 14.4% European figure is defensible but should be treated as an upper-bound case. The global CAGRs cluster at 12.8–13.0%, and Europe's 26.6% global revenue share is high relative to its apparel production base. The divergence implies Europe's growth is value-led (premium, short-run, compliance-driven decoration) rather than volume-led. Buyers should model 11–13% as a conservative planning case and reserve 14.4% for upside scenarios.
Europe's decorated apparel market segments primarily by decoration technology, then by end user and channel. Embroidery led 2023 revenue at 40.7%, while screen printing is identified as the fastest-growing segment through 2030, reflecting volume recovery in promotional and teamwear.
| Parent segment | Children | 2023 position |
|---|---|---|
| Product / technology | Embroidery, Screen Printing, Dye Sublimation, Digital Printing, Others | Embroidery largest (~40.7%); screen printing fastest-growing |
| End user | Men, Women, Children | Men historically dominant in workwear/promotional; children fastest-growing globally |
| Distribution channel | Offline, Online | Offline still majority; online the structural growth channel |
Implication: the fastest-growing technology (screen printing) and the largest (embroidery) are not the same, which means decorators must run dual capability rather than consolidate onto one platform. Digital and sublimation sit between them, absorbing short-run and personalised demand.
Germany is projected to register the highest country-level CAGR through 2030, while Western Europe — led by Germany, the UK and France — concentrates the region's corporate, promotional and premium fashion demand. Central and Eastern Europe is the cost-competitive decoration base.
| Region | Market Share (%) |
|---|---|
| Western Europe | 0.34% |
| Southern Europe | 0.22% |
| Northern Europe | 0.21% |
| Central & Eastern Europe | 0.23% |
| Parent | Children |
|---|---|
| Western Europe | Germany, UK, France, Netherlands, Belgium |
| Southern Europe | Italy, Spain, Portugal |
| Northern Europe | Sweden, Denmark, Finland, Norway |
| Central & Eastern Europe | Poland, Czechia, Romania, Hungary |
Germany's lead stems from its industrial workwear, automotive and trade-show promotional base — structurally recurring, contract-driven demand rather than fashion-cycle exposure. Poland's role is supply-side: Lynka's Skawina operation illustrates CEE's emergence as a near-shore decoration hub serving Western European brands. This implies a two-speed geography: demand concentrates in the west, production capacity migrates east, and logistics cost per unit becomes a decisive competitive variable.
Growth is driven principally by personalisation demand, e-commerce and print-on-demand economics, and recurring corporate, sports and licensed merchandise programmes. Restraints are capital intensity, raw-material and operating-cost inflation, and fabric-compatibility complexity across varied garment portfolios.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Personalisation and self-expression demand | Driver | High | Bespoke graphics raise per-unit value and repeat purchase |
| E-commerce and print-on-demand | Driver | High | Removes inventory risk; 44.4% of decorators prioritise e-commerce investment |
| Corporate, sports and licensed merchandise | Driver | High | Recurring, seasonal, contract-based order flow |
| Digital and AI-enabled design workflows | Driver | Medium-High | Faster turnaround, lower design cost, mass customisation |
| Sustainability and eco-friendly inks | Driver | Medium | Regulatory push plus brand procurement requirements |
| Equipment capital outlay | Restraint | High | 100,000–500,000 USD for full production setup |
| Raw material and cost inflation | Restraint | High | Operating cost inflation of 6.5% reported in Q1 2024 |
| Fabric-compatibility complexity | Restraint | Medium | Wrong process raises rejects, rework and quality-control cost |
The balance favours growth, but not evenly. Demand-side drivers are structural and compounding; restraints are largely executional and financeable. The decisive constraint is capital: small decorators outsource or defer upgrades, ceding share to better-capitalised, digitally integrated players. Our analysis suggests consolidation pressure will intensify through 2030.
Europe's decorated apparel landscape is fragmented, spanning North American blank-and-decoration majors (Gildan, Hanesbrands, Delta Apparel, Berkshire Hathaway's apparel operations) and European-focused decorators such as Advance Printwear (UK) and Lynka (Poland), with no vendor holding dominant regional share.
| Company | HQ | Scale signal | Strategic position |
|---|---|---|---|
| Gildan Activewear | Canada | Large-scale blank apparel | Vertical blank supply plus decoration partner ecosystem |
| Hanesbrands | USA | ~48,000 employees | Brand portfolio, promotional and retail channels |
| Delta Apparel | USA | ~6,000 employees | Blank and decorated apparel, print-on-demand capability |
| Berkshire Hathaway (apparel) | USA | ~396,500 group employees | Portfolio scale, distribution reach |
| Advance Printwear | UK | Small, specialist | UK garment decoration and supply |
| Lynka | Poland | 251–500 employees | CEE decoration and contract production hub |
Differentiation rests less on decoration technique than on three moats: blank-garment supply control, fulfilment speed and compliance-grade traceability. Vertically integrated players that own blanks, decoration and logistics compress lead times — the single metric corporate and DTC buyers now weight most heavily. Specialist European decorators compete on service intimacy and near-shore responsiveness rather than price.
Procurement decisions in Europe turn on four mission-critical criteria: decoration durability under repeated industrial washing, colour consistency across batches, supplier lead-time reliability, and documented material compliance. Buyers should contract on measurable tolerances rather than sample approval alone — colour drift and adhesion failure are the most common cause of rejected decorated orders.
Switching costs are moderate but asymmetric. Blank garment supply is relatively substitutable; decorated programme transitions are not, because artwork files, screen or embroidery-digitisation libraries, and approved colour standards sit with the incumbent. Operators should therefore negotiate ownership of design files and digitisation assets at contract outset. Regulatory exposure centres on chemical compliance for inks and finishes, textile labelling, and increasingly on extended producer responsibility and eco-design obligations — meaning sustainable, water-reduced decoration is becoming a procurement gate, not a differentiator. Capital intensity compounds all of this: buyers without in-house decoration capacity inherit supplier lead-time risk.
The balance of evidence favours a premiumisation thesis over a volume thesis for Europe. A 14.4% CAGR against a 26.6% global revenue share is internally inconsistent with volume-led growth; it implies Europe is converting mix toward high-value, short-run, compliance-certified decoration. Operators who read the number as a demand boom will over-invest in bulk screen capacity.
The strongest counter-argument is that screen printing's flagged fastest-growth status signals a genuine volume recovery as promotional, teamwear and event demand normalises post-pandemic. That is credible — but screen printing's growth is likely concentrated in automated, short-setup configurations, not legacy manual presses. Our analysis suggests the two theses are compatible: volume returns, but only through capital-efficient equipment.
Actionable strategy:
What would change this conclusion: a sustained reversal in European operating-cost inflation, or regulatory clarification that materially lowers compliance cost for small decorators, would shift value back toward fragmented, low-capital specialists. Conversely, evidence of accelerating digital substitution above 47% of decoration volume by 2026 would make the premiumisation case decisive.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.4% from 2020-2034 |
| Segmentation |
|
Europe's decorated apparel market was valued at approximately 7.7 Billion in 2023 and is forecast to reach about 19.7 Billion by 2030. That represents a 14.4% compound annual growth rate, positioning Europe among the fastest-growing regional decorated apparel markets worldwide.
Embroidery was the largest product segment in 2023, accounting for roughly 40.7% of European decorated apparel revenue. Its durability and premium perception make it dominant in corporate uniforms, workwear and branded premium apparel, where decoration must survive repeated industrial washing.
Germany is projected to record the highest CAGR between 2024 and 2030, driven by industrial workwear, automotive branding and trade-show promotional demand. Poland is also significant as a near-shore decoration production hub serving Western European brands.
Personalisation demand, e-commerce and print-on-demand economics, plus recurring corporate, sports and licensed merchandise programmes. Sustainability requirements and AI-enabled design workflows are emerging accelerators, while equipment capital costs and raw material inflation remain the principal restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research programme applies a 70/30 primary-to-secondary split. Structured depth interviews were conducted with stakeholders across the decorated apparel value chain: blank garment and fabric suppliers, specialist decorators and embroidery houses, inks and consumables producers, contract print-on-demand platforms, and pan-European distributors. Interviewees were drawn from decision-making roles including VP-level Sourcing, Head of Production, Technical and Quality Directors, and Commercial Operations Leads. Interview content was cross-checked against observed order-book behaviour and capacity utilisation data to limit stated-preference bias.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Production & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Blank Garment & Fabric Suppliers | 30% |
| Specialist Decorators & Embroidery Houses | 35% |
| Inks, Consumables & Equipment Producers | 20% |
| Distributors & Print-on-Demand Platforms | 15% |
We triangulate against official multilateral sources — UN Comtrade and Eurostat textile and apparel trade flows, WTO tariff schedules, and national statistics offices — alongside corporate annual filings (10-K and investor presentations) for listed decorated apparel participants. Patent filings in digital textile printing and embroidery automation inform technology substitution curves. Sector association reporting from printing and apparel decoration trade bodies provides qualitative demand context. No competitor market-research publications are used as validation sources.
Sizing runs simultaneously top-down and bottom-up. Top-down, we allocate European apparel consumption by decoration technology and end-use intensity using macroeconomic and retail data. Bottom-up, we model decorator capacity, throughput, average selling price and order frequency, aggregating to a regional total. Convergence between the two approaches defines the confidence band around the base-year figure.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |