 Alpaca Apparel Accessories Market
: 2026 Global Outlook
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 279

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Alpaca Apparel Accessories Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 753.0 M |
| 2026 | 805.0 M |
| 2027 | 873.0 M |
| 2028 | 946.0 M |
| 2029 | 1.030 B |
| 2030 | 1.110 B |
| 2031 | 1.210 B |

The alpaca apparel and accessories market covers garments and fashion items made from alpaca fleece—sweaters, coats, scarves, shawls, hats, gloves, socks, and lifestyle accessories. Valued for softness, thermal regulation, hypoallergenic comfort, and biodegradability, the category sits at the intersection of luxury fashion, sustainable textiles, and functional cold-weather wear.
This analysis covers finished alpaca garments (apparel) and non-garment accessories across men, women, and children, sold through online and offline channels in North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. It examines fiber-to-shelf value chains, pricing dynamics, and vendor positioning. This analysis does not cover raw alpaca fiber trading as a standalone commodity, synthetic and cellulosic blends without alpaca content, or textile machinery markets.
Published estimates cluster between $689.7 million and $805.2 million for the 2025–2026 base period, with 2030–2033 forecasts spanning $1.09 billion to $1.41 billion. The dispersion reflects differing base years, channel coverage, and treatment of blended products.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| $753.4M → $1,412.0M | 2025 | 2033 | 8.4% | Global finished apparel + accessories, online/offline | One published estimate (2025) |
| $805.2M → $1,412.0M | 2026 | 2033 | 8.4% | Same scope, 2026 base restatement | Same publisher, updated series |
| $682.7M → $1,279.7M | 2023 | 2032 | 7.2% | Global, product/end-user/channel segmentation | A competing analysis (2023) |
| $689.7M → $1,101.1M | 2025 | 2031 | 8.11% | Global, includes hypermarket/specialty split | A competing analysis (2026) |
| $1,358.9M (2033) | 2025 | 2033 | 8.2% | Global, women/men end-user, offline/online | A competing analysis (2026) |
Our analysis suggests the $753.4 million (2025) base with an 8.4% CAGR is the most defensible central case. It aligns with ADEX-reported export growth of 33% in early 2024 and PROMPERÚ's $214 million in Peruvian alpaca product exports in 2023. The lower-CAGR estimates likely reflect wider channel definitions that dilute premium pricing.
Segmentation follows three non-geographic axes—product, end user, and distribution channel—each with a dominant incumbent and a faster-growing challenger.
| Parent segment | Children | 2025 share | Growth signal |
|---|---|---|---|
| Product | Apparel, Accessories | Apparel 73.8% | Accessories ~9.0% CAGR |
| End user | Women, Men, Children | Women 74.1% | Children ~9.4% CAGR |
| Distribution channel | Offline, Online | Offline 70.2% | Online ~9.0% CAGR |
Implication: Incumbency is concentrated in apparel, women, and offline—but incremental growth is migrating to accessories, children, and digital. Vendors optimizing only for the dominant segments will underperform the market CAGR.
North America leads with 36.8% of 2025 global revenue, underpinned by high disposable income, a mature sustainable-fashion consumer base, and strong DTC brand penetration. The U.S. is the single largest country market, with Canada a secondary premium buyer.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.24% |
| Asia Pacific | 0.19% |
| Latin America | 0.14% |
| Middle East & Africa | 0.08% |
| Parent region | Countries / sub-markets |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain, Netherlands |
| Asia Pacific | China, Japan, India, South Korea, Indonesia, Malaysia |
| Latin America | Peru, Argentina, Brazil, Mexico |
| Middle East & Africa | UAE, Saudi Arabia, Israel, South Africa |
| Region | 2025 share |
|---|---|
| North America | 36.8% |
| Europe | 23.5% |
| Asia Pacific | 18.5% |
| Latin America | 13.5% |
| Middle East & Africa | 7.7% |
Europe's strength is in luxury fashion houses and heritage knitwear; Asia Pacific grows on rising disposable income and fabric awareness; Latin America is the production heartland and fastest-growing consumer base (~9.6% CAGR), led by Peru.
Demand-side forces are structural and durable; supply-side constraints are concentrated and climate-exposed. The net balance favors growth, but with a ceiling imposed by fiber availability.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Sustainable/premium fiber demand | Driver | High | Lower water/land footprint vs. cotton; luxury adoption |
| Ethical sourcing & traceability | Driver | High | 90,000+ Peruvian producers; certification programs |
| E-commerce & DTC expansion | Driver | High | Brands bypass physical retail; global niche access |
| Fiber supply concentration | Restraint | High | Peru ~80% of commercial fiber; climate volatility |
| High production cost | Restraint | Medium | Specialized harvesting/sorting; premium retail pricing |
| Animal welfare compliance costs | Restraint | Medium | Certification and audit overheads |
Our analysis suggests the binding constraint is not demand but supply. Climate-driven herd volatility in the Andes creates a structural bottleneck that no amount of marketing spend can resolve—making supply security the true competitive moat.
The market is highly fragmented and heritage-led, with vertically integrated Peruvian groups, luxury houses, specialist DTC brands, and artisan cooperatives competing on fiber access, brand story, and channel reach.
| Vendor | Positioning | Core strength |
|---|---|---|
| Incalpaca / KUNA & Alpaca 111 | Peruvian heritage, branded fashion | Fiber access, textile capability, international reach |
| Michell & Cía. / Sol Alpaca | Vertically integrated processor | Yarn-to-consumer platform, premium finishing |
| Peruvian Connection | Artisan-inspired knitwear | DTC strength in North America and Europe |
| PAKA Apparel | Outdoor/performance alpaca | Functional positioning, sustainability narrative |
| Alicia Adams Alpaca | Luxury lifestyle | Design-led, farm-based identity |
| Alpaca Direct | Specialist retail | Broad portfolio, yarn and accessories |
| Loro Piana | Luxury fashion house | Brand prestige, premium fiber sourcing |
Differentiation rests on three moats: fiber access (Peruvian vertical integration), traceability credentials (certifications, fair-trade programs), and narrative authenticity (Andean heritage, farm-to-garment storytelling). Pure-play brands without supply linkage face margin compression as fiber costs rise.
Procurement decisions hinge on verifying fiber origin and certification, because a single supply disruption in the Andes propagates globally. Buyers should demand traceability documentation, animal-welfare compliance, and consistent micron grading—baby alpaca versus standard grades materially affect price and hand-feel. Switching costs are moderate: fiber sourcing can be re-routed, but brand equity tied to Peruvian provenance is hard to replicate. Regulatory exposure is low compared to chemical-intensive categories, but emerging animal-welfare and eco-labeling rules in the EU and North America raise compliance overhead. Operators should model climate risk into forward contracts and build dual-sourcing relationships with cooperatives to hedge concentration risk.
The balance of evidence favors supply-secured, digitally native operators over volume-driven generalists. Demand is structurally sound—sustainability, premiumization, and e-commerce tailwinds are durable—but the fiber ceiling means growth is zero-sum at the raw-material level. Brands that lock in long-term cooperative partnerships and certification-backed traceability will capture disproportionate margin. The strongest counter-argument is that a global recession could compress premium discretionary spend faster than expected, but the 2024 export data (+33% in early-year fiber derivatives) suggests resilience even in softer macro conditions.
A second-order effect deserves attention: the shift toward undyed, natural-color collections (e.g., black alpaca genetics programs) reduces dyeing costs and water use, simultaneously cutting production expense and strengthening the sustainability narrative. This is a rare margin-and-marketing win. Our analysis suggests accessory-led entry (socks, scarves, hats) is the lowest-friction route to new customers, with conversion to higher-ticket apparel following.
Actionable Strategy:
What would change our conclusion: a sustained collapse in Peruvian herd health, or EU regulatory action restricting animal-fiber labeling, would materially lower the growth trajectory and shift advantage to synthetic-blend competitors.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.4% from 2020-2034 |
| Segmentation |
|
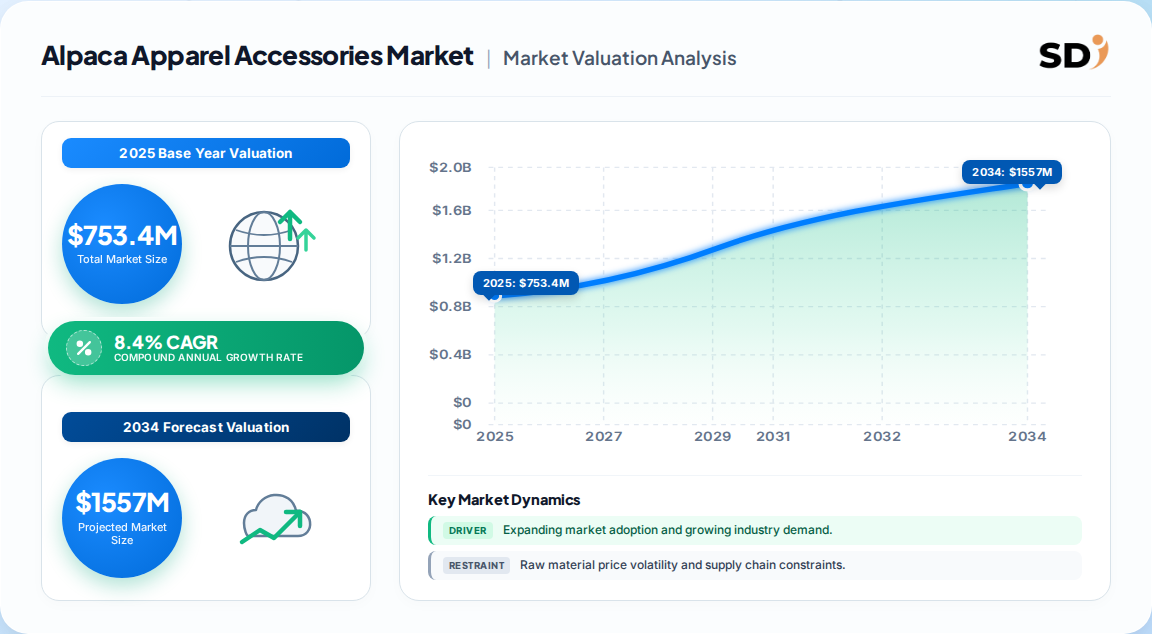
The global market was valued at approximately $753.4 million in 2025 and is projected to reach $1.41 billion by 2033, growing at an 8.4% CAGR. Competing estimates range from $689.7 million to $805.2 million for the base period due to differing scope definitions.
Accessories is the fastest-growing product segment at roughly 9.0% CAGR, driven by hats, gloves, socks, and scarves. Children's apparel grows fastest by end user at ~9.4% CAGR, and online distribution leads channel growth at ~9.0% CAGR.
North America leads with 36.8% of global revenue in 2025, supported by high disposable income and mature sustainable-fashion demand. The U.S. is the largest single country market, while Latin America is the fastest-growing region at ~9.6% CAGR.
Fiber supply concentration is the primary constraint—Peru produces roughly 80% of global commercial alpaca fiber, leaving supply vulnerable to Andean climate events. High production costs and specialized processing further limit scalability and keep retail prices premium.
Key players include Incalpaca/KUNA, Michell & Cía./Sol Alpaca, Peruvian Connection, PAKA Apparel, Alicia Adams Alpaca, Alpaca Direct, and luxury houses such as Loro Piana. The market is highly fragmented and heritage-led, with vertical integration a key competitive moat.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the alpaca value chain, including raw fiber producers and cooperatives, vertically integrated textile mills, specialized apparel manufacturers, luxury and DTC brand operators, and global distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of Product Development, Technical and Quality Directors, and Commercial Operations Leads. Interview programs were structured to capture fiber availability, pricing pass-through, channel economics, and certification requirements.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Product Development & Design Heads | 28% |
| Quality & Compliance Directors | 22% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Fiber Producers & Cooperatives | 30% |
| Textile Mills & Processors | 28% |
| Apparel & Accessory Manufacturers | 27% |
| Distributors & Retail Brands | 15% |
Secondary validation draws on official multilateral databases—UN Comtrade, WTO tariff and trade statistics, US ITC, and Eurostat—alongside corporate annual filings (10-K, investor presentations), patent databases, and recognized industry associations. Trade flow data from Peruvian export authorities and international fiber associations were cross-referenced to corroborate volumetric and value estimates. No third-party market-research publisher data is used as a validation source.
Market sizing triangulates a Top-Down allocation (macroeconomic consumption, apparel segment shares, regional disposable income) with a Bottom-Up model (manufacturer capacity, fiber volume, average selling price, and end-use consumption). The two approaches are reconciled to produce a single base-year value and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow & consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |