 Emulsifiers Personal Care Market
 Size, Trends & 2036 Forecast
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 210

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Emulsifiers Personal Care Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2026 | 612.0 M |
| 2027 | 638.0 M |
| 2028 | 664.0 M |
| 2029 | 691.0 M |
| 2030 | 719.0 M |
| 2031 | 749.0 M |
| 2032 | 779.0 M |

The Emulsifiers Personal Care Market comprises surface-active ingredients that stabilize oil–water mixtures in creams, lotions, serums, sunscreens and hair-care products. It spans plant-derived and synthetic chemistries—polyglycerol esters, sucrose esters, lecithin, lactic esters, polysorbates and amino-acid systems—sold to cosmetic formulators and contract manufacturers.
This analysis covers emulsifier ingredients sold into skin care, hair care, make-up and other personal care applications, segmented by product chemistry, product format (O/W, W/O), source (natural, synthetic) and region. It excludes food-grade emulsifiers, pharmaceutical excipients sold under drug master files, industrial surfactants, and oilfield chemicals. This analysis does not cover finished cosmetic products, packaging, or fragrance and preservative ingredient classes.
Estimates diverge because publishers define the category differently—some count only cosmetic-grade emulsifiers, others bundle all personal care surfactants. The table below reconciles the competing figures.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 612.42 Million (2026) → 915.29 Million | 2026 | 2036 | 4.1% | Emulsifiers sold into personal care only | One published estimate |
| 712 Million (2023) → 1,298 Million | 2023 | 2033 | 6.9% | Cosmetic emulsifiers, narrow cosmetic definition | A competing analysis |
| 22.8% of 8.98 Billion global emulsifiers (~2.05 Billion) | 2025 | 2034 | ~5.5% | Personal care share of total emulsifiers | A third published estimate |
The 612.42 Million → 915.29 Million trajectory is the most defensible for this market: it is the only series scoped exclusively to personal care emulsifiers, and its 4.1% CAGR is consistent with mature, regulation-driven substitution rather than volume-led expansion. Our analysis suggests the higher 6.9% figure reflects a broader cosmetic-surfactant basket and a different base year; buyers should treat it as an upper bound, not a planning number.
The market segments primarily by chemistry, emulsion format, source and end application, with green and amino-acid chemistries the fastest-growing tiers.
| Parent Segment | Children |
|---|---|
| By Product Format | Oil-in-Water (O/W), Water-in-Oil (W/O) |
| By Product Type | Lactic Esters of Fatty Acids, Lecithin, Mono & Di-glycerides, Esters of Monoglycerides, Polysorbates, Polyglycerol Esters, PGPR, Amino-Acid Based, Others |
| By Source | Natural (Green), Synthetic |
| By Application | Skin Care, Hair Care, Make-up, Others |
O/W systems dominate at ~63.3% because lightweight, fast-absorbing textures align with hydration-led skin care. Natural/green sources hold ~63.4% of cosmetic emulsifier demand and ~72.0% of personal care emulsifiers in the narrower series—a divergence we explore below.
Asia Pacific leads the Emulsifiers Personal Care Market with roughly 42% of global revenue, driven by China and India's expanding beauty consumption and clean-label reformulation. Europe and North America follow as innovation and premiumization hubs.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.42% |
| North America | 0.25% |
| Europe | 0.24% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
| Region | Share (2026) |
|---|---|
| Asia Pacific | 42% |
| North America | 25% |
| Europe | 24% |
| Latin America | 5% |
| Middle East & Africa | 4% |
This divergence implies that Asia Pacific's lead is volume-led, while Europe's influence is standards-led: EU restrictions on ethoxylated emulsifiers effectively set the reformulation agenda globally, so European specification choices cascade into Asian contract manufacturing.
Clean-beauty regulation and plant-derived substitution are the primary growth engines, while raw-material volatility and formulation complexity cap conversion speed.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Clean-beauty certification expansion | Driver | High | Mandates natural/green emulsifier substitution |
| PEG/ethoxylate regulatory scrutiny | Driver | High | Forces reformulation toward plant and amino-acid systems |
| Premium skin care and dermocosmetics growth | Driver | High | Raises emulsifier value per formulation |
| Biotechnology-derived emulsifiers | Driver | Medium | Enables traceable, fermentation-based alternatives |
| Raw material price volatility | Restraint | High | Coconut, olive and palm feedstock swings pressure margins |
| Formulation complexity of natural systems | Restraint | Medium | Slows lab-to-scale conversion |
| Multi-region regulatory compliance | Restraint | Medium | Raises cost of global SKU harmonization |
| Synthetic emulsifier perception backlash | Restraint | Medium | Depresses polysorbate-heavy formulations |
Net, drivers outweigh restraints, but the balance is regulatory rather than demand-led. Our analysis suggests substitution is not optional for brands selling into the EU and increasingly the UK and US—compliance timelines, not consumer preference, set the pace.
BASF, ADM, DSM-Firmenich, Evonik, Kerry, Palsgaard and Stepan anchor the competitive landscape, competing on green chemistry portfolios, traceability and formulation support.
| Company | Strategic Position | Differentiator |
|---|---|---|
| BASF SE | Global leader | Broad emulsifier portfolio, formulation technical support |
| ADM | Plant-derived scale | Lecithin and bio-based feedstock integration |
| DSM-Firmenich | Innovation-led | Biotechnology and vitamin-adjacent formulation science |
| Evonik | Specialty chemistry | Amino-acid and mild surfactant systems |
| Kerry Group | Formulation solutions | Application-led personal care ingredient systems |
| Palsgaard | Emulsifier specialist | Plant-derived emulsifier focus and clean-label credentials |
| Stepan Company | Surfactant scale | Cost-efficient surfactant manufacturing |
Moat formation is shifting from chemistry breadth to certification coverage and feedstock traceability. Suppliers who can document coconut- or olive-origin emulsifiers and support customers through EU and US filings are winning specification slots earlier in the reformulation cycle.
Procurement decisions in this category hinge on regulatory defensibility, supply continuity and formulation compatibility, not unit price alone. Natural emulsifiers cost materially more than synthetic alternatives, so buyers must model total cost of reformulation—including stability testing, retesting cycles and label changes—rather than comparing per-kilogram quotes.
Switching costs are high once an emulsifier is locked into a validated formula: re-validation, stability re-testing and regulatory re-notification can consume quarters. Buyers should therefore qualify dual sources for any green emulsifier above 5% of formula weight. Feedstock volatility in coconut, olive and palm derivatives is a persistent margin risk; index-linked contracts and multi-origin qualification reduce exposure.
Compliance is the binding constraint. EU cosmetics regulation, US FDA safety requirements and expanding clean-beauty certification schemes each create distinct documentation burdens. Operators should require supplier dossiers covering origin, biodegradability and impurity profiles at RFQ stage, not post-award.
The balance of evidence favors early, deliberate substitution toward plant-derived and amino-acid emulsifiers, not because consumer demand is overwhelming, but because the regulatory trajectory in Europe and North America makes the synthetic alternative progressively harder to defend. The personal care segment's 4.1% CAGR understates the value migration: within a slow-growing unit market, the green tier is capturing a rising share of spend.
The strongest counter-argument is cost. Natural emulsifiers remain 25–60% more expensive than synthetic counterparts, and in price-sensitive emerging markets that gap can stall adoption. But our analysis suggests this is a timing argument, not a direction argument—feedstock scale-up and fermentation-derived alternatives are narrowing the gap, and brands caught mid-reformulation when restrictions tighten face the highest switching costs of all.
Actionable Strategy:
What would change our conclusion: a sustained fall in synthetic emulsifier regulatory pressure, or a feedstock shock that widens the natural–synthetic cost gap beyond 80%, would materially slow the substitution curve described here.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain—raw material and feedstock suppliers, specialty emulsifier producers, contract formulators and blenders, and global ingredient distributors—with decision-makers including VPs of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads.
Secondary validation draws on UN Comtrade and WTO trade flows, US ITC and Eurostat tariff data, corporate 10-K filings and investor presentations, patent databases, and non-profit technical standards bodies active in cosmetic ingredient safety.
Sizing triangulates top-down macroeconomic and segment allocation against bottom-up manufacturer capacity, product pricing and end-use consumption modeling, reconciling the two to a consensus base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.1% from 2020-2034 |
| Segmentation |
|
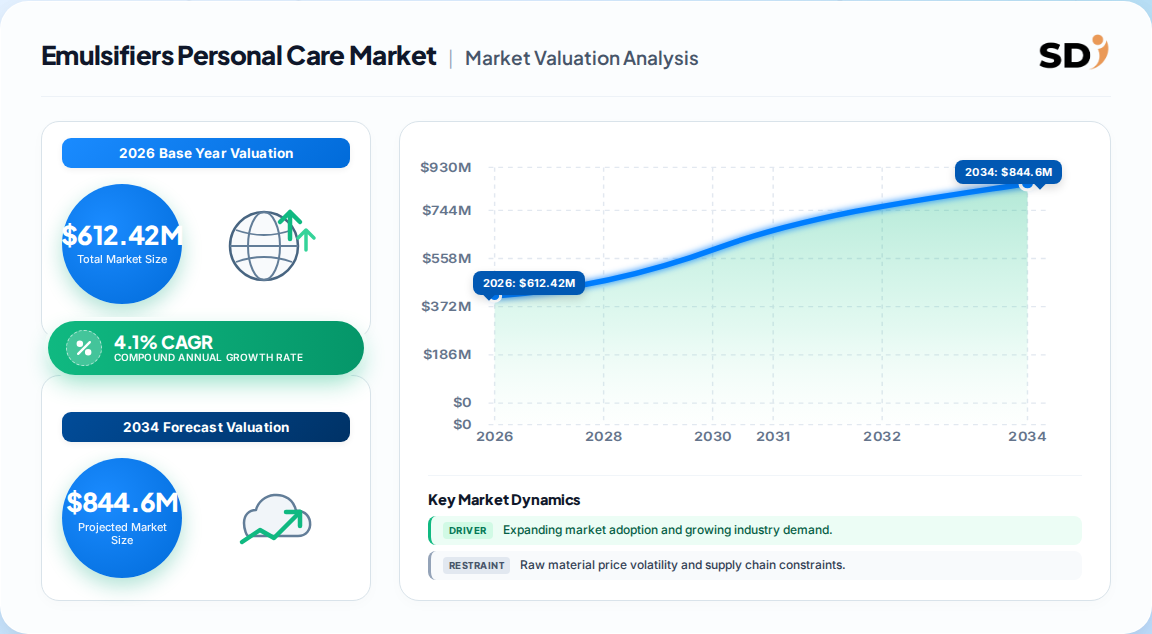
The market was valued at 612.42 Million in 2026 and is forecast to reach 915.29 Million by 2036, growing at a 4.1% CAGR over the decade.
Asia Pacific leads with roughly 42% of global revenue, driven by China and India's expanding beauty consumption and clean-label reformulation activity.
Green, plant-derived emulsifiers and amino-acid-based systems are growing fastest, supported by clean-beauty certification and tightening restrictions on ethoxylated chemistries.
BASF, ADM, DSM-Firmenich, Evonik, Kerry, Palsgaard and Stepan lead, competing on green chemistry portfolios, traceability and formulation technical support.
Regulatory scrutiny of PEG and ethoxylated emulsifiers, plus clean-beauty certification expansion, is forcing reformulation toward plant-derived and fermentation-based alternatives despite a 25–60% cost premium.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VPs of Sourcing & Procurement | 30% |
| Heads of R&D & Formulation | 35% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Feedstock Suppliers | 30% |
| Specialty Emulsifier Producers | 40% |
| Contract Formulators & Blenders | 18% |
| Global Ingredient Distributors | 12% |
This study follows a rigorous 70/30 primary-to-secondary research split. In-depth interviews were conducted across the personal care emulsifier value chain—raw material and feedstock suppliers (coconut, olive, palm and fermentation inputs), specialty emulsifier producers, contract formulators and blenders, and global ingredient distributors. Decision-makers interviewed included VPs of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, technical and commercial perspectives.
Secondary validation draws on UN Comtrade and WTO trade flow databases, US ITC and Eurostat tariff and import records, corporate 10-K and SEC filings, annual investor presentations, patent databases for bio-based emulsifier technologies, and recognized non-profit technical standards and industry association publications governing cosmetic ingredient safety and labeling.
Sizing applies simultaneous top-down macroeconomic and segment allocation against bottom-up manufacturer capacity, product pricing and end-use consumption modeling. The two streams are reconciled to a consensus base-year value, with divergence flagged and resolved through primary interview validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |