Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Law Enforcement Military Clothing Market Outlook 2025
Law Enforcement Military Clothing Market
Law Enforcement Military Clothing Market Outlook 2025
Law Enforcement Military Clothing Market by Material (Aramid, Cotton Blends, Nylon, Polyester, Modacrylic, FR Rayon, Viscose, Wool, Kermel), by Function (Flame-Resistant, Ballistic/Protective, Moisture-Wicking, Antimicrobial, Water-Resistant, Camouflage), by Product Type (Combat Uniforms, Tactical Vests & Carriers, Outerwear, Headgear, Footwear, Camouflage Clothing), by End-Use (Military/Defense, Law Enforcement/Police, Paramilitary & Border Security, Private Security), by Protection Level (Ballistic, Flame & Fire, Chemical & Biological, Standard Duty Wear), by Distribution Channel (Government Direct Contracts, Institutional Suppliers, Retail/Specialty), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Poland), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Israel) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 260
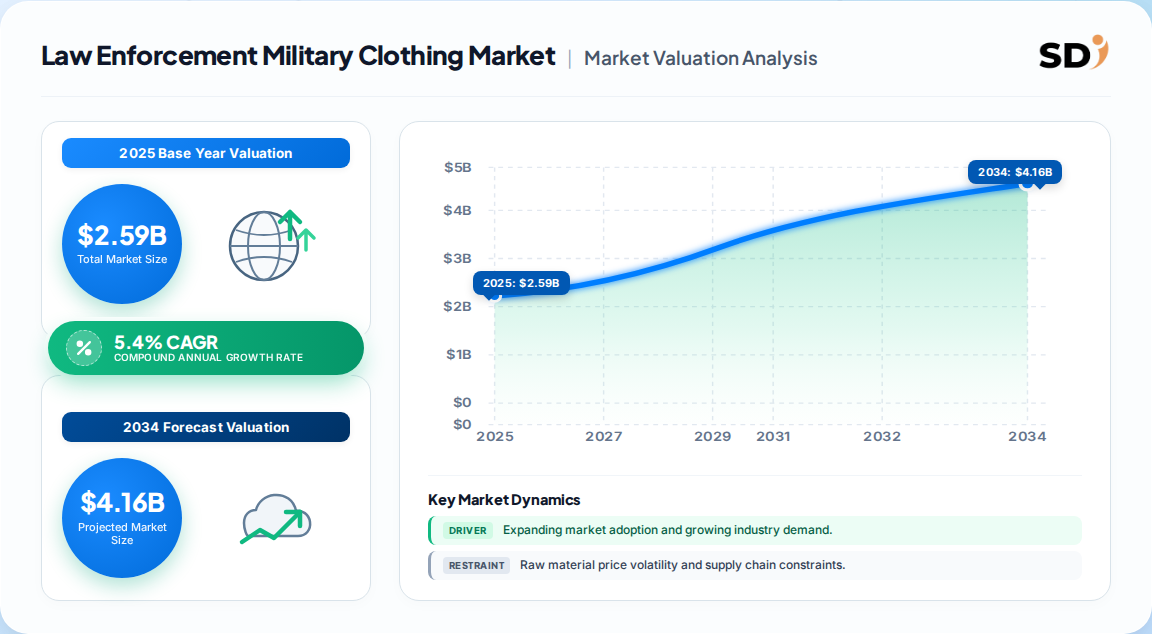
USD 2.59 billion in 2025 — the global Law Enforcement Military Clothing Market sits at a critical inflection point, projected to reach USD 3.74 billion by 2032 at a 5.4% CAGR.
Asia-Pacific leads with roughly 31% revenue share, but North America's procurement depth and sovereign-sourcing rules (Berry Amendment) keep it the highest-value per-contract region.
Flame-resistant apparel commands the largest functional segment (~39%), while aramid-based fabrics are the fastest-growing material class at a projected ~10% CAGR.
Defense end-use dominates at ~71% of revenue; law enforcement is the faster-growing buyer cohort as urban tactical modernization accelerates.
Cumulative opportunity of USD 25.17 billion over 2025–2032 — more than double the prior six-year window — signals structural, not cyclical, demand.
Point Blank, Safariland, Crye Precision, Propper, Milliken anchor a concentrated vendor field where system-based selling (uniform + plate + carrier) is becoming the default bid format.
Why this matters for decision-makers: Vendors that cannot bundle modular, MOLLE-compatible kits with certified ballistic and FR layers will be locked out of the largest government tenders; pure-apparel players face margin compression.
Law Enforcement Military Clothing Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.310 B
2023
2.450 B
2024
2.590 B
2025
2.730 B
2026
2.880 B
2027
3.030 B
2028
3.190 B
2029
Law Enforcement Military Clothing Market Size (In Billion)
Year
Market Size
2023
2.310 B
2024
2.450 B
2025
2.590 B
2026
2.730 B
2027
2.880 B
2028
3.030 B
2029
3.190 B
What is the Law Enforcement Military Clothing Market?
The Law Enforcement Military Clothing Market covers purpose-built garments — combat uniforms, flame-resistant duty wear, tactical outerwear, body-armor carriers, headgear, and footwear — procured by military, police, paramilitary, and private security end users. It is defined by mission-specific performance standards (ballistic, FR, chemical-biological) rather than fashion cycles, and is dominated by government direct-contract procurement.
Scope: what this report covers and excludes
This analysis covers finished apparel and protective clothing sold to military, law enforcement, paramilitary, and private security buyers across all major regions, segmented by material, function, end-use, protection level, and distribution channel. This analysis does not cover standalone body-armor plates, helmets as separate PPE categories, footwear as a discrete industrial market, or raw textile fiber commodity trading.
How big is the market for Law Enforcement Military Clothing Market?
Estimates diverge materially on absolute size — driven by whether body-armor carriers, footwear, and private-security sales are counted — but converge on a 5–8% CAGR band through the early 2030s.
Broad definition incl. footwear, body armor, security personnel
A competing analysis
Our analysis suggests the USD 2.59B (2025) figure is the most defensible for a pure apparel-and-protective-clothing scope, because it excludes standalone hard-armor and footwear markets that inflate the USD 17.66B estimate. The 7.69% CAGR outlier likely reflects a narrower base with higher aramid-content mix skew. Buyers should anchor budgeting to the 5.4–5.9% band and treat the wider number as a total-addressable umbrella.
How is the market segmented?
Segments are most usefully read along four non-geographic axes: material chemistry, protective function, end-user type, and procurement channel — each carrying distinct margin and certification profiles.
Military/Defense, Law Enforcement/Police, Paramilitary & Border Security, Private Security
By Protection Level
Ballistic, Flame & Fire, Chemical & Biological, Standard Duty Wear
By Distribution
Government Direct Contracts, Institutional Suppliers, Retail/Specialty
Which region leads in Law Enforcement Military Clothing Market?
Asia-Pacific leads on volume share (~31%), North America leads on contract value and technology intensity (~35%), and Europe holds the regulatory benchmark position — but leadership flips depending on whether you measure revenue, units, or aramid content per garment.
Law Enforcement Military Clothing Market Regional Market Share
Loading chart...
Law Enforcement Military Clothing Market Regional Market Share
Region
Market Share (%)
North America
0.35%
Europe
0.22%
Asia-Pacific
0.31%
South America
0.06%
Middle East & Africa
0.06%
Parent Region
Key Country Markets
North America
USA, Canada, Mexico
Europe
Germany, UK, France, Italy, Poland
Asia-Pacific
China, India, Japan, South Korea, Australia
Latin America
Brazil, Argentina, Colombia
Middle East & Africa
Saudi Arabia, UAE, South Africa, Israel
Region
2025 Share
North America
35%
Asia-Pacific
31%
Europe
22%
Latin America
6%
Middle East & Africa
6%
This divergence implies a two-speed market: Asia-Pacific volume growth (9%+ CAGR in several estimates) is driven by paramilitary expansion and domestic textile capacity in China and India, while North American and European growth is value-led through smart-fabric and FR upgrades. Vendors with Asia-Pacific manufacturing but Western certifications hold the strongest cross-regional position.
What is driving growth — and what is holding it back?
Force modernization programs and multi-domain operational doctrine are the dominant demand engines, while certification bottlenecks and raw-material concentration are the binding constraints on supply response.
Our analysis suggests the balance of risk sits on the supply side, not demand. Procurement budgets are structurally rising; the constraint is certified aramid and FR fabric capacity plus testing-lab throughput. Manufacturers that pre-invest in certification pipelines will capture disproportionate share when tender windows open.
Who are the leading vendors?
The competitive field is concentrated at the top, where vertically integrated players hold long-term defense-ministry alliances, and fragmented at the tactical-retail tier.
Company
Primary Strength
Moat Type
Point Blank Enterprises
Body armor + uniform systems
Government contracts, vertical integration
Safariland
Duty gear and tactical apparel
Brand, law-enforcement channel depth
Crye Precision
Combat uniforms, modular systems
Design IP, special-forces specification
Propper International
Large-volume military apparel
Scale, Berry Amendment compliance
Milliken & Company
FR and performance textiles
Material science IP
W.L. Gore & Associates
Protective membranes/fabrics
Patented material technology
5.11 Tactical
Law-enforcement tactical wear
Brand, retail + agency channels
Differentiation is shifting from garment construction to system integration — vendors that supply uniform, carrier, and plate as a certified kit are winning larger tenders. Sovereign-sourcing rules like the Berry Amendment simultaneously protect domestic incumbents and raise barriers for low-cost Asian entrants, reinforcing concentration in North America and Europe.
What do buyers and operators need to know?
Selection criteria are dominated by certification, not price. Buyers should prioritise garments with independently verified FR (NFPA 1975/2112) and ballistic (NIJ) compliance, documented MOLLE compatibility, and proven wash-durability of protective finishes.
Procurement risk concentrates in three areas: supply continuity (aramid fabric is concentrated among few global producers), counterfeit substitution in tactical retail channels, and specification drift where lower-cost bids fail field durability tests. Switching costs are high once a uniform system is adopted — size grading, camouflage pattern, and carrier integration all create multi-year lock-in.
Operators should also plan for the female-fit transition: agencies that adopt ergonomically graded female uniforms report better ballistic coverage and retention. Finally, regulatory compliance (Berry Amendment in the US, equivalent EU/NATO local-content rules) must be confirmed at tender stage; non-compliant bids are disqualified regardless of technical merit.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours a structural growth thesis rather than a cyclical one. The USD 25.17 billion cumulative opportunity through 2032 is more than double the prior six-year window, and the drivers — geopolitical tension, force modernization, smart-textile adoption — are multi-year policy commitments, not discretionary spend. The strongest counter-argument is the persistent gap between headline defense budgets and actual apparel procurement execution, where lengthy certification and budget allocation delays can defer revenue by 12–24 months.
Our analysis suggests the highest-value strategic position is the certified system integrator: vendors that bundle modular uniform, carrier, and FR layering with Western-recognised certification capture the largest government tenders and defend margin against commodity apparel imports. Pure-garment manufacturers face margin compression as aramid input costs and counterfeit pressure squeeze the middle of the market.
Actionable Strategy:
Investors should weight exposure toward aramid/FR fabric capacity and system-integration platforms, not generic uniform cut-and-sew.
Operators should lock multi-year supply agreements now, before certification-lab bottlenecks tighten further in 2026–2027.
Vendors should prioritise female-fit ergonomic lines and smart-textile pilots to access premium-margin next-generation uniform programs.
What would change our conclusion: a sustained decline in global defense budget growth, or a breakthrough in low-cost domestic aramid production that collapses FR fabric pricing, would compress the value pool and shift advantage back to scale-volume players.
While this overview establishes the strategic frame, precise sub-segment forecasting by protection level, camouflage pattern, and country-level tender pipelines requires the full report's granular modelling.
Law Enforcement Military Clothing Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Law Enforcement Military Clothing Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.4% from 2020-2034
Segmentation
By Material
Aramid
Cotton Blends
Nylon
Polyester
Modacrylic
FR Rayon
Viscose
Wool
Kermel
By Function
Flame-Resistant
Ballistic/Protective
Moisture-Wicking
Antimicrobial
Water-Resistant
Camouflage
By Product Type
Combat Uniforms
Tactical Vests & Carriers
Outerwear
Headgear
Footwear
Camouflage Clothing
By End-Use
Military/Defense
Law Enforcement/Police
Paramilitary & Border Security
Private Security
By Protection Level
Ballistic
Flame & Fire
Chemical & Biological
Standard Duty Wear
By Distribution Channel
Government Direct Contracts
Institutional Suppliers
Retail/Specialty
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Poland
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Israel
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Material
5.1.1. Aramid
5.1.2. Cotton Blends
5.1.3. Nylon
5.1.4. Polyester
5.1.5. Modacrylic
5.1.6. FR Rayon
5.1.7. Viscose
5.1.8. Wool
5.1.9. Kermel
5.2. Market Analysis, Insights and Forecast - by Function
5.2.1. Flame-Resistant
5.2.2. Ballistic/Protective
5.2.3. Moisture-Wicking
5.2.4. Antimicrobial
5.2.5. Water-Resistant
5.2.6. Camouflage
5.3. Market Analysis, Insights and Forecast - by Product Type
5.3.1. Combat Uniforms
5.3.2. Tactical Vests & Carriers
5.3.3. Outerwear
5.3.4. Headgear
5.3.5. Footwear
5.3.6. Camouflage Clothing
5.4. Market Analysis, Insights and Forecast - by End-Use
5.4.1. Military/Defense
5.4.2. Law Enforcement/Police
5.4.3. Paramilitary & Border Security
5.4.4. Private Security
5.5. Market Analysis, Insights and Forecast - by Protection Level
5.5.1. Ballistic
5.5.2. Flame & Fire
5.5.3. Chemical & Biological
5.5.4. Standard Duty Wear
5.6. Market Analysis, Insights and Forecast - by Distribution Channel
5.6.1. Government Direct Contracts
5.6.2. Institutional Suppliers
5.6.3. Retail/Specialty
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Material
6.1.1. Aramid
6.1.2. Cotton Blends
6.1.3. Nylon
6.1.4. Polyester
6.1.5. Modacrylic
6.1.6. FR Rayon
6.1.7. Viscose
6.1.8. Wool
6.1.9. Kermel
6.2. Market Analysis, Insights and Forecast - by Function
6.2.1. Flame-Resistant
6.2.2. Ballistic/Protective
6.2.3. Moisture-Wicking
6.2.4. Antimicrobial
6.2.5. Water-Resistant
6.2.6. Camouflage
6.3. Market Analysis, Insights and Forecast - by Product Type
6.3.1. Combat Uniforms
6.3.2. Tactical Vests & Carriers
6.3.3. Outerwear
6.3.4. Headgear
6.3.5. Footwear
6.3.6. Camouflage Clothing
6.4. Market Analysis, Insights and Forecast - by End-Use
6.4.1. Military/Defense
6.4.2. Law Enforcement/Police
6.4.3. Paramilitary & Border Security
6.4.4. Private Security
6.5. Market Analysis, Insights and Forecast - by Protection Level
6.5.1. Ballistic
6.5.2. Flame & Fire
6.5.3. Chemical & Biological
6.5.4. Standard Duty Wear
6.6. Market Analysis, Insights and Forecast - by Distribution Channel
6.6.1. Government Direct Contracts
6.6.2. Institutional Suppliers
6.6.3. Retail/Specialty
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Material
7.1.1. Aramid
7.1.2. Cotton Blends
7.1.3. Nylon
7.1.4. Polyester
7.1.5. Modacrylic
7.1.6. FR Rayon
7.1.7. Viscose
7.1.8. Wool
7.1.9. Kermel
7.2. Market Analysis, Insights and Forecast - by Function
7.2.1. Flame-Resistant
7.2.2. Ballistic/Protective
7.2.3. Moisture-Wicking
7.2.4. Antimicrobial
7.2.5. Water-Resistant
7.2.6. Camouflage
7.3. Market Analysis, Insights and Forecast - by Product Type
7.3.1. Combat Uniforms
7.3.2. Tactical Vests & Carriers
7.3.3. Outerwear
7.3.4. Headgear
7.3.5. Footwear
7.3.6. Camouflage Clothing
7.4. Market Analysis, Insights and Forecast - by End-Use
7.4.1. Military/Defense
7.4.2. Law Enforcement/Police
7.4.3. Paramilitary & Border Security
7.4.4. Private Security
7.5. Market Analysis, Insights and Forecast - by Protection Level
7.5.1. Ballistic
7.5.2. Flame & Fire
7.5.3. Chemical & Biological
7.5.4. Standard Duty Wear
7.6. Market Analysis, Insights and Forecast - by Distribution Channel
7.6.1. Government Direct Contracts
7.6.2. Institutional Suppliers
7.6.3. Retail/Specialty
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Material
8.1.1. Aramid
8.1.2. Cotton Blends
8.1.3. Nylon
8.1.4. Polyester
8.1.5. Modacrylic
8.1.6. FR Rayon
8.1.7. Viscose
8.1.8. Wool
8.1.9. Kermel
8.2. Market Analysis, Insights and Forecast - by Function
8.2.1. Flame-Resistant
8.2.2. Ballistic/Protective
8.2.3. Moisture-Wicking
8.2.4. Antimicrobial
8.2.5. Water-Resistant
8.2.6. Camouflage
8.3. Market Analysis, Insights and Forecast - by Product Type
8.3.1. Combat Uniforms
8.3.2. Tactical Vests & Carriers
8.3.3. Outerwear
8.3.4. Headgear
8.3.5. Footwear
8.3.6. Camouflage Clothing
8.4. Market Analysis, Insights and Forecast - by End-Use
8.4.1. Military/Defense
8.4.2. Law Enforcement/Police
8.4.3. Paramilitary & Border Security
8.4.4. Private Security
8.5. Market Analysis, Insights and Forecast - by Protection Level
8.5.1. Ballistic
8.5.2. Flame & Fire
8.5.3. Chemical & Biological
8.5.4. Standard Duty Wear
8.6. Market Analysis, Insights and Forecast - by Distribution Channel
8.6.1. Government Direct Contracts
8.6.2. Institutional Suppliers
8.6.3. Retail/Specialty
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Material
9.1.1. Aramid
9.1.2. Cotton Blends
9.1.3. Nylon
9.1.4. Polyester
9.1.5. Modacrylic
9.1.6. FR Rayon
9.1.7. Viscose
9.1.8. Wool
9.1.9. Kermel
9.2. Market Analysis, Insights and Forecast - by Function
9.2.1. Flame-Resistant
9.2.2. Ballistic/Protective
9.2.3. Moisture-Wicking
9.2.4. Antimicrobial
9.2.5. Water-Resistant
9.2.6. Camouflage
9.3. Market Analysis, Insights and Forecast - by Product Type
9.3.1. Combat Uniforms
9.3.2. Tactical Vests & Carriers
9.3.3. Outerwear
9.3.4. Headgear
9.3.5. Footwear
9.3.6. Camouflage Clothing
9.4. Market Analysis, Insights and Forecast - by End-Use
9.4.1. Military/Defense
9.4.2. Law Enforcement/Police
9.4.3. Paramilitary & Border Security
9.4.4. Private Security
9.5. Market Analysis, Insights and Forecast - by Protection Level
9.5.1. Ballistic
9.5.2. Flame & Fire
9.5.3. Chemical & Biological
9.5.4. Standard Duty Wear
9.6. Market Analysis, Insights and Forecast - by Distribution Channel
9.6.1. Government Direct Contracts
9.6.2. Institutional Suppliers
9.6.3. Retail/Specialty
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Material
10.1.1. Aramid
10.1.2. Cotton Blends
10.1.3. Nylon
10.1.4. Polyester
10.1.5. Modacrylic
10.1.6. FR Rayon
10.1.7. Viscose
10.1.8. Wool
10.1.9. Kermel
10.2. Market Analysis, Insights and Forecast - by Function
10.2.1. Flame-Resistant
10.2.2. Ballistic/Protective
10.2.3. Moisture-Wicking
10.2.4. Antimicrobial
10.2.5. Water-Resistant
10.2.6. Camouflage
10.3. Market Analysis, Insights and Forecast - by Product Type
10.3.1. Combat Uniforms
10.3.2. Tactical Vests & Carriers
10.3.3. Outerwear
10.3.4. Headgear
10.3.5. Footwear
10.3.6. Camouflage Clothing
10.4. Market Analysis, Insights and Forecast - by End-Use
10.4.1. Military/Defense
10.4.2. Law Enforcement/Police
10.4.3. Paramilitary & Border Security
10.4.4. Private Security
10.5. Market Analysis, Insights and Forecast - by Protection Level
10.5.1. Ballistic
10.5.2. Flame & Fire
10.5.3. Chemical & Biological
10.5.4. Standard Duty Wear
10.6. Market Analysis, Insights and Forecast - by Distribution Channel
10.6.1. Government Direct Contracts
10.6.2. Institutional Suppliers
10.6.3. Retail/Specialty
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Point Blank Enterprises
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Safariland
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Crye Precision
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Propper International
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Milliken & Company
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. W.L. Gore & Associates
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. 5.11 Tactical
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Blackhawk
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Tactical Tailor
11.1.9.1. Company Overview
12. Research Methodology
List of Figures
Figure 1: Law Enforcement Military Clothing Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Law Enforcement Military Clothing Market Revenue (Billion), by Material 2026 & 2034
Figure 3: North America Law Enforcement Military Clothing Market Revenue Share (%), by Material 2026 & 2034
Figure 4: North America Law Enforcement Military Clothing Market Revenue (Billion), by Function 2026 & 2034
Figure 5: North America Law Enforcement Military Clothing Market Revenue Share (%), by Function 2026 & 2034
Figure 6: North America Law Enforcement Military Clothing Market Revenue (Billion), by Product Type 2026 & 2034
Figure 7: North America Law Enforcement Military Clothing Market Revenue Share (%), by Product Type 2026 & 2034
Figure 8: North America Law Enforcement Military Clothing Market Revenue (Billion), by End-Use 2026 & 2034
Figure 9: North America Law Enforcement Military Clothing Market Revenue Share (%), by End-Use 2026 & 2034
Figure 10: North America Law Enforcement Military Clothing Market Revenue (Billion), by Protection Level 2026 & 2034
Figure 11: North America Law Enforcement Military Clothing Market Revenue Share (%), by Protection Level 2026 & 2034
Figure 12: North America Law Enforcement Military Clothing Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 13: North America Law Enforcement Military Clothing Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 14: North America Law Enforcement Military Clothing Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Law Enforcement Military Clothing Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Law Enforcement Military Clothing Market Revenue Billion Forecast, by Material 2020 & 2034
Table 2: Law Enforcement Military Clothing Market Revenue Billion Forecast, by Function 2020 & 2034
Table 3: Law Enforcement Military Clothing Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 4: Law Enforcement Military Clothing Market Revenue Billion Forecast, by End-Use 2020 & 2034
Table 5: Law Enforcement Military Clothing Market Revenue Billion Forecast, by Protection Level 2020 & 2034
Table 6: Law Enforcement Military Clothing Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 7: Law Enforcement Military Clothing Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Law Enforcement Military Clothing Market Revenue Billion Forecast, by Material 2020 & 2034
Table 9: North America Law Enforcement Military Clothing Market Revenue Billion Forecast, by Function 2020 & 2034
Table 10: North America Law Enforcement Military Clothing Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 11: North America Law Enforcement Military Clothing Market Revenue Billion Forecast, by End-Use 2020 & 2034
Table 12: North America Law Enforcement Military Clothing Market Revenue Billion Forecast, by Protection Level 2020 & 2034
Table 13: North America Law Enforcement Military Clothing Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 14: North America Law Enforcement Military Clothing Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Law Enforcement Military Clothing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the Law Enforcement Military Clothing Market in 2025?
The market is valued at approximately USD 2.59 billion in 2025, up 5.8% year-on-year from USD 2.45 billion in 2024. Estimates vary by scope, with broader definitions including footwear and body armor reaching higher figures.
2. What is the growth rate of the Law Enforcement Military Clothing Market?
Most published estimates converge on a 5.4–5.9% CAGR through the early 2030s. Narrower-scope analyses report up to 7.7%, driven by higher aramid-content mix and force modernization spending.
3. Which region dominates the Law Enforcement Military Clothing Market?
Asia-Pacific leads on volume share at roughly 31%, while North America leads on contract value at about 35%. Europe holds the regulatory benchmark position through green procurement and NATO standards.
4. What material segment leads the Law Enforcement Military Clothing Market?
Cotton blends (particularly NYCO) hold the largest share for standard-issue uniforms due to breathability and cost. Aramid fibers are the fastest-growing material class, projected near a 10% CAGR on FR and ballistic demand.
5. Who are the leading companies in the Law Enforcement Military Clothing Market?
Key players include Point Blank Enterprises, Safariland, Crye Precision, Propper International, Milliken & Company, W.L. Gore & Associates, and 5.11 Tactical, with concentration reinforced by sovereign-sourcing rules and long-term defense alliances.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program is built on a 70/30 primary-to-secondary split. We conducted in-depth interviews across the value chain — aramid and FR fabric producers, specialised garment manufacturers, ballistic and protective-apparel integrators, and government-contract distributors — to capture procurement behaviour at each tier. Interviewees included VP-level Sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads at defence and law-enforcement suppliers, ensuring demand signals are validated by decision-makers who set tender specifications.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing VPs
35%
R&D & Technical Directors
30%
Commercial Operations Leads
20%
Quality & Compliance Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
FR & Aramid Fabric Producers
35%
Specialised Garment Manufacturers
40%
Ballistic & Protective Integrators
15%
Government Contract Distributors
10%
Secondary Benchmarking & Public Trade Validation
We triangulate primary findings against official multilateral databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases tracking smart-textile and FR-fabric innovation, and recognised technical standards bodies including NIJ, NFPA, and ISO textile committees. These sources anchor market sizing to observable trade flows and certified-product registrations rather than survey extrapolation alone.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down and Bottom-Up models. The Top-Down approach allocates macroeconomic defence and internal-security budgets to apparel and protective-clothing line items by region. The Bottom-Up approach models manufacturer capacity, unit pricing, and end-use consumption by agency type. Divergence between the two is reconciled through segment-level elasticity analysis.


 Law Enforcement Military Clothing Market