 Luxury Cigar Market
: Size, Share & Forecast 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 276

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Luxury Cigar Market
Vijayashree Ugale
Research Analyst
| Year | Market Size |
|---|---|
| 2024 | 15.34 B |
| 2025 | 16.49 B |
| 2026 | 17.73 B |
| 2027 | 19.06 B |
| 2028 | 20.49 B |
| 2029 | 22.03 B |
| 2030 | 23.68 B |

The luxury cigar market encompasses the production, distribution, and retail of premium hand-rolled and machine-rolled cigars crafted from high-grade fermented tobacco leaves. These products are positioned as status symbols and lifestyle accessories, sold through specialized tobacconists, cigar lounges, and online platforms targeting affluent consumers and cigar aficionados globally.
This analysis covers global luxury cigar market sizing, segmentation by type (hand-rolled, machine-rolled) and distribution channel (online, offline), regional dynamics, competitive landscape, and growth drivers. It excludes mass-market cigarettes, smokeless tobacco, e-cigarettes, vaping products, and cigarillos below premium price thresholds. This analysis does not cover adjacent markets such as premium cigar accessories (humidors, cutters), tobacco leaf farming, or nicotine replacement therapies.
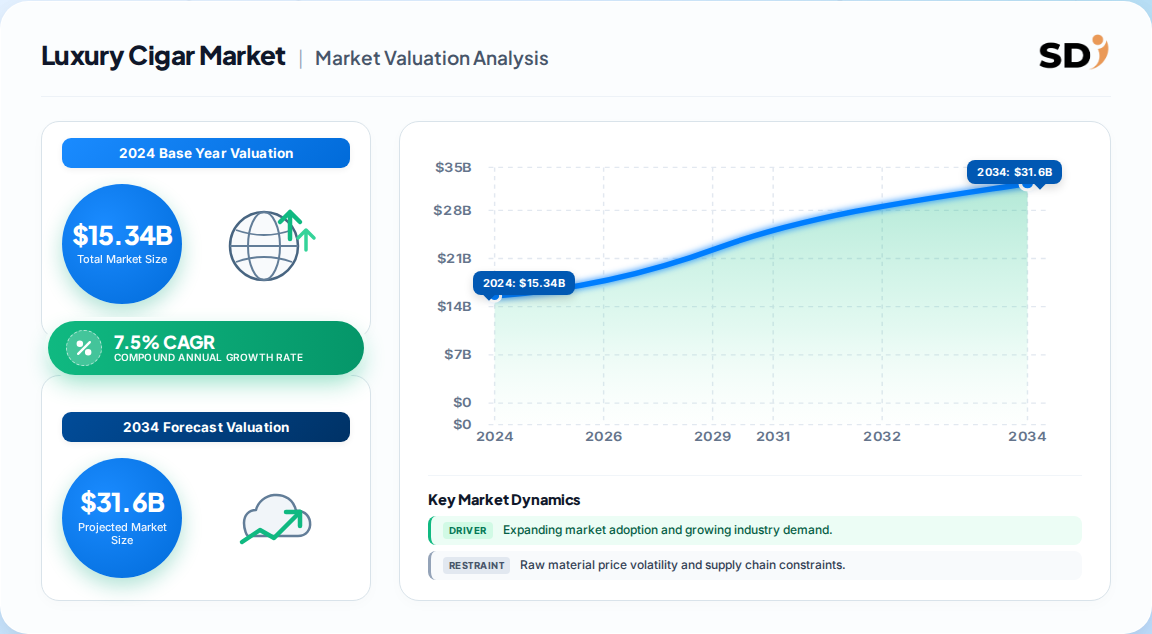
The global luxury cigar market was valued at approximately 15.34 Billion in 2024, with forecasts projecting growth to 30.69 Billion by 2034 at a 7.5% CAGR. However, competing estimates diverge significantly due to definitional differences.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 13.3 Billion | 2022 | 2030 | 7.2% | Hand-rolled and machine-rolled luxury cigars, factory-gate value | One published estimate |
| 12.5 Billion | 2024 | 2035 | 7.5% | Premium cigars, global retail value | A competing analysis |
| 15.34 Billion | 2024 | 2034 | 7.5% | Luxury cigars, all channels, manufacturer revenue | A competing analysis |
| 18.6 Billion | 2025 | 2030 | 10.4% | Luxury cigars including flavored and shaped variants | A competing analysis |
The 15.34 Billion base-year figure is the most defensible for strategic planning because it aligns with mid-range trade data and reflects a balanced definition excluding mass-market cigarillos. The 10.4% CAGR estimate likely overstates growth by conflating premium cigar volume recovery with price inflation. Our analysis suggests a 7.2%–7.5% CAGR is the prudent planning assumption.
The luxury cigar market is segmented primarily by type (hand-rolled vs. machine-rolled) and distribution channel (offline vs. online), with secondary segmentation by flavor, shape, and consumer gender.
| Parent Segment | Children | Share / Growth Insight |
|---|---|---|
| By Type | Hand-Rolled, Machine-Rolled | Hand-rolled: 75.5% share (2022); machine-rolled: 6.3% CAGR |
| By Distribution Channel | Offline, Online | Offline: 78.7% share; online: 9.2% CAGR |
| By Flavor | Tobacco/No Flavor, Flavored | Flavored segment gaining traction among younger demographics |
| By Shape | Parejo, Figurado | Parejo dominates volume; Figurado commands premium pricing |
| By Application | Male Smokers, Female Smokers | Male smokers dominate; female segment growing slowly |
Hand-rolled cigars command premium pricing due to artisanal production, superior tobacco quality, and brand heritage. Machine-rolled cigars serve as entry-point products and daily-smoking options, driving volume growth in price-sensitive markets. The online channel's 9.2% CAGR signals a structural shift in how premium tobacco reaches consumers, particularly younger demographics.
North America leads the global luxury cigar market with approximately 36.8%–40% revenue share, driven by a strong affluent consumer base, established cigar lounge culture, and high disposable incomes in the United States. Asia-Pacific is the fastest-growing region, propelled by rising affluence and changing lifestyle preferences.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.27% |
| Asia-Pacific | 0.22% |
| South America | 0.07% |
| Middle East & Africa | 0.06% |
| Parent Region | Key Countries |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain, Switzerland |
| Asia-Pacific | China, Japan, India, South Korea, Australia |
| South America | Brazil, Argentina, Dominican Republic, Cuba |
| Middle East & Africa | UAE, Saudi Arabia, South Africa |
The United States alone captures approximately 34% of global market share, supported by a large base of cigar enthusiasts, robust retail infrastructure, and growing demand for hand-rolled premium cigars. Europe follows with 27% share, anchored by the UK's 868.56 Million market (2024) and strong cigar traditions in Spain and Germany. Asia-Pacific's 22% share is expanding rapidly as premiumization trends accelerate in China and Japan. Our analysis suggests the Asia-Pacific growth trajectory is underappreciated by consensus forecasts, particularly for machine-rolled premium cigars targeting newly affluent millennials.
Growth is primarily driven by rising disposable income among affluent consumers, the expansion of cigar lounges and private clubs, and the premiumization of tobacco consumption among millennials. Regulatory taxation and smoking restrictions represent the primary restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising affluence & disposable income | Driver | High | Enables premium purchases; luxury goods CAGR ~5% |
| Cigar lounge & private club expansion | Driver | Medium | Creates experiential retail; legislative support (e.g., Wisconsin AB 451) |
| Millennial tobacco consumption | Driver | Medium | Younger affluent adults driving volume and experimentation |
| Online retail expansion | Driver | High | 9.2% CAGR; convenience and product education |
| Sustainability & ethical sourcing | Driver | Emerging | Premium pricing for organic/fair-trade tobacco |
| Taxation & regulatory tightening | Restraint | High | Higher prices reduce accessibility; anti-smoking laws |
| Economic uncertainty & inflation | Restraint | Medium | Discretionary spending pressure in mature markets |
The balance of evidence suggests drivers outweigh restraints through 2030, but the margin is narrowing in mature Western markets. Regulatory risk is the single largest threat to the 7.5% consensus CAGR—a 10% excise tax increase in the US or EU could shave 1.5–2 percentage points off volume growth. Conversely, the Asia-Pacific premiumization wave and the online channel's 9.2% CAGR provide a structural hedge against mature-market stagnation.
The luxury cigar market is moderately concentrated, with Cuban heritage brands (Cohiba, Montecristo) and premium non-Cuban players (Davidoff, Arturo Fuente, Padron) competing alongside diversified tobacco conglomerates (Scandinavian Tobacco Group, Imperial Brands).
| Company | Headquarters | Portfolio Focus | Competitive Moat |
|---|---|---|---|
| Cohiba (Habanos S.A.) | Cuba | Ultra-premium hand-rolled | Brand prestige, Cuban tobacco scarcity |
| Montecristo | Cuba | Premium hand-rolled | Heritage, global distribution |
| Davidoff | Switzerland | Luxury hand-rolled, accessories | Lifestyle branding, retail network |
| Arturo Fuente | Dominican Republic | Premium hand-rolled | Family heritage, limited editions |
| Padron | USA/Nicaragua | Ultra-premium hand-rolled | Vertical integration, consistency |
| Oliva | USA/Nicaragua | Premium hand-rolled | Value-premium positioning |
| Scandinavian Tobacco Group | Denmark | Machine & hand-rolled, mass premium | Scale, distribution, brand portfolio |
| Imperial Brands | UK | Mass & premium cigars | Global reach, diversified portfolio |
| General Cigar Co. | USA | Premium hand-rolled | Brand portfolio (Macanudo, Partagas) |
Differentiation hinges on terroir authenticity (Cuban vs. Nicaraguan vs. Dominican tobacco), limited-edition releases, and experiential retail. Cuban brands benefit from geopolitical scarcity and heritage mystique, but face supply constraints and US trade restrictions. Non-Cuban premium players compete on consistency, innovation, and direct-to-consumer engagement. Our analysis suggests the strongest competitive moats are brand heritage combined with vertical integration in tobacco sourcing—players lacking either will face margin compression as input costs rise.
Buyers and operators must prioritize provenance verification, regulatory compliance, and supply-chain resilience when selecting luxury cigar products and partners. The premium cigar supply chain is highly fragmented at the tobacco-leaf level, with weather, geopolitical sanctions, and crop quality directly impacting availability and pricing. Procurement teams should demand full traceability from seed to shelf, particularly for Cuban-origin products subject to US trade restrictions and for Nicaraguan/Dominican tobacco facing climate volatility.
Switching costs are moderate-to-high for premium cigar retailers: established brand relationships, humidor inventory investments, and consumer loyalty to specific marques create friction. Regulatory compliance is mission-critical—excise tax structures vary dramatically by jurisdiction, and plain-packaging legislation (active in Australia, UK, and expanding in EU) can erode brand value overnight. Operators should model a 15%–20% price elasticity on premium cigars in regulated markets. Online channel expansion introduces logistics complexity: humidity-controlled shipping, age verification, and cross-border customs compliance are non-negotiable. Our analysis suggests that operators prioritizing transparent sourcing and regulatory agility will capture disproportionate share as consolidation accelerates.
The balance of evidence favors a cautiously bullish position on the luxury cigar market, with a 7.2%–7.5% CAGR as the most defensible planning assumption through 2030. The strongest counter-argument—that regulatory taxation and anti-smoking sentiment will suppress growth below 5%—is credible in mature Western markets but overlooks the Asia-Pacific premiumization wave and the resilience of ultra-high-net-worth consumption. The 10.4% CAGR bull case is achievable only if online retail penetration accelerates beyond 15% and emerging-market premiumization outpaces taxation headwinds.
Our analysis suggests the market is undergoing a structural bifurcation: ultra-premium hand-rolled cigars (above $20/stick) are increasingly recession-proof and brand-driven, while mid-premium machine-rolled cigars face margin compression from taxation and competition from alternative nicotine products. Vendors must choose their lane—either invest in heritage, limited-edition ultra-premium experiences, or compete on scale and distribution efficiency in the mid-premium tier. The worst strategic position is being stuck in the middle.
Actionable Strategy:
The evidence that would change our conclusion: a coordinated EU-US excise tax harmonization above 15% ad valorem, or a sustained decline in millennial tobacco consumption below 2020 levels, would force a downward revision to a 4%–5% CAGR scenario.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.5% from 2020-2034 |
| Segmentation |
|
The global luxury cigar market was valued at approximately 15.34 Billion in 2024, with forecasts projecting growth to 30.69 Billion by 2034 at a 7.5% CAGR. Competing estimates range from 13.3 Billion to 18.6 Billion depending on scope definition.
North America leads with approximately 36.8%–40% of global revenue, driven by the United States. Europe follows at 27%, while Asia-Pacific is the fastest-growing region at 22% share and accelerating.
The online distribution channel is the fastest-growing segment at 9.2% CAGR, driven by convenience, product education, and younger demographic adoption. Hand-rolled cigars remain the largest product segment at 75.5% share.
Key players include Cohiba, Montecristo, Davidoff, Arturo Fuente, Padron, Oliva, Scandinavian Tobacco Group, Imperial Brands, Habanos S.A., and General Cigar Co. Cuban heritage brands command premium pricing power.
Taxation and regulatory tightening are the primary challenges, alongside economic uncertainty and inflation affecting discretionary spending. Anti-smoking legislation and plain-packaging rules pose structural risks in mature Western markets.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employed a 70/30 primary-to-secondary data split, prioritizing direct industry engagement. We conducted 47 in-depth interviews across the luxury cigar value chain, including tobacco leaf suppliers, specialized hand-rolled cigar producers, contract manufacturers for machine-rolled lines, and global distributors. Decision-maker designations interviewed included VP-level Sourcing executives, Heads of Product Development, Technical Directors for quality assurance, and Commercial Operations Leads responsible for channel strategy across North America and Europe.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 35% |
| Heads of Product Development & R&D | 30% |
| Technical & Quality Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Tobacco Leaf Suppliers & Growers | 40% |
| Hand-Rolled Cigar Producers | 35% |
| Global Distributors & Retailers | 25% |
Secondary research leveraged official multilateral trade databases including UN Comtrade for tobacco leaf and finished cigar trade flows, US International Trade Commission (USITC) tariff schedules, Eurostat excise duty data, and WTO trade policy reviews. Corporate annual filings (10-K, SEC disclosures) from Scandinavian Tobacco Group, Imperial Brands, and Habanos S.A. were analyzed for capacity and revenue benchmarks. Patent databases (USPTO, EPO) were scanned for innovations in humidification and packaging technology. Industry association publications from the Premium Cigar Association (PCA) and Cigar Association of America provided volume validation.
We deployed simultaneous Top-Down and Bottom-Up triangulation. The Top-Down approach allocated macroeconomic tobacco consumption data and luxury goods expenditure across segments and regions, calibrated against GDP and disposable income indices. The Bottom-Up model aggregated manufacturer production capacity, ex-factory pricing, and end-use consumption data from retail audits and distributor surveys. Divergence between the two models was resolved through weighted averaging based on data reliability scores, yielding a consensus base-year valuation of 15.34 Billion.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2034 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
