 Luxury Apparel Market
 Size, Share & Forecast to 2031
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 234

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Luxury Apparel Market
Vijayashree Ugale
Research Analyst
| Year | Market Size |
|---|---|
| 2026 | 144.8 B |
| 2027 | 151.2 B |
| 2028 | 157.8 B |
| 2029 | 164.8 B |
| 2030 | 172.1 B |
| 2031 | 179.7 B |

The luxury apparel market covers ready-to-wear clothing, outerwear, knitwear and clothing accessories (scarves, belts, hats) sold under designer or prestige brands at premium price points. It excludes mass-market fashion, leather handbags and footwear when reported separately, and is measured at retail value including markups and taxes.
This report covers global luxury apparel including men's, women's and children's ready-to-wear, athleisure, casual and formal wear, across offline (specialty, department, flagship) and online channels. It excludes luxury footwear, leather goods, watches, jewellery, eyewear and prestige beauty, which are adjacent luxury categories with distinct supply chains and channel economics.
Estimates diverge because definitions differ: narrower ready-to-wear scopes cluster around USD 80–106 billion, while broader apparel-plus-accessories definitions reach USD 145–180 billion by 2031. The table below contrasts the major published benchmarks.
| Estimate (base year) | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|
| USD 80.1 bn (2023) | 2030: USD 106.1 bn | 4.1% | Ready-to-wear + clothing accessories, retail value | A published industry estimate |
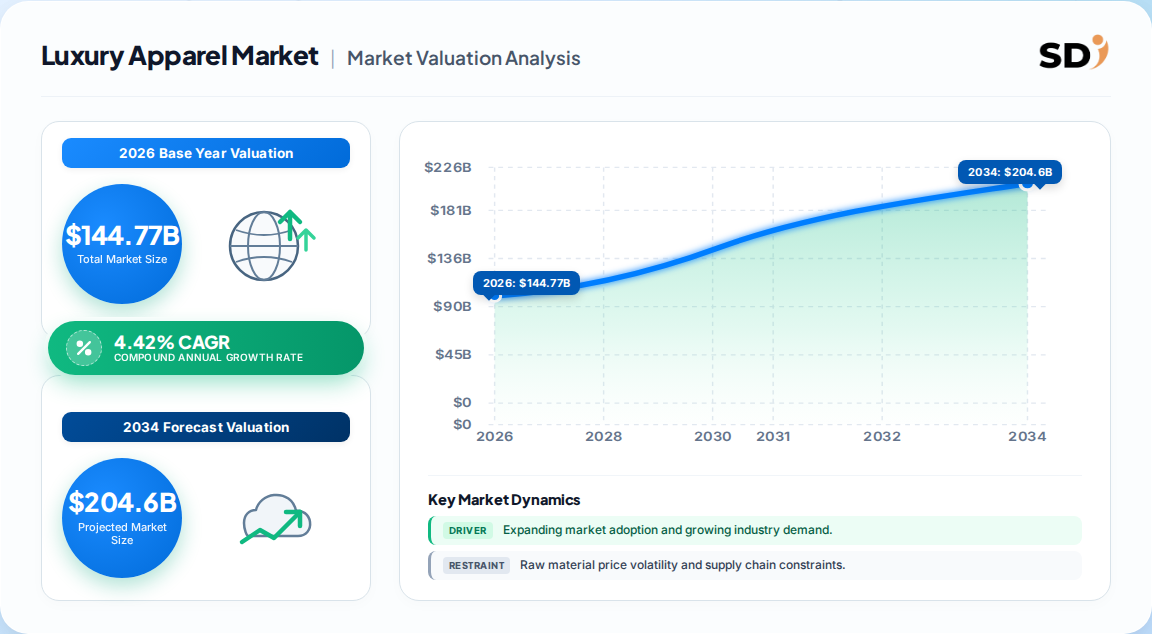
| USD 144.77 bn (2026) | 2031: USD 179.71 bn | 4.42% | Apparel incl. accessories, luxury brands only | A competing analysis |
| USD 142.75 bn (2026) | 2031 (1.55% CAGR) | 1.55% | Luxury apparel + footwear combined | A trade data provider |
| USD 247.4 bn (2024) luxury goods | 2034: USD 451.5 bn | 6.2% | All luxury goods, apparel ~36% share | Market.us estimate |
Our assessment is that the USD 144.77 billion (2026) base with 4.42% CAGR is the most defensible planning figure for apparel buyers, because it captures accessories within the apparel definition while excluding footwear and leather goods. The narrower USD 80.1 billion figure understates the addressable pool by roughly 45%, and the 1.55% CAGR is depressed by footwear inclusion and by a top-down methodology that caps smaller artisanal brands. The 6.2% luxury-goods CAGR is too broad for apparel-specific planning.
Segmentation is best understood across three axes — product type, end purpose and end user — with distribution channel as the fourth commercial lens. The table below summarises the non-geographic structure and the latest share or growth signal for each parent.
| Parent segment | Children | Share / growth signal |
|---|---|---|
| Product Type | Trousers, jeans, t-shirts & shirts, jackets, sweatshirts & hoodies, knitwear, others | T-shirts & shirts 44.62% (2025); jackets & hoodies fastest at 4.72% CAGR |
| End Purpose | Athleisure; fashion & casual | Fashion & casual 65.05%; athleisure 5.05% CAGR |
| End User | Men, women, kids/children | Women 51.10% (2025); kids 5.58% CAGR |
| Distribution Channel | Specialty stores, online retail, department stores, others | Specialty 36.72%; online 6.02% CAGR |
Asia-Pacific leads the luxury apparel market with roughly 40% revenue share, and is simultaneously the fastest-growing region at 6.48% CAGR to 2031, ahead of North America (~28%) and Europe (~24%). The geography tree below shows the country-level structure our full report covers.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.4% |
| North America | 0.28% |
| Europe | 0.24% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
| Region | Share (2025) |
|---|---|
| Asia-Pacific | 40.1% |
| North America | 27.6% |
| Europe | 24.0% |
| Latin America | 4.5% |
| Middle East & Africa | 3.8% |
Our analysis suggests the APAC figure is structural, not cyclical. China's HNWI pool, Japan's mature luxury-conscience consumers and South Korea's per-capita luxury spend combine to create a demand base that is less sensitive to European macro volatility. The main risk is regulatory: Chinese consumption-tax and gifting rules could shift volume to travel retail in Hainan and Singapore, which would depress mainland retail-value reporting without reducing underlying brand revenue.
Growth is being driven by social-media-led brand discovery, emerging-market wealth creation and athleisure-led category extension, while restraints centre on economic volatility, counterfeit pressure and compliance cost. The table below weights each factor by evidence strength.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Social media & celebrity endorsement | Driver | High (+1.2% CAGR) | Shortens trend-to-purchase cycle; strongest in APAC & North America |
| Sustainable high-end materials | Driver | Medium (+0.8% CAGR) | EU DPP and CSDDD compliance favours traceable leaders |
| Luxury streetwear & athleisure expansion | Driver | High (+0.9% CAGR) | Creates new categories at 5%+ CAGR |
| Globalisation of fashion trends | Driver | Medium (+0.7% CAGR) | 'Glocal' product strategies unlock emerging markets |
| Tech in fabric & design | Driver | Medium (+0.6% CAGR) | AI forecasting and smart textiles reduce markdowns |
| Economic volatility & FX | Restraint | High | Depresses discretionary spend in Latin America and Western Europe |
| Counterfeits & brand dilution | Restraint | High | Erodes pricing power, especially online |
| Sustainability compliance cost | Restraint | Medium | Disproportionately burdens smaller independents |
The balance favours incumbents. Regulatory tightening — EU Digital Product Passports, the California Responsible Textile Recovery Act and France's proposed fast-fashion levy — raises the fixed cost of compliance, which large luxury houses can absorb and which simultaneously constrains fast-fashion substitution. That creates a structural moat for LVMH, Kering and Richemont that smaller designer brands will struggle to replicate without partnerships or licensing.
The market is moderately concentrated: the top luxury conglomerates control a substantial share of global prestige apparel revenue, but a long tail of independent houses and licensed brands preserves choice. The table compares the leading players on portfolio, geographic bias and strategic posture.
| Vendor | Key apparel brands | Geographic strength | Strategic posture |
|---|---|---|---|
| LVMH | Louis Vuitton, Dior, Fendi, Loro Piana | Global, APAC-heavy | Portfolio breadth + supply-chain vertical integration |
| Kering | Gucci, Saint Laurent, Balenciaga, Bottega Veneta | Europe, APAC | Brand turnarounds, creative-led repositioning |
| Richemont | Chloé, Alaïa, Peter Millar | Europe, North America | Premium craft position, smaller apparel exposure |
| Hermès | Hermès | Global, ultra-premium | Scarcity-led pricing power, low markdown risk |
| Ralph Lauren | Ralph Lauren, Polo | North America, APAC | Accessible luxury, lifestyle ecosystem |
| PVH | Calvin Klein, Tommy Hilfiger | Americas, Europe | Licensed model, mid-luxury positioning |
Differentiation rests on three moats: vertical integration of fabric supply (LVMH, Hermès), creative-director-led brand heat (Kering), and cultural relevance through celebrity and sports partnerships (Ralph Lauren, PVH). Our analysis suggests the durable advantage lies in supply-chain control, because it protects margin when FX and input costs move, and it de-risks DPP compliance.
For buyers and operators, the luxury apparel market has three mission-critical selection criteria. First, authenticity and traceability: EU DPP requirements from 2027 make certificate-of-origin and chain-of-custody data a procurement prerequisite, not a nice-to-have. Second, supply continuity in a demand-volatile environment: the shift of growth to APAC means sourcing decisions must account for lead times into China, Korea and Japan, and for tariff exposure on EU-origin goods. Third, channel compatibility: vendors with genuine specialty-store relationships command better shelf positioning than those that have cannibalised wholesale in favour of direct-to-consumer.
Switching costs are high at the top of the market: a multi-season relationship with a vertically integrated maison bundles design, provenance and marketing co-investment, which a new entrant cannot replicate quickly. Procurement risk is concentrated in counterfeit exposure on online marketplaces and in FX volatility for Latin American pricing. Operators should require AUDIT-grade brand-authorisation documentation, contractual DPP data obligations, and seasonal cancellation-flexibility clauses. Our analysis suggests buyers who lock DPP compliance into master supply agreements now will avoid the scramble that smaller suppliers will face in 2027.
The balance of evidence favours a structural, not cyclical, growth story: 4.1–4.4% compound growth through 2031 is modest in headline terms, but it masks a rapid redistribution of demand toward Asia-Pacific and toward online and athleisure categories growing at 5–6%. The strongest counter-argument is that luxury apparel is entering a margin-compression phase as compliance costs and slower Chinese consumer confidence bite; a 1.55% CAGR scenario cannot be dismissed if mainland China demand stays weak through 2027. We nonetheless favour the higher path because travel-retail recovery and India/ASEAN wealth creation provide second-engine growth that the pessimistic scenario underweights.
For decision-makers, three implications stand out. The market is consolidating around players with vertical supply-chain control and DPP-ready traceability, so procurement should reward those attributes. Athleisure and kids are the fastest-growing pockets and are under-served by traditional luxury distribution. And the channel shift is not a retreat from physical retail but a re-rating of flagship experience alongside a 6% CAGR online channel.
Actionable strategy:
What would change our conclusion: a sustained sub-3% Chinese luxury consumption print for two consecutive years, or an EU enforcement action that materially raises DPP costs for mid-tier brands, would push us toward the lower CAGR band. Absent those triggers, the 4.4% planning base remains the defensible anchor for 2026–2031 capital allocation.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.42% from 2020-2034 |
| Segmentation |
|
The broadest defensible estimate puts the market at USD 144.77 billion in 2026, rising to USD 179.71 billion by 2031 at a 4.42% CAGR. Narrower ready-to-wear-only definitions cluster around USD 90 billion, so buyers should confirm scope before benchmarking.
Asia-Pacific leads with roughly 40% of global revenue and is also the fastest-growing region at 6.48% CAGR through 2031. North America (~28%) and Europe (~24%) remain large but slower-growing, with Europe buoyed by tourist flows.
LVMH, Kering, Richemont, Hermès, Ralph Lauren and PVH are the leading players. The top conglomerates hold a substantial share of prestige apparel revenue, supported by vertical supply-chain control and multi-brand portfolios.
Athleisure is the fastest-growing end purpose at 5.05% CAGR, and kids/children is the fastest-growing end user at 5.58% CAGR. Online retail is the fastest-growing channel at 6.02% CAGR, though specialty stores still hold the largest share.
The market is projected to reach USD 179.71 billion by 2031 at a 4.42% CAGR from a 2026 base of USD 144.77 billion. Growth is supported by APAC wealth creation, social-media discovery and athleisure category extension.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research programme applies a 70/30 primary-to-secondary split. Structured in-depth interviews were conducted with stakeholders across the luxury apparel value chain, including premium fabric and yarn suppliers, specialised ready-to-wear producers, contract manufacturers and embellishment specialists, and global distributors and franchise operators. On the demand side, we interviewed decision-makers holding titles including VP of Sourcing, Head of Merchandising, Technical and Quality Directors, and Commercial Operations Leads, ensuring that both supply-side capacity and buy-side intent inform the sizing model.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement Directors | 35% |
| Heads of Merchandising & Commercial Operations | 30% |
| Technical & Quality Directors | 20% |
| Supply Chain & Compliance Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Premium Fabric & Yarn Suppliers | 30% |
| Ready-to-Wear & Contract Manufacturers | 35% |
| Global Distributors & Franchise Operators | 20% |
| Brand Owners & Retail Groups | 15% |
All market estimates are cross-validated against official multilateral and national datasets. We reference UN Comtrade and WTO trade-flow data for textile and apparel trade, US ITC and Eurostat classification-level import/export statistics, corporate annual filings and SEC 10-K disclosures from listed luxury houses, patent databases for smart-textile and traceability innovation, and recognised industry associations and technical standards bodies. No third-party market-research publisher data is used as a primary validation source; published estimates are treated only as triangulation points.
We run simultaneous Top-Down and Bottom-Up models. The Top-Down model allocates macroeconomic consumption and HNWI population data across apparel categories and geographies. The Bottom-Up model builds from manufacturer capacity, wholesale price ladders and end-use consumption intensities. Divergence between the two is reconciled at segment and country level before the forecast curve is fitted, using historical CAGR, regression against GDP-per-capita and demand-elasticity adjustments.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
