Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Luxury Wines Spirits Market by Product Type (Wines, Champagnes, Spirits(Whisky, Cognac, Brandy, Vodka, Gin, Rum, Tequila, Others)), by Price Range (Premium, Super-Premium, Ultra-Premium), by Distribution Channel (Retail, Wholesale, E-commerce, Others), by End User (Individual Consumers, Hospitality Industry, Event Organizers, Corporate Gifting), by Alcohol Content (Low/No Alcohol, Standard, High ABV), by Europe (France, Italy, Spain, Germany, UK, Switzerland), by Asia Pacific (China, India, Japan, South Korea, Australia, Singapore), by North America (USA, Canada, Mexico), by Latin America (Brazil, Argentina, Chile), by Middle East & Africa (UAE, South Africa, Saudi Arabia) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 217
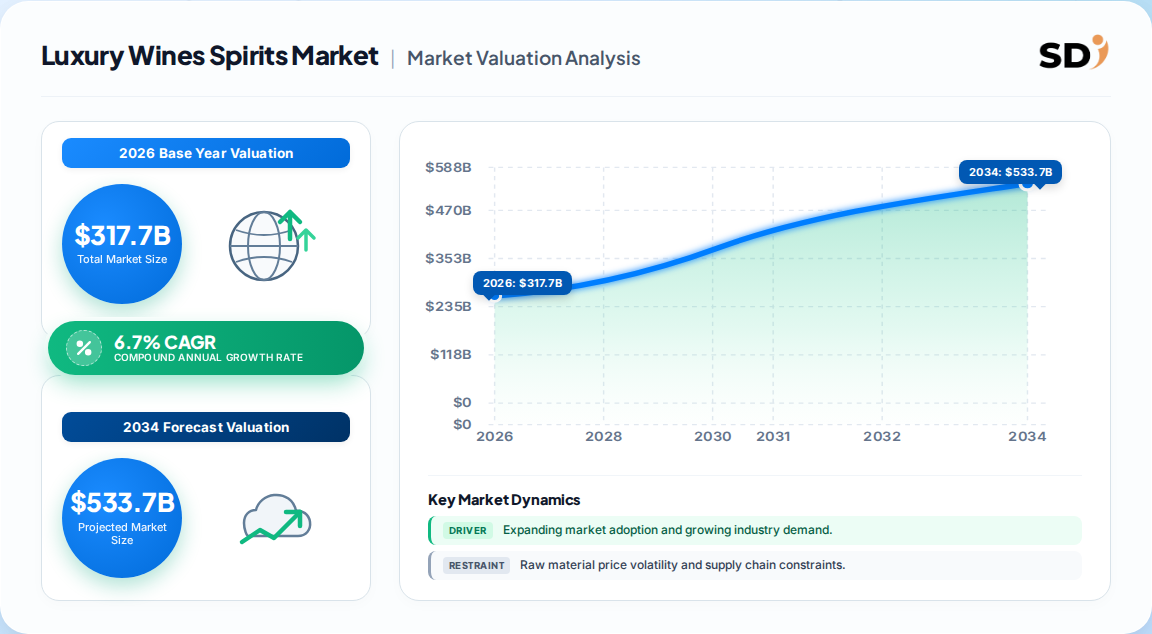
317.7 Billion is the estimated global luxury wines spirits market size in 2026, with a forecast of 533.8 Billion by 2035 at a 6.7% CAGR (2026–2035).
Europe leads with an estimated 35.6% revenue share by 2035, anchored by heritage winemaking and premium craft production.
Asia Pacific is the fastest-growing region, driven by rising disposable incomes, e-commerce penetration and western premiumization trends.
Wines/Champagnes hold the largest product share, while spirits grow faster due to cocktail culture and premium mixology.
Retail remains the dominant distribution channel; e-commerce is the fastest-growing, reshaping direct-to-consumer access.
Diageo, Pernod Ricard, LVMH (Moët Hennessy), Brown-Forman and Bacardi lead a concentrated competitive landscape.
Why this matters for decision-makers: Vendors must pivot toward experiential, digitally enabled and sustainability-certified luxury propositions to avoid margin compression as counterfeit risk and supply volatility intensify.
Luxury Wines Spirits Market Size (In Billion)
500.0B
400.0B
300.0B
200.0B
100.0B
0
297.8 B
2025
317.7 B
2026
339.0 B
2027
361.7 B
2028
385.9 B
2029
411.8 B
2030
439.4 B
2031
Luxury Wines Spirits Market Size (In Billion)
Year
Market Size
2025
297.8 B
2026
317.7 B
2027
339.0 B
2028
361.7 B
2029
385.9 B
2030
411.8 B
2031
439.4 B
What is the Luxury Wines Spirits Market?
The luxury wines spirits market comprises premium and super-premium alcoholic beverages — fine wines, champagnes, and aged or craft spirits such as whisky, cognac, vodka and gin — sold at price points and provenance standards that signal status, craftsmanship and scarcity to affluent and aspirational consumers worldwide.
Scope: what this report covers and excludes
This analysis covers global luxury wines and spirits across product type (wines/champagnes and spirits), price tiers (premium, super-premium, ultra-premium), distribution channels (retail, wholesale, e-commerce, others) and consumer end-use (individual, hospitality, gifting, events). This analysis does not cover mass-market table wine, beer, ready-to-drink cocktails, non-alcoholic beverages, or the broader alcoholic beverages market except where referenced as context.
How big is the market for Luxury Wines Spirits Market?
Estimates vary widely because each published figure uses a different definition of "luxury" and a different base year. The table below compares the major published benchmarks side by side.
Broad luxury wines and spirits incl. all spirits types
One published estimate
Our analysis suggests the 297.8 Billion (2025) to 533.8 Billion (2035) trajectory is the most defensible because it balances a conservative base-year definition with a bottom-up end-user segmentation that reconciles individual consumption, hospitality and gifting demand. The 867.9 Billion figure almost certainly employs an inflated definition that includes premium mass-market tiers, while the 229.4 Billion estimate uses a narrower pre-pandemic base. Buyers should treat the 6.2–6.7% CAGR band as the credible planning range.
How is the market segmented?
The market segments primarily by product type and distribution channel, with secondary cuts by price tier and consumer end-use.
Which region leads in Luxury Wines Spirits Market?
Europe leads the global luxury wines and spirits market, projected to command approximately 35.6% of revenue by 2035, supported by deep winemaking heritage in France, Italy and Spain and rising demand for organic and biodynamic offerings.
Luxury Wines Spirits Market Regional Market Share
Loading chart...
Luxury Wines Spirits Market Regional Market Share
Region
Market Share (%)
North America
0.24%
Europe
0.36%
Asia-Pacific
0.28%
South America
0.06%
Middle East & Africa
0.06%
The geographic hierarchy below shows the parent regions and their key country markets.
Europe — France, Italy, Spain, Germany, UK, Switzerland
Asia Pacific — China, India, Japan, South Korea, Australia, Singapore
North America — USA, Canada, Mexico
Latin America — Brazil, Argentina, Chile
Middle East & Africa — UAE, South Africa, Saudi Arabia
Asia Pacific is the fastest-growing region at an estimated 6.8–8.5% CAGR, with China and India contributing significantly through expanding vineyards, rising per capita wealth and premium spirits adoption. North America remains a mature, high-value market where premiumization and direct-to-consumer e-commerce offset flat volume growth.
What is driving growth — and what is holding it back?
Growth is driven by wealth transfer to younger consumers, premiumization, e-commerce expansion and sustainability credentials, while high prices, counterfeiting and regulatory restrictions constrain the pace.
Factor
Direction
Evidence strength
Mechanism
Wealth transfer to youth
Driver
High
USD 68–84 trillion expected to pass to descendants, reshaping luxury spending
Premiumization and artisanal demand
Driver
High
Consumers trade up for provenance, craft and unique flavor profiles
E-commerce and digital engagement
Driver
High
Direct-to-consumer access, subscription models and social media discovery
Rising disposable incomes in emerging markets
Driver
High
New affluent consumers in India, China and Southeast Asia
Sustainability and organic certification
Driver
Medium
Ethical sourcing influences purchase decisions, especially in Europe
Counterfeit products
Restraint
High
Brand integrity erosion and consumer health risk
High price points and excise duties
Restraint
High
Limits volume growth and raises landed costs in import markets
Regulatory restrictions on alcohol sales
Restraint
Medium
Advertising bans and licensing rules constrain channel expansion
Our analysis suggests the balance of forces favors growth, but the counterfeit challenge is underappreciated: as secondary-market and online sales expand, provenance authentication (blockchain, NFT-backed certificates) will become a margin-protection imperative rather than a marketing novelty.
Who are the leading vendors?
The market is concentrated among global beverage and luxury conglomerates, with differentiation built on brand heritage, portfolio breadth and distribution reach.
Company
HQ
Portfolio strength
Strategic positioning
Diageo Plc
UK
Scotch, gin, vodka, tequila
Global scale and premium spirits leadership
Pernod Ricard
France
Cognac, champagne, whisky
Premiumization and emerging-market reach
LVMH (Moët Hennessy)
France
Champagne, cognac, fine wines
Luxury brand equity and prestige pricing
Brown-Forman
USA
Whiskey, tequila
American whiskey moat and premium mixology
Bacardi Limited
Bermuda
Rum, gin, vodka
Cocktail culture and on-trade strength
Campari Group
Italy
Aperitifs, bitters, spirits
Premium aperitivo and cocktail-led growth
Suntory Holdings
Japan
Whisky, beer, spirits
Japanese whisky scarcity premium
Treasury Wine Estates
Australia
Fine wine
Penfolds luxury wine anchor
Competitive moats rest on terroir and aged inventory (whisky and champagne), brand storytelling and control of distribution. E-commerce has lowered barriers for niche craft producers, but the largest players retain pricing power through scarcity management and travel-retail networks.
What do buyers and operators need to know?
Procurement decisions in this market hinge on authenticity assurance, provenance documentation, and channel-specific licensing. Buyers should prioritize suppliers with verifiable chain-of-custody, bonded warehousing and sustainability certifications, because counterfeit risk and regulatory penalties fall on the importer as well as the brand. Switching costs are high in on-trade and hospitality because wine lists and staff training are brand-specific, so operators should negotiate multi-year supply agreements with allocation guarantees for ultra-premium SKUs. Regulatory compliance — excise duties, labeling, age-verification and cross-border e-commerce rules — varies sharply by jurisdiction; for example, Hong Kong applies 100% excise duty on the first HKD 25 of high-ABV beverages. Operators expanding into Asia Pacific must budget for licensing timelines and localized digital marketing compliance.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a premiumization-led growth thesis with a 6.2–6.7% CAGR through the early 2030s, but the strongest counter-argument is that volume growth in mature Western markets is stagnating and could drag headline value growth below consensus if emerging-market demand softens. We judge this risk manageable because Asia Pacific's income growth and Europe's pricing power provide offsetting momentum.
Our analysis suggests the next competitive battleground is provenance and experience, not price. Brands that invest in authenticated digital provenance, immersive vineyard and distillery tourism, and sustainability-certified portfolios will capture the wealth-transfer generation now entering peak consumption years.
Actionable Strategy:
Investors should overweight exposure to premium spirits and champagne portfolios with strong Asia Pacific distribution and authenticated secondary-market platforms.
Operators should build e-commerce and direct-to-consumer capabilities now to capture the fastest-growing channel and reduce reliance on wholesale margins.
Vendors should secure organic/biodynamic certifications and blockchain provenance to defend pricing against counterfeit encroachment.
Evidence that would change our conclusion: a sustained decline in China luxury spirits consumption, a sharp excise-duty escalation across the EU and UK, or a faster-than-expected shift to no-alcohol alternatives exceeding 5% of premium volume.
1. How big is the luxury wines and spirits market in 2026?
The global luxury wines and spirits market is estimated at 317.7 Billion in 2026 and is projected to reach 533.8 Billion by 2035, growing at a 6.7% CAGR during the forecast period.
2. Which region dominates the luxury wines and spirits market?
Europe dominates with an estimated 35.6% revenue share by 2035, driven by heritage winemaking in France, Italy and Spain, plus strong demand for organic and biodynamic premium products.
3. Which segment is growing fastest in the luxury wines and spirits market?
Spirits are growing faster than wines, supported by cocktail culture and premium mixology, while e-commerce is the fastest-growing distribution channel due to direct-to-consumer access.
4. Who are the leading players in the luxury wines and spirits market?
Leading players include Diageo, Pernod Ricard, LVMH (Moët Hennessy), Brown-Forman, Bacardi, Campari Group, Suntory Holdings and Treasury Wine Estates, competing on heritage, portfolio breadth and distribution.
5. What are the main challenges facing the luxury wines and spirits market?
Counterfeit products, high price points and excise duties, and regulatory restrictions on alcohol sales are the primary restraints, alongside supply chain fragility and raw material volatility.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including vineyard and raw material suppliers, specialized distillers and wineries, contract bottlers and formulators, global distributors, and travel-retail operators. Interviewees included VP-level Sourcing leads, Heads of R&D and product development, Technical Directors responsible for quality and compliance, and Commercial Operations Leads managing channel strategy across Europe and Asia Pacific. Interviews were structured to validate pricing tiers, volume allocation and channel margins.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
30%
Commercial Operations Leads
30%
Quality & Regulatory Directors
25%
R&D & Product Development Heads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Vineyards & Raw Material Suppliers
30%
Distillers & Wineries
35%
Global Distributors & Wholesalers
20%
Retail & E-commerce Operators
15%
Secondary Benchmarking & Public Trade Validation
We triangulate primary findings against official multilateral databases including UN Comtrade, WTO tariff and trade statistics, US ITC data, and Eurostat beverage trade flows. Corporate annual filings (10-K, SEC filings, investor presentations) from listed beverage companies provide revenue and volume benchmarks. Patent databases and recognized industry associations, including the OIV (International Organisation of Vine and Wine) and national spirits associations, validate production and consumption statistics. No competitor market-research publications are used as validation sources.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down and Bottom-Up models. The Top-Down model allocates macroeconomic beverage expenditure and industry segment share across regions and price tiers. The Bottom-Up model builds from manufacturer capacity, product pricing and end-use consumption modeling across individual, hospitality, gifting and event segments. Divergences between the two models are reconciled through expert review.
 Luxury Wines Spirits Market