 Organic Tobacco Market
: 2026 Size, CAGR & Strategic Outlook
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 240

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Organic Tobacco Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 234.0 M |
| 2026 | 254.0 M |
| 2027 | 274.0 M |
| 2028 | 296.0 M |
| 2029 | 319.0 M |
| 2030 | 344.0 M |
| 2031 | 371.0 M |

The organic tobacco market comprises certified tobacco grown without synthetic pesticides or fertilizers, processed with minimal additives, and sold as smoked or smokeless products. It serves adult consumers seeking natural positioning, premium cigars, roll-your-own blends, and additive-free alternatives, though regulators mandate that organic claims do not imply reduced health risk.
This report covers global certified organic tobacco cultivation, processing, and trade across flue-cured, sun-cured, fire-cured, and air-cured leaf types. It includes smoked and smokeless applications in semi-processed and processed forms across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. This analysis does not cover conventional tobacco markets, nicotine replacement therapies, vaping or heated tobacco products, or non-tobacco organic agricultural commodities.
Estimates vary widely due to divergent definitions of certified organic scope and conflicting data on farm-gate versus retail value. The table below benchmarks published figures.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 143.8 Million | 2026 | 2033 | 4.3% | Certified organic leaf and branded retail products | One published estimate |
| 252.9 Million | 2026 | 2033 | 8.5% | Certified organic tobacco retail value, global | A competing analysis |
| 275.72 Million | 2027 | 2036 | 8.55% | Certified organic tobacco, farm-gate and intermediate | Another published analysis |
| 3.82 Billion | 2025 | 2035 | 4.56% | Broad organic tobacco including informal and uncertified | A broader-scope estimate |
Our analysis favors the 254 million base because the 3.82 billion figure likely includes uncertified natural tobacco and informal markets, inflating the addressable certified segment. The 143.8 million estimate may undercount retail value by focusing on farm-gate pricing. The convergence of two estimates near 254 million for 2026 supports a defensible base.
Organic tobacco segments by curing method, application, processing stage, and finished format, with smoking applications commanding the majority share.
| Parent Segment | Children |
|---|---|
| By Type | Flue-cured, Sun-cured, Fire-cured, Air-cured |
| By Application | Smoking (cigarettes, cigars, roll-your-own), Smokeless (chewing, snus) |
| By Form | Semi-processed (whole leaf, threshed), Processed (cut tobacco, branded blends) |
| By Certification | USDA Organic, EU Organic, Other certified organic |
Our analysis suggests the processed segment (4.9% CAGR) will outpace semi-processed as branded premium products capture higher margins, though certified leaf traceability remains the binding constraint on supply.
Asia-Pacific leads in growth while North America holds the largest revenue share, with certified organic leaf farming concentrated in India, China, Brazil, and Indonesia.
| Region | Market Share (%) |
|---|---|
| North America | 0.28% |
| Europe | 0.24% |
| Asia-Pacific | 0.4% |
| South America | 0.04% |
| Middle East & Africa | 0.04% |
Regional share snapshot (2026): North America 28% · Europe 24% · Asia-Pacific 40% · Latin America 4% · Middle East & Africa 4%. Our analysis notes Asia-Pacific's 40% share reflects farm-gate production volume rather than retail value, where North America still commands premium pricing. This divergence implies leaf merchants and exporters should prioritize certified supply from India and Indonesia to serve European and North American buyers.
Consumer preference for natural, additive-free products and tightening pesticide residue rules drive demand, while tobacco control laws and higher organic farming costs restrain expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Natural/additive-free preference | Driver | Medium | Adult smokers seek fewer ingredients; premium pricing supports value growth |
| Sustainable sourcing rules | Driver | Medium | EU residue limits and corporate targets push exporters to organic methods |
| Tobacco control laws | Restraint | High | WHO reports 1.2 billion users in 2024; taxes, bans, plain packaging reduce volumes |
| Organic farming costs | Restraint | Medium | Lower yields, certification costs, crop rotation limits constrain supply |
Our analysis suggests the regulatory driver is stronger than commonly acknowledged: tightening EU maximum residue limits effectively forces exporters toward certified organic methods, creating a compliance-driven supply pool independent of consumer demand. However, this supply growth may outpace demand in markets where tobacco control suppresses volumes, creating margin pressure for undifferentiated certified leaf.
Competitive positioning spans vertically integrated tobacco majors, specialty organic brands, and certified leaf merchants, with differentiation anchored in certification, traceability, and premium brand equity.
| Company | Category | Differentiation |
|---|---|---|
| Santa Fe Natural Tobacco (Reynolds American) | Branded cigarettes | Organic certified leaf, additive-free positioning, US distribution |
| Philip Morris International | Multinational | Broad portfolio, premium pricing, global reach |
| Japan Tobacco International | Multinational | Regional adaptation, eco-conscious packaging |
| Imperial Brands | Multinational | Budget-friendly RYO, resealable pouches |
| Swedish Match | Smokeless specialist | Organic snus and chewing tobacco leadership |
| Universal Corporation | Leaf merchant | Contract grower programs, traceability |
| Pyxus International | Leaf merchant | Certified organic sourcing, farmer training |
Our analysis indicates the moat lies in certified supply access rather than brand alone. Leaf merchants with contract grower networks control the critical upstream link, giving them leverage over branded manufacturers who lack direct farm relationships.
Procurement of certified organic tobacco hinges on verification of certification integrity, traceability from farm to factory, and compliance with evolving residue limits. Buyers should prioritize suppliers with multi-year contract grower programs and digital tracking capabilities. Switching costs are high because organic certification requires multi-year farm conversion, limiting the pool of qualified suppliers. Regulatory risk is significant: the FDA and EU restrict "natural" claims, and mislabeling carries legal exposure. Operators must also account for yield volatility from weather and pest pressure, which is more severe without synthetic inputs. Our analysis suggests buyers locking in certified supply now will avoid premium spikes as EU residue rules tighten through 2027.
The balance of evidence favors a compliance-driven supply thesis over a consumer-demand thesis. Organic tobacco growth is being pulled by regulatory residue limits and corporate sustainability targets more than by organic consumer preference, which remains a niche of roughly 30% of tobacco users considering organic options. The strongest counter-argument is that tobacco control will overwhelm any niche premium; however, the premium cigar and roll-your-own segments face less volume erosion than mass-market cigarettes, providing a viable revenue pool.
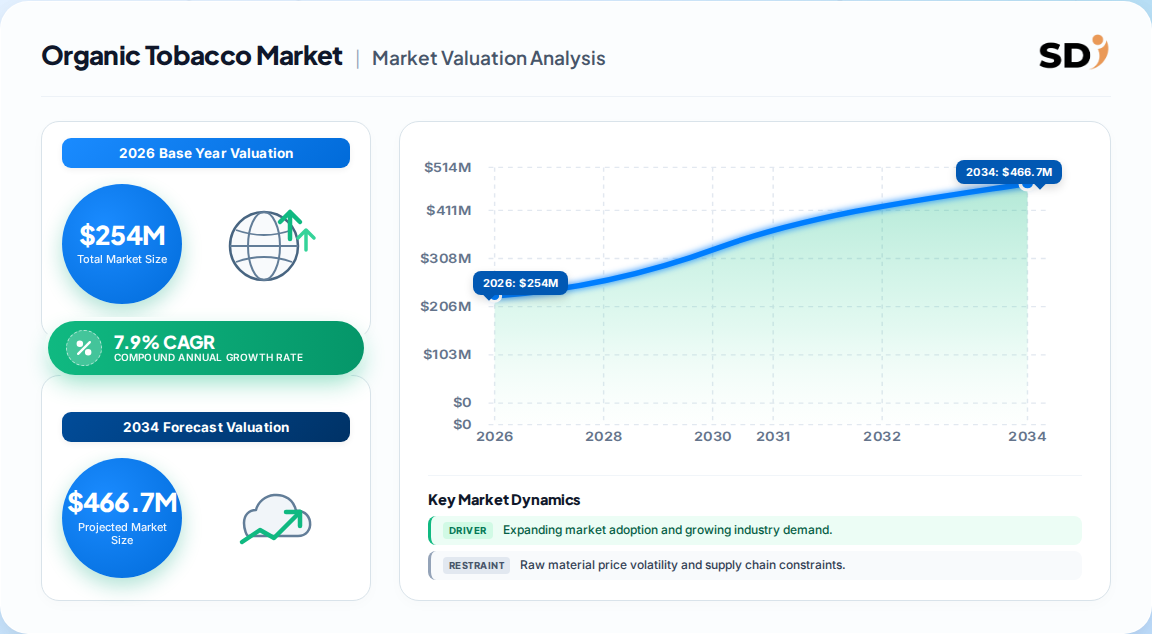
Our analysis suggests the most defensible position is upstream: certified leaf supply with traceability. Brands that secure contract grower relationships and certification will command pricing power as EU rules tighten. The 7.9% CAGR is achievable only if certified acreage expands; without it, supply constraints will cap growth below forecast.
Actionable strategy:
What would change our conclusion: if FDA nicotine caps or UK generational bans accelerate volume decline beyond 5% annually, even premium segments would face margin compression, undermining the niche premium thesis.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
The global organic tobacco market is valued at approximately 254 million in 2026, with a forecast to reach about 434 million by 2033 at a 7.9% CAGR, reflecting sustained niche demand.
North America holds the largest retail revenue share at roughly 28%, while Asia-Pacific leads in certified leaf production volume and is the fastest-growing region at 5.6% CAGR through 2033.
Consumer preference for natural, additive-free products and tightening EU pesticide residue limits are the primary drivers, pushing exporters toward certified organic cultivation and traceable supply chains.
Leading vendors include Santa Fe Natural Tobacco (Reynolds American), Philip Morris International, Japan Tobacco, Imperial Brands, Swedish Match, and Djarum, alongside certified leaf merchants Universal Corporation and Pyxus International.
No. Regulators including the FDA require packaging to state that organic tobacco is not safer than conventional tobacco. All tobacco products cause serious harm regardless of cultivation method.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conducted in-depth interviews with stakeholders across the organic tobacco value chain, including certified leaf growers, specialized organic tobacco processors, contract formulators for branded blends, global leaf merchants, and specialty distributors. Interview participants were drawn from decision-maker roles including VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring insights reflect operational and strategic realities.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 35% |
| Technical & R&D Heads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Certified Leaf Growers & Cooperatives | 40% |
| Specialized Organic Processors & Formulators | 30% |
| Global Leaf Merchants & Distributors | 30% |
We validate findings against official multilateral trade databases including UN Comtrade, WTO tariff and trade statistics, US ITC data, and Eurostat agricultural trade flows. Corporate annual filings (10-K, SEC filings, investor presentations) from publicly traded tobacco companies and leaf merchants provide revenue and capacity benchmarks. Patent databases and recognized non-profit technical standards, including USDA Organic and EU Organic certification frameworks, inform regulatory and compliance analysis.
Our sizing approach triangulates Top-Down macroeconomic allocation across tobacco industry segments with Bottom-Up modeling of manufacturer capacity, certified acreage, product pricing, and end-use consumption. This dual approach reconciles farm-gate value with retail revenue, isolating certified organic scope from broader natural tobacco categories.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |