 Emollients Personal Care Market
 Outlook 2025
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 243

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Emollients Personal Care Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 4.870 B |
| 2025 | 5.060 B |
| 2026 | 5.250 B |
| 2027 | 5.450 B |
| 2028 | 5.660 B |
| 2029 | 5.870 B |
| 2030 | 6.100 B |

The emollients personal care market covers ingredients formulated into skincare, haircare, cosmetics and sun care to soften skin, improve spreadability, restore barrier function and deliver sensory feel. It spans green biobased esters, vegetable oils, silicone fluids and mineral oils sold to brands, contract formulators and ingredient houses.
Scope is global, covering emollient ingredients sold into personal care and cosmetic formulations across four product families: green/biobased, silicone fluids, mineral oils and other specialty emollients. Revenue is measured at manufacturer-level ingredient sales, not finished consumer product retail. This analysis does not cover the broader industrial emollients market, pharmaceutical excipients, or finished cosmetic product retail values.
Published estimates cluster around USD 4.8–5.2 billion for 2024–2026, converging on roughly USD 6.8 billion by 2033. The divergence is scope-driven: narrower "personal care emollients" definitions exclude pharma and industrial uses, while broader definitions inflate the base by 5x.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 4.87 Billion | 2024 | 2033 | 3.8% | Emollient ingredients sold into personal care only | One published estimate (Grand View-style scope) |
| USD 5.2 Billion | 2026 | 2033 | 3.8% | Same personal-care-only scope, forward base | Competing analysis |
| USD 6.55 Billion | 2024 | 2034 | 3.6% | Personal-care emollients, product-segmented | Alternative published estimate |
| USD 28.79 Billion | 2024 | 2035 | 3.48% | All emollients incl. pharma, industrial, infant care | Broader industrial-emollient definition |
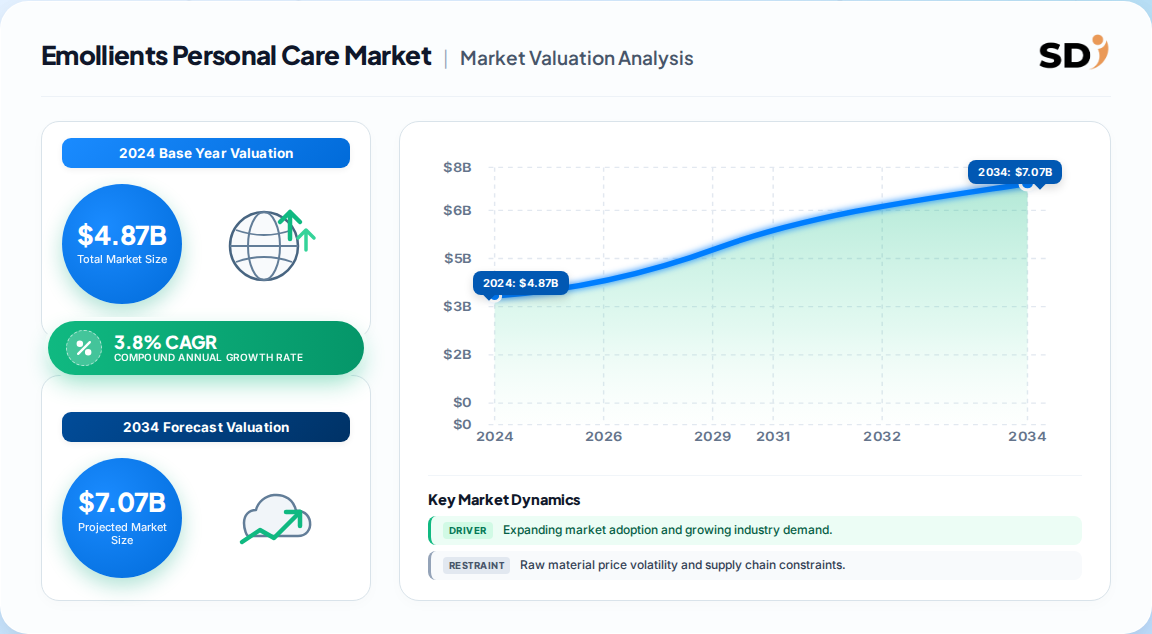
Our analysis suggests the USD 4.87 billion, 3.8% CAGR baseline is the most defensible for personal care buyers: it aligns with the 72.5% green-emollient share and Asia Pacific's 33% regional weight. The USD 28.79 billion figure is not a competing view of the same market — it is a fundamentally wider definition and should not be used for personal care procurement planning.
Segmentation runs on two axes: product chemistry and end application. Product chemistry is the primary strategic lens because it determines regulatory exposure, sustainability positioning and pricing power.
| Parent segment | Children | 2024 position |
|---|---|---|
| Product | Green (biobased esters, biobased alkanes, vegetable oils, others) | Largest, ~72.5% share; fastest growth (4.1%) |
| Product | Silicone fluids (cyclomethicones, dimethicones, others) | Mature; regulatory pressure; 2.4% volume CAGR |
| Product | Mineral oils (petrolatum, paraffinum liquid, synthetic hydrocarbons, others) | Cost-led; declining relative share |
| Application | Skin care, hair care, sun care, color cosmetics, baby care | Skin care largest; hair care fastest |
| Formulation | Creams, lotions, gels, ointments | Creams largest; gels fastest |
Implication: the product-chemistry split, not application, is where margin and regulatory risk concentrate. Buyers should benchmark supplier portfolios against the green share, not the application mix.
Asia Pacific leads with roughly one-third of global revenue, driven by K-beauty and J-beauty formulation trends favoring lightweight, multifunctional textures, plus rapid urbanization and rising disposable income in China, Japan, South Korea and India.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.33% |
| North America | 0.24% |
| Europe | 0.23% |
| Latin America | 0.11% |
| Middle East & Africa | 0.09% |
| Region | 2024 share | Growth posture |
|---|---|---|
| Asia Pacific | ~33% | Largest; China leads growth |
| North America | ~24% | Fastest acceleration on clean-label shift |
| Europe | ~23% | Regulatory-led reformulation |
| Latin America | ~11% | Premium skincare expansion |
| Middle East & Africa | ~9% | Nascent, price-sensitive |
The North America acceleration is the second-order signal worth acting on: clean-label purchasing behavior is migrating from niche to mainstream, which re-prices bio-based emollients upward in the highest-margin region.
Growth is driven primarily by clean-beauty reformulation, multifunctional skincare demand and an aging population needing barrier-repair actives. Restraints are regulatory scrutiny of silicones and petroleum derivatives, plus formulation instability of natural alternatives.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Clean beauty / natural ingredients | Driver | High | Reformulation toward green esters and alkanes |
| Multifunctional skincare demand | Driver | High | Single emollient delivering sensory + barrier + SPF support |
| Aging population (2.1B aged 60+ by 2050) | Driver | Medium-High | Barrier-repair and anti-aging formulations |
| E-commerce expansion | Driver | Medium | Access and comparison for premium SKUs |
| Silicone/petroleum regulatory scrutiny | Restraint | High | Reformulation cost and supply-chain adjustment |
| Natural emollient stability limits | Restraint | Medium | Oxidation, shelf-life and performance inconsistency |
| Raw material cost volatility | Restraint | Medium | Margin pressure on bio-based inputs |
The balance favors growth, but the drivers and restraints are not symmetric: clean-beauty demand is structural and compounding, while regulatory and stability constraints are episodic and addressable through formulation R&D. Our analysis suggests the net effect is a steady 3.6–4.0% CAGR rather than an acceleration.
Competition is moderately fragmented: a handful of global specialty chemical players dominate by scale, pricing and portfolio breadth, while regional bio-based specialists capture the fastest-growing green niches.
| Company | Positioning | Strategic moat |
|---|---|---|
| BASF SE | Broad portfolio, scale | Global reach, formulation support |
| Clariant AG | Green and specialty emollients | Sustainability positioning |
| Croda International | Bio-based and sensory emollients | Innovation pipeline, clean-label credibility |
| Evonik Industries | Specialty and silicone alternatives | R&D depth |
| Ashland Global | Personal care focus | Application expertise |
| Dow Inc. | Silicone and specialty fluids | Manufacturing scale |
| Eastman Chemical | Esters and specialty | Cost and capacity |
| Kao, Lubrizol, Momentive, Wacker, Stepan, Vantage, Hallstar, Lonza | Niche and regional strength | Application-specific IP |
Differentiation increasingly rests on bio-based feedstock access and formulation support rather than pure price. Vendors that cannot demonstrate a credible green roadmap will lose specification wins in North America and Europe first.
Selection criteria have shifted from pure sensory performance to a combined scorecard: biodegradability, feedstock traceability, sensory equivalence to silicones, and supply reliability. Procurement teams should require documented biodegradation and feedstock origin, not just INCI naming.
Switching costs are non-trivial. Replacing a silicone or mineral oil emollient typically triggers full reformulation, stability retesting and, in the EU, re-assessment under cosmetic ingredient frameworks. That creates sticky incumbent relationships but also a first-mover advantage for suppliers who pre-qualify bio-alternatives with sensory parity data.
Regulatory compliance is the sharpest risk. Silicone restrictions and petroleum-origin scrutiny are advancing unevenly by jurisdiction, so multi-region brands need suppliers with region-specific compliance documentation. Natural emollients introduce their own risk: oxidation and batch inconsistency can drive shelf-life failures, so incoming quality protocols must be tightened.
Operationally, dual-sourcing across green and mineral oil lines preserves cost flexibility during transition, but blending them in one SKU risks clean-label credibility. The practical recommendation is portfolio separation: premium green lines and value mineral lines managed as distinct supply chains.
The balance of evidence favors a green-led growth thesis, but with a moderating rather than accelerating curve. The 72.5% green share and 4.1% green CAGR are consistent across sources and are reinforced by North America's clean-label acceleration. The strongest counter-argument is cost: mineral oils and silicone fluids remain entrenched in cost-sensitive and high-performance applications, and natural emollient stability problems are real, not theoretical. That caps green substitution at the margin rather than driving wholesale replacement.
Our judgment is that the 3.8% consensus CAGR is credible for the total market, but hides a bifurcation: green emollients likely compound faster than 4% while silicone and mineral oils stagnate or decline in premium segments. Buyers who plan at the blended rate will under-invest in bio-based capacity and over-invest in legacy lines.
The divergence between the USD 4.87 billion personal-care scope and the USD 28.79 billion all-emollient scope is the single most common source of planning error we observe. Teams should lock the personal-care-only definition before benchmarking any supplier or market share claim.
Actionable Strategy
What would change this conclusion: a faster-than-expected regulatory clampdown on a major silicone or petroleum emollient, or a breakthrough in natural-emollient stabilization technology. Either would accelerate the green shift well beyond the 3.8% blended baseline.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.8% from 2020-2034 |
| Segmentation |
|
The emollients personal care market was valued at approximately USD 4.87 billion in 2024. It is projected to reach about USD 6.82 billion by 2033, growing at a compound annual rate of roughly 3.8%.
Asia Pacific leads with roughly one-third of global revenue, supported by K-beauty and J-beauty trends and rising disposable income. North America is the fastest-accelerating region on clean-label demand.
The main types are green biobased emollients (esters, alkanes, vegetable oils), silicone fluids (dimethicones, cyclomethicones), mineral oils (petrolatum, paraffinum liquid) and other specialty emollients.
Green emollients benefit from clean-beauty demand, biodegradability and regulatory tailwinds. Silicone fluids face scrutiny over environmental persistence, prompting reformulation despite superior spreadability and sensory performance.
Leading suppliers include BASF, Clariant, Croda International, Evonik, Ashland, Dow, Eastman Chemical, Kao, Lubrizol, Momentive, Wacker, Stepan and Vantage Specialty Chemicals.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews are conducted across the value chain with raw material and feedstock suppliers, specialized emollient producers, contract formulators and blenders, and global ingredient distributors. Decision-maker designations include VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads. Interview guides probe specification criteria, reformulation triggers, regulatory documentation requirements and switching costs. Fieldwork is weighted toward Asia Pacific and North America, reflecting their combined share of demand.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Leads | 40% |
| Procurement & Sourcing Directors | 35% |
| Regulatory & Quality Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 40% |
| Formulators & Blenders | 30% |
| Distributors & Traders | 30% |
We benchmark against official multilateral trade and standards databases including UN Comtrade, WTO tariff schedules, US ITC data and Eurostat chemical trade flows. Corporate annual filings (10-K, SEC, investor presentations) from listed ingredient suppliers inform capacity, revenue and segment disclosures. Patent databases and recognized technical standards bodies validate innovation direction and formulation claims.
We run simultaneous Top-Down and Bottom-Up models. Top-down allocates macroeconomic cosmetic and personal care output to the emollient ingredient layer using segment intensity ratios. Bottom-up models manufacturer capacity, product pricing and end-use consumption by application and region. Divergence between the two is reconciled through structured expert review.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |