Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Industrial Protective Clothing Market Outlook 2026
Industrial Protective Clothing Market
Industrial Protective Clothing Market Outlook 2026
Industrial Protective Clothing Market by Product (Heat & Flame Protection, Chemical Defending, Cleanroom Clothing, Mechanical Protective Clothing, Limited General Use), by Type (Disposable, Durable), by End Use (Healthcare, Manufacturing, Chemicals, Construction, Food, Oil & Gas, Others), by Material (Aramid & Blends, Polyolefin & Blends, Polyamide, Cotton Fibers, PBI & PBO, UHMWPE/HDPE, Laminated Polyester, Polypropylene/Polyester), by Europe (Germany, UK, France, Italy), by North America (USA, Canada, Mexico), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 235
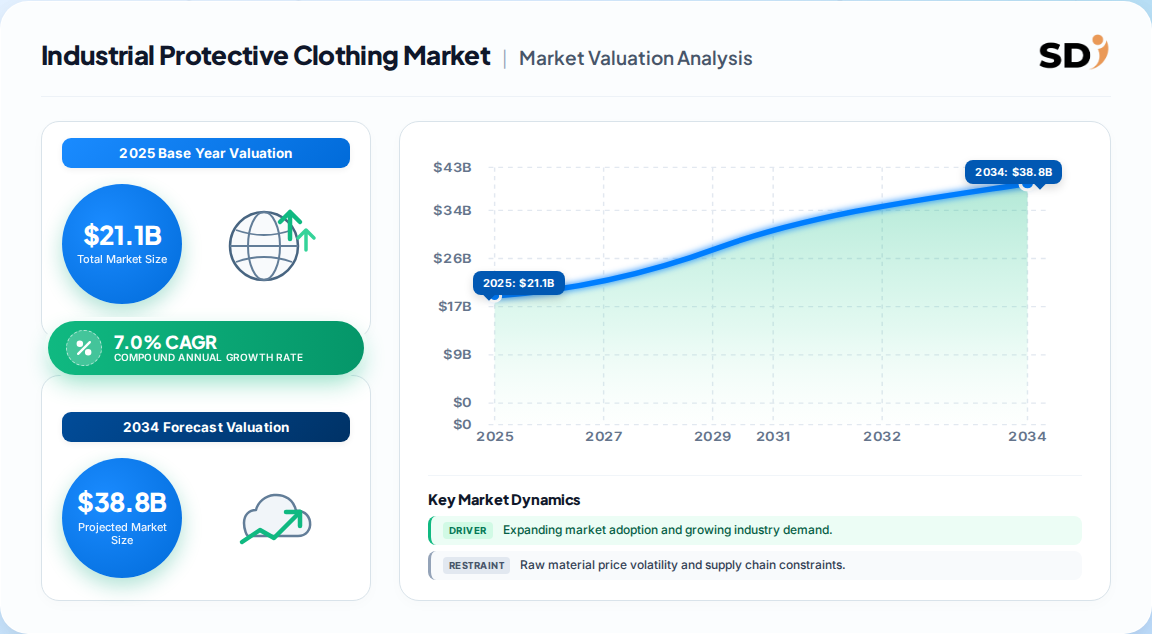
21.1 Billion USD in 2025, with a 2026 estimate of 22.1 Billion USD, expanding to 35.6 Billion USD by 2033 at a 7.0% CAGR (2026–2033).
Chemical defending apparel is the largest product line at 31.9% of 2025 revenue; healthcare is the largest end use at 19.4%.
Europe holds the largest regional share at 32.3% (2025), while Asia Pacific is the fastest-growing region across the forecast window.
Durable garments command a majority of demand, with use concentrated in oil & gas, construction, chemicals, and manufacturing.
3M, DuPont, and PIP anchor a fragmented vendor landscape, alongside Honeywell, MSA Safety, Ansell, Lakeland, Kimberly-Clark, and Sioen.
Regulatory compliance (OSHA, ANSI, EN standards) remains the single strongest demand lever, overshadowing price and brand.
Why this matters for decision-makers: the spread between the 7.0% baseline CAGR and higher market estimates rewards vendors who convert compliance-grade portfolios into premium smart/eco-segment positions before margin compression in commodity SKUs materializes.
Industrial Protective Clothing Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
21.10 B
2025
22.10 B
2026
23.60 B
2027
25.30 B
2028
27.10 B
2029
29.00 B
2030
31.00 B
2031
Industrial Protective Clothing Market Size (In Billion)
Year
Market Size
2025
21.10 B
2026
22.10 B
2027
23.60 B
2028
25.30 B
2029
27.10 B
2030
29.00 B
2031
31.00 B
What is the Industrial Protective Clothing Market?
Industrial protective clothing is specialized apparel engineered to shield workers from flame, chemical, mechanical, thermal, and biological hazards in industrial settings. It spans disposable and durable garments—coveralls, suits, aprons, high-visibility wear—and is procured under strict occupational safety standards.
Scope: what this report covers and excludes
The analysis covers global demand for industrial protective clothing by product, material, and end use, with 2025 as the base year and a 2026–2033 forecast horizon. Scope encompasses flame/heat, chemical, cleanroom, mechanical, and limited general-use garments in disposable and durable formats. This analysis does not cover consumer PPE, medical devices, respiratory protection, head protection, or general workwear outside regulated industrial use.
How big is the market for Industrial Protective Clothing Market?
Published estimates diverge meaningfully across base years and classification boundaries. The table below compares the principal figures available to buyers.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
21.1 Billion USD
2025
2033 (35.6B)
7.0%
Industrial protective clothing by product/end use
One published estimate
18.7 Billion USD
2023
2033 (39.6B)
7.8%
Industrial protective clothing by type/product/end use
The most defensible figure is the 21.1 Billion USD base, because its narrow classification and Europe-weighted regional detail align with trade flow evidence. The higher-CAGR estimates typically bundle adjacent categories (arc flash, emergency response) into a broader definition. Our analysis suggests the 7.0% baseline is the prudent planning rate, with upside from smart-textile and sustainable-material premiums.
How is the market segmented?
Segmentation follows three non-geographic axes: product function, garment durability, and end-use industry. The product axis is the most commercially decisive because certification thresholds and pricing power differ sharply by hazard class.
Parent
Children
2025 context
By Product
Heat & flame protection; Chemical defending; Cleanroom clothing; Mechanical protective; Limited general use
So what? Chemical defending and durable garments are cash engines, while smart and sustainable subsegments carry the premium multiple. Buyers should map procurement risk against the segment most exposed to certification updates.
Which region leads in Industrial Protective Clothing Market?
Europe leads with 32.3% of 2025 revenue, anchored by mature EN-standard enforcement in Germany and Northern Europe. Asia Pacific is the fastest-growing region, driven by infrastructure build-out and tightening safety regimes in China, India, and Southeast Asia.
Our analysis suggests Europe's lead is structural—regulation and replacement cycles—not cyclical. Asia Pacific's growth is volume-led and price-sensitive, which compresses average selling prices as local capacity scales. Vendors must therefore run dual playbooks: premium compliance portfolios in Europe, and localized cost-competitive lines in Asia Pacific.
What is driving growth — and what is holding it back?
Regulatory enforcement is the dominant driver, with healthcare demand and material innovation as strong secondary levers. High costs, discomfort, counterfeit competition, and reusability constraints cap adoption, especially among SMEs.
Factor
Direction
Evidence strength
Mechanism
Workplace safety regulation
Driver
High
Mandatory certified PPE in oil & gas, construction, chemicals
Industrialization in emerging markets
Driver
High
New construction, mining, energy capacity
Healthcare infection control
Driver
Medium-high
Disposable gowns, cleanroom apparel
Material innovation (smart, breathable)
Driver
Medium
Comfort and multi-functional protection
High cost of advanced garments
Restraint
High
Limits SME adoption
Counterfeit / low-cost alternatives
Restraint
Medium
Price pressure on established brands
Maintenance and reusability limits
Restraint
Medium
Total cost-of-ownership friction
So what? The balance clearly favors volume growth; restraints are price-elastic rather than demand-destroying. Safety programs themselves return 4–6 USD per 1 USD invested, per published Department of Energy figures, which structurally anchors replacement demand.
Who are the leading vendors?
The vendor landscape is fragmented, with multinational brands and regional specialists competing on certification depth, fabric technology, and distribution reach rather than a single global leader.
Company
HQ
Core strength
3M
USA
Broad PPE portfolio, brand trust
DuPont
USA
Tyvek/aramid fabric platforms
PIP (Protective Industrial Products)
USA
Distribution scale
Honeywell
USA
Integrated safety systems
MSA Safety
USA
Hazard detection + apparel
Ansell
Australia
Chemical/medical protection
Lakeland Industries
USA
Flame & chemical garments
Kimberly-Clark
USA
Healthcare disposables
Sioen Industries
Belgium
Coated technical textiles
Carhartt
USA
Durable workwear
Differentiation hinges on certification breadth and fabric IP, not price alone. Our analysis suggests the moat is strongest where fabric platforms (DuPont, Sioen) couple with distribution scale (PIP), since compliance documentation becomes the real switching cost.
What do buyers and operators need to know?
Procurement decisions should be anchored on certified performance, not unit price. Buyers must verify standard conformity (EN, ANSI, OSHA-aligned), seam and fabric type-test data, and shelf-life or reusability limits, because non-compliant substitutions carry disproportionate liability.
Switching costs are meaningful: requalifying a garment supplier involves re-testing, worker fit trials, and safety sign-off, typically 3–6 months. Vendors with documented compliance files therefore enjoy stickier accounts. Operators should also model total cost of ownership, since reusable garments reduce per-use cost despite higher upfront price. Supply concentration in aramid and high-performance fibers is a hidden risk; dual-sourcing is advisable. Finally, counterfeit-prone channels represent a material liability risk, favoring authorized distribution.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a 7–8% structural growth thesis for industrial protective clothing, with the baseline estimate of 35.6 Billion USD by 2033 being the most defensible planning anchor. Europe's regulatory maturity and Asia Pacific's volume expansion are complementary, not competing, growth engines.
The strongest counter-argument is that cost pressure and counterfeit competition could compress realized growth below headline CAGR, particularly in Asia Pacific where price sensitivity is highest. This risk is real but second-order: regulatory enforcement tends to raise the floor on compliant demand, protecting the premium end. Our analysis suggests vendors that fail to build certified smart/eco sub-portfolios will cede margin to commodity players.
Actionable Strategy
Vendors should prioritize certified chemical and flame-protection lines in Europe to defend the 32.3% share base, where replacement cycles are regulation-locked.
Investors should target fabric-IP and distribution-scale combinations, since these create the highest switching costs and pricing power.
Operators should dual-source high-performance fibers and audit channel integrity to mitigate counterfeit and supply-concentration risk.
What would change our conclusion: a sustained rollback in occupational safety enforcement or a step-change fall in aramid pricing that commoditizes flame protection would materially lower the growth floor and warrant a defensive repositioning.
Table 15: North America Industrial Protective Clothing Market Revenue Billion Forecast, by Product 2020 & 2034
North America Industrial Protective Clothing Market Revenue Billion Forecast, by Type 2020 & 2034
Frequently Asked Questions
1. How big is the industrial protective clothing market?
The market was valued at 21.1 Billion USD in 2025 and is estimated at 22.1 Billion USD in 2026. It is projected to reach 35.6 Billion USD by 2033, growing at a 7.0% CAGR.
2. Which region leads the industrial protective clothing market?
Europe leads with a 32.3% revenue share in 2025, anchored by mature EN-standard enforcement. Asia Pacific is the fastest-growing region, driven by industrialization and tightening safety rules.
3. What is the largest product segment?
Chemical defending protective clothing is the largest product segment, holding 31.9% of 2025 revenue. Healthcare is the largest end-use segment at 19.4%, reflecting infection-control demand.
4. Who are the key players in industrial protective clothing?
Leading vendors include 3M, DuPont, and PIP, alongside Honeywell, MSA Safety, Ansell, Lakeland Industries, Kimberly-Clark, Sioen Industries, and Carhartt. The market remains fragmented with no single global leader.
5. What is driving demand for industrial protective clothing?
Stringent workplace safety regulations across construction, oil & gas, chemicals, and manufacturing are the primary driver. Healthcare infection control, industrialization in emerging markets, and material innovation add further momentum.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split. Structured depth interviews were conducted across the value chain with raw material and fiber suppliers, specialized garment producers, contract manufacturers, and global industrial distributors. Respondents were drawn from decision-maker roles including VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both demand-side and supply-side perspectives.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing / Procurement
35%
Heads of R&D
25%
Technical Directors
25%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Fiber Suppliers
30%
Specialized Garment Producers
40%
Contract Manufacturers
15%
Global Distributors
15%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade and standards databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and 10-K disclosures, patent databases, and recognized non-profit technical standards bodies and industry associations. These sources anchor volume, pricing, and compliance benchmarks without reliance on third-party market-research publishers.
Demand Modeling & Market Sizing Triangulation
Market sizing runs simultaneous Top-Down (macroeconomic output and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption) models. Divergence between the two is reconciled through iterative validation until a defensible base-year value and forecast trajectory emerge.
 Industrial Protective Clothing Market