Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Luxury Mice Hotels Market by Hotel (5-Star Luxury, Ultra-Luxury, Integrated Resorts), by Event (Meetings, Incentives, Conferences, Exhibitions), by Meeting Size (Under 100, 100-499, 500-999, 1, 000+), by Event Theme (Technology & Digital Innovation, Leadership & Strategy, Product Launch, Wellness & Retreat), by Booking Mode (Direct, Corporate Travel Agency, Third-Party Marketplace), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Switzerland), by Asia Pacific (China, Japan, India, South Korea, Singapore, Australia), by Latin America (Brazil, Argentina, Colombia, Chile), by Middle East & Africa (UAE, Saudi Arabia, Turkey, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 265
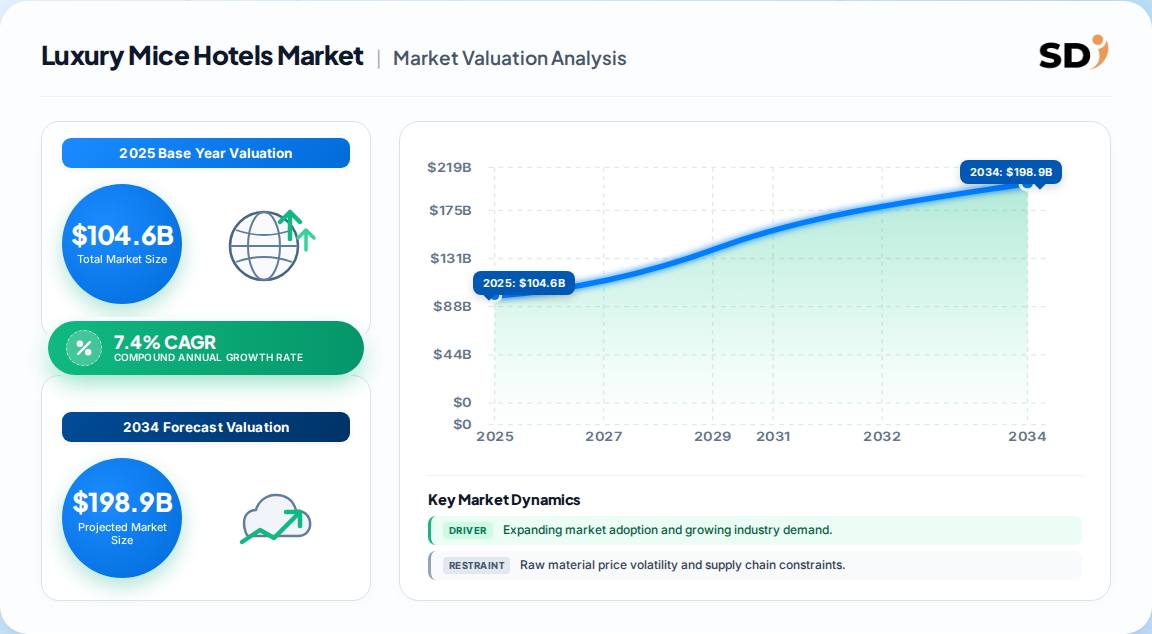
The global luxury MICE hotels market was valued at 104.6 Billion in 2025, with a base-year estimate of 112.3 Billion for 2026, reflecting recovered corporate group demand.
Forecast growth of 7.4% CAGR (2026–2033) lifts the market to roughly 185 Billion by 2033 — faster than the broader hotel market's ~6.2% trajectory.
5-star and ultra-luxury properties dominate inventory, but incentive programs and technology-themed events are the fastest-compounding demand pockets.
North America leads with roughly 34% of global luxury MICE revenue, followed by Asia-Pacific (28%) and Europe (26%).
Meetings remain the largest event type at 36.1% of U.S. segment revenue; 500–999 delegate events lead meeting-size share at 24.0%.
Marriott, Hilton, Accor, IHG and Hyatt anchor the competitive field, competing increasingly on experiential programming rather than room rate.
Why this matters for decision-makers: Group spend is shifting from rate to experience — operators who cannot monetize curated programming, wellness and AI-driven RFP response will cede margin to experience-led ultra-luxury competitors.
Luxury Mice Hotels Market Size (In Billion)
150.0B
100.0B
50.0B
0
97.40 B
2024
104.6 B
2025
112.3 B
2026
120.6 B
2027
129.5 B
2028
139.1 B
2029
149.4 B
2030
Luxury Mice Hotels Market Size (In Billion)
Year
Market Size
2024
97.40 B
2025
104.6 B
2026
112.3 B
2027
120.6 B
2028
129.5 B
2029
139.1 B
2030
149.4 B
What is the Luxury Mice Hotels Market?
The luxury MICE hotels market covers premium and ultra-luxury hotel properties purpose-built or purpose-adapted to host Meetings, Incentives, Conferences and Exhibitions — combining high-specification meeting space, banqueting, advanced AV, and personalized group services with five-star accommodation and dining.
Scope: what this report covers and excludes
Scope covers global luxury and ultra-luxury hotels generating revenue from group MICE business — meetings, incentive travel, conferences and exhibitions — across five-star, ultra-luxury and integrated resort formats. Coverage includes event themes, meeting-size bands and booking modes. This analysis does not cover midscale or select-service business hotels, standalone convention centres without hotel inventory, pure leisure luxury transient demand, or corporate travel management software as a discrete market.
How big is the market for Luxury MICE Hotels Market?
Global luxury MICE hotel revenue is most defensibly sized near 104.6 Billion in 2025, rising to roughly 112.3 Billion in 2026 and 185 Billion by 2033 — a 7.4% CAGR that sits above the overall hotel market but below headline luxury-hospitality growth.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
104.6 Billion
2025
2033
7.4%
Global luxury hotel revenue, MICE-weighted
One published luxury-hotel analysis
9.8 Billion
2026
2033
5.6%
U.S.-only luxury MICE hotels
A competing U.S. estimate
1.37 Trillion
2026
2032
6.15%
Total global hotels, all tiers
A broad hotel-market analysis
Our analysis suggests the U.S.-only figure implies North America captures roughly one-third of global luxury MICE spend — internally consistent with the regional split. The lower 5.6% U.S. CAGR versus the 7.4% global rate implies Asia-Pacific and Middle East markets are pulling the global curve upward. Buyers should treat the global 7.4% as the planning anchor and the U.S. 5.6% as the mature-market floor.
How is the market segmented?
Segmentation is most useful when organized around what buyers actually transact — property tier, event type, meeting size, theme and booking channel — since each axis carries distinct pricing power.
Technology and digital-innovation events led theme share at 19.3% in 2025, while direct booking held 39.9% — evidence that planners still prize relationship-led contracting even as digital sourcing channels grow.
Which region leads in Luxury Mice Hotels Market?
North America leads the global luxury MICE hotels market at approximately 34% revenue share, supported by the deepest five-star meeting inventory and the world's largest corporate incentive budgets.
Luxury Mice Hotels Market Regional Market Share
Loading chart...
Luxury Mice Hotels Market Regional Market Share
Region
Market Share (%)
North America
0.34%
Europe
0.26%
Asia-Pacific
0.28%
South America
0.05%
Middle East & Africa
0.07%
Region
Share
North America
34%
Asia-Pacific
28%
Europe
26%
Middle East & Africa
7%
South America
5%
North America — USA, Canada, Mexico
USA dominates on incentive spend (~USD 5,400 per person) and convention inventory
Europe — Germany, UK, France, Italy, Spain, Switzerland
Strong on association conferences and heritage venues
Asia-Pacific — China, Japan, India, South Korea, Singapore, Australia
Fastest-growing, led by India (9.1% luxury CAGR) and Singapore (8.6%)
Middle East & Africa — UAE, Saudi Arabia, Turkey, South Africa
UAE at 8.1% — Gulf investment in ultra-luxury event infrastructure
South America — Brazil, Argentina, Colombia, Chile
Emerging; Argentina fastest at 8.2%
This divergence implies the competitive centre of gravity will drift toward Asia-Pacific and the Gulf by 2030, while North America remains the profit pool.
What is driving growth — and what is holding it back?
Growth is driven by restored corporate travel budgets, premium incentive spend and a structural shift toward experiential group events; the binding constraint is labour cost and availability in high-touch service roles.
Factor
Direction
Evidence strength
Mechanism
Incentive budget expansion
Driver
High
USD 4,900 average per-person spend; accommodation 27% of budget
Experiential venue shift
Driver
High
49% of NA planners used unique venues in 2025 vs 17% in 2023
Corporate travel recovery
Driver
High
Global business travel ~USD 1.47 trillion in 2024
AI-enabled planning
Driver
Medium
RFP automation, dynamic group pricing, demand forecasting
Labour shortages
Restraint
High
76% of U.S. hotels reported staffing shortages in 2024
Wage inflation
Restraint
High
U.S. hotel compensation USD 123 billion, up from 102 billion in 2019
The balance favours growth, but margin — not volume — is the contested ground. Our analysis suggests wage inflation outpaces achievable rate growth in mature markets, meaning incremental MICE revenue increasingly converts at lower profitability unless operators redesign service delivery.
Who are the leading vendors?
Competition is concentrated among five global chain operators, each leveraging loyalty ecosystems, global sales organisations and owned meeting inventory rather than competing on rate alone.
Company
Luxury/MICE positioning
Core moat
Marriott International
Broadest luxury portfolio; large group inventory
Loyalty scale and global sales network
Hilton Worldwide
Strong convention and corporate meeting presence
Brand breadth and mid-market-to-luxury ladder
Accor S.A.
Deep European and Asia-Pacific luxury footprint
Regional density and lifestyle brands
IHG Hotels & Resorts
Premium and luxury conversion pipeline
Loyalty programme and franchise reach
Hyatt Hotels
Meetings-focused luxury and resort assets
Group-service reputation and resort concentration
Differentiation is shifting toward experience design and data capability. Moats built on inventory are replicable; moats built on planner relationships, proprietary demand data and AI-assisted RFP turnaround are not — which is where the next competitive gap will open.
What do buyers and operators need to know?
Selection criteria have moved decisively beyond rate. Procurement teams should weight meeting-space flexibility, AV and hybrid capability, dedicated group-service staffing ratios, sustainability certification and F&B provenance — the factors that determine delegate satisfaction and repeat booking.
Procurement risk centres on labour-driven service variability: a property that cannot staff banquets consistently represents reputational exposure for the host brand. Contract on service-level commitments, not just space and rate. Switching costs are high once a multi-year programme is anchored to a venue, so buyers should negotiate multi-year rate holds and attrition flexibility upfront.
Regulatory compliance — data privacy for delegate manifests, accessibility standards, fire and occupancy codes, and emerging sustainability reporting — increasingly appears in corporate RFP scoring. Operators who cannot evidence compliance will be screened out before commercial negotiation begins.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours the growth case: corporate travel has exceeded 2019 nominal levels, incentive budgets are structurally higher, and planners are demonstrably trading rate sensitivity for experience. The strongest counter-argument is margin erosion — labour inflation is real, and a 7.4% revenue CAGR may mask flat or declining group profitability in mature Western markets. We nonetheless judge revenue growth the more reliable signal, because premium incentive demand is price-inelastic among top-tier corporate buyers.
Our second-order read: the divergence between the 5.6% U.S. and 7.4% global CAGR is not a data inconsistency but a signal of geographic rotation. Capital and sales investment should follow the curve — toward Gulf and Asia-Pacific ultra-luxury assets — while North American properties defend margin through experience monetisation and AI-driven RFP efficiency.
Actionable strategy:
Investors: Prioritise Gulf and Asia-Pacific ultra-luxury MICE assets where CAGR exceeds 8%, and underwrite on group-mix rather than transient occupancy.
Operators: Deploy AI across RFP response, group pricing and space allocation to offset wage inflation — target measurable sales-cycle compression within two booking seasons.
Buyers: Lock multi-year rate holds with attrition flexibility now, before experiential demand further strengthens vendor pricing power.
What would change our conclusion: a sustained decline in incentive per-person spend below USD 4,000, or staffing shortages persisting above 70% of hotels through 2027, would shift the outlook from growth to margin-defence.
Luxury Mice Hotels Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Luxury Mice Hotels Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.4% from 2020-2034
Segmentation
By Hotel
5-Star Luxury
Ultra-Luxury
Integrated Resorts
By Event
Meetings
Incentives
Conferences
Exhibitions
By Meeting Size
Under 100
100-499
500-999
1
000+
By Event Theme
Technology & Digital Innovation
Leadership & Strategy
Product Launch
Wellness & Retreat
By Booking Mode
Direct
Corporate Travel Agency
Third-Party Marketplace
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Switzerland
Asia Pacific
China
Japan
India
South Korea
Singapore
Australia
Latin America
Brazil
Argentina
Colombia
Chile
Middle East & Africa
UAE
Saudi Arabia
Turkey
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Hotel
5.1.1. 5-Star Luxury
5.1.2. Ultra-Luxury
5.1.3. Integrated Resorts
5.2. Market Analysis, Insights and Forecast - by Event
5.2.1. Meetings
5.2.2. Incentives
5.2.3. Conferences
5.2.4. Exhibitions
5.3. Market Analysis, Insights and Forecast - by Meeting Size
5.3.1. Under 100
5.3.2. 100-499
5.3.3. 500-999
5.3.4. 1
5.3.5. 000+
5.4. Market Analysis, Insights and Forecast - by Event Theme
5.4.1. Technology & Digital Innovation
5.4.2. Leadership & Strategy
5.4.3. Product Launch
5.4.4. Wellness & Retreat
5.5. Market Analysis, Insights and Forecast - by Booking Mode
5.5.1. Direct
5.5.2. Corporate Travel Agency
5.5.3. Third-Party Marketplace
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Hotel
6.1.1. 5-Star Luxury
6.1.2. Ultra-Luxury
6.1.3. Integrated Resorts
6.2. Market Analysis, Insights and Forecast - by Event
6.2.1. Meetings
6.2.2. Incentives
6.2.3. Conferences
6.2.4. Exhibitions
6.3. Market Analysis, Insights and Forecast - by Meeting Size
6.3.1. Under 100
6.3.2. 100-499
6.3.3. 500-999
6.3.4. 1
6.3.5. 000+
6.4. Market Analysis, Insights and Forecast - by Event Theme
6.4.1. Technology & Digital Innovation
6.4.2. Leadership & Strategy
6.4.3. Product Launch
6.4.4. Wellness & Retreat
6.5. Market Analysis, Insights and Forecast - by Booking Mode
6.5.1. Direct
6.5.2. Corporate Travel Agency
6.5.3. Third-Party Marketplace
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Hotel
7.1.1. 5-Star Luxury
7.1.2. Ultra-Luxury
7.1.3. Integrated Resorts
7.2. Market Analysis, Insights and Forecast - by Event
7.2.1. Meetings
7.2.2. Incentives
7.2.3. Conferences
7.2.4. Exhibitions
7.3. Market Analysis, Insights and Forecast - by Meeting Size
7.3.1. Under 100
7.3.2. 100-499
7.3.3. 500-999
7.3.4. 1
7.3.5. 000+
7.4. Market Analysis, Insights and Forecast - by Event Theme
7.4.1. Technology & Digital Innovation
7.4.2. Leadership & Strategy
7.4.3. Product Launch
7.4.4. Wellness & Retreat
7.5. Market Analysis, Insights and Forecast - by Booking Mode
7.5.1. Direct
7.5.2. Corporate Travel Agency
7.5.3. Third-Party Marketplace
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Hotel
8.1.1. 5-Star Luxury
8.1.2. Ultra-Luxury
8.1.3. Integrated Resorts
8.2. Market Analysis, Insights and Forecast - by Event
8.2.1. Meetings
8.2.2. Incentives
8.2.3. Conferences
8.2.4. Exhibitions
8.3. Market Analysis, Insights and Forecast - by Meeting Size
8.3.1. Under 100
8.3.2. 100-499
8.3.3. 500-999
8.3.4. 1
8.3.5. 000+
8.4. Market Analysis, Insights and Forecast - by Event Theme
8.4.1. Technology & Digital Innovation
8.4.2. Leadership & Strategy
8.4.3. Product Launch
8.4.4. Wellness & Retreat
8.5. Market Analysis, Insights and Forecast - by Booking Mode
8.5.1. Direct
8.5.2. Corporate Travel Agency
8.5.3. Third-Party Marketplace
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Hotel
9.1.1. 5-Star Luxury
9.1.2. Ultra-Luxury
9.1.3. Integrated Resorts
9.2. Market Analysis, Insights and Forecast - by Event
9.2.1. Meetings
9.2.2. Incentives
9.2.3. Conferences
9.2.4. Exhibitions
9.3. Market Analysis, Insights and Forecast - by Meeting Size
9.3.1. Under 100
9.3.2. 100-499
9.3.3. 500-999
9.3.4. 1
9.3.5. 000+
9.4. Market Analysis, Insights and Forecast - by Event Theme
9.4.1. Technology & Digital Innovation
9.4.2. Leadership & Strategy
9.4.3. Product Launch
9.4.4. Wellness & Retreat
9.5. Market Analysis, Insights and Forecast - by Booking Mode
9.5.1. Direct
9.5.2. Corporate Travel Agency
9.5.3. Third-Party Marketplace
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Hotel
10.1.1. 5-Star Luxury
10.1.2. Ultra-Luxury
10.1.3. Integrated Resorts
10.2. Market Analysis, Insights and Forecast - by Event
10.2.1. Meetings
10.2.2. Incentives
10.2.3. Conferences
10.2.4. Exhibitions
10.3. Market Analysis, Insights and Forecast - by Meeting Size
10.3.1. Under 100
10.3.2. 100-499
10.3.3. 500-999
10.3.4. 1
10.3.5. 000+
10.4. Market Analysis, Insights and Forecast - by Event Theme
10.4.1. Technology & Digital Innovation
10.4.2. Leadership & Strategy
10.4.3. Product Launch
10.4.4. Wellness & Retreat
10.5. Market Analysis, Insights and Forecast - by Booking Mode
10.5.1. Direct
10.5.2. Corporate Travel Agency
10.5.3. Third-Party Marketplace
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Luxury Mice Hotels Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Luxury Mice Hotels Market Revenue (Billion), by Hotel 2026 & 2034
Figure 3: North America Luxury Mice Hotels Market Revenue Share (%), by Hotel 2026 & 2034
Figure 4: North America Luxury Mice Hotels Market Revenue (Billion), by Event 2026 & 2034
Figure 5: North America Luxury Mice Hotels Market Revenue Share (%), by Event 2026 & 2034
Figure 6: North America Luxury Mice Hotels Market Revenue (Billion), by Meeting Size 2026 & 2034
Figure 7: North America Luxury Mice Hotels Market Revenue Share (%), by Meeting Size 2026 & 2034
Figure 8: North America Luxury Mice Hotels Market Revenue (Billion), by Event Theme 2026 & 2034
Figure 9: North America Luxury Mice Hotels Market Revenue Share (%), by Event Theme 2026 & 2034
Figure 10: North America Luxury Mice Hotels Market Revenue (Billion), by Booking Mode 2026 & 2034
Figure 11: North America Luxury Mice Hotels Market Revenue Share (%), by Booking Mode 2026 & 2034
Figure 12: North America Luxury Mice Hotels Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Luxury Mice Hotels Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Luxury Mice Hotels Market Revenue (Billion), by Hotel 2026 & 2034
Figure 15: Europe Luxury Mice Hotels Market Revenue Share (%), by Hotel 2026 & 2034
Figure 16: Europe Luxury Mice Hotels Market Revenue (Billion), by Event 2026 & 2034
List of Tables
Table 1: Luxury Mice Hotels Market Revenue Billion Forecast, by Hotel 2020 & 2034
Table 16: Europe Luxury Mice Hotels Market Revenue Billion Forecast, by Hotel 2020 & 2034
Frequently Asked Questions
1. How big is the luxury MICE hotels market?
The global luxury MICE hotels market was valued at approximately 104.6 Billion in 2025 and is projected to reach roughly 185 Billion by 2033, growing at a 7.4% CAGR over the forecast period.
2. Which region leads the luxury MICE hotels market?
North America leads with roughly 34% of global revenue, driven by the deepest five-star meeting inventory and the world's highest corporate incentive budgets. Asia-Pacific is the fastest-growing region.
3. What are the main drivers of luxury MICE hotel demand?
Restored corporate travel budgets, premium incentive spend averaging USD 4,900 per person, and a shift toward experiential venues — 49% of North American planners used unique venues in 2025 versus 17% in 2023.
4. What is restraining growth in the luxury MICE hotels market?
Persistent labour shortages and wage inflation. In 2024, 76% of surveyed U.S. hotels reported staffing shortages, and compensation reached USD 123 billion, squeezing group-service margins.
5. Which event type is largest in the luxury MICE hotels market?
Meetings account for the largest share at approximately 36.1% of U.S. segment revenue, followed by incentive programmes, which carry the highest per-person spend and strongest luxury attachment.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research follows a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the luxury hospitality value chain, including luxury hotel group commercial teams, independent ultra-luxury property operators, corporate event and destination-management agencies, meeting-space technology providers, and corporate procurement and travel buyers. Interviews targeted decision-makers holding VP of Group Sales, Head of MICE Commercial Operations, Director of Event Technology, and Corporate Travel Procurement Lead designations.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Group Sales & Commercial Operations Leads
38%
Hotel General Managers & Asset Directors
27%
Corporate Travel & Event Procurement
23%
Event Technology & Compliance Managers
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Luxury Hotel Group Operators
40%
Ultra-Luxury & Independent Properties
25%
Event & Destination Management Agencies
22%
Meeting Technology & Procurement Platforms
13%
Secondary Benchmarking & Public Trade Validation
Cross-validation draws on official multilateral and standards sources: UN Tourism arrival statistics, UN Comtrade hospitality service flows, WTO travel services data, U.S. Bureau of Economic Analysis travel exports, and corporate annual filings (10-K, SEC submissions, investor presentations) from listed hotel groups. Industry association data from the Global Business Travel Association, Events Industry Council, American Hotel & Lodging Association and World Travel & Tourism Council provide demand-side validation.
Demand Modeling & Market Sizing Triangulation
We apply simultaneous Top-Down modelling — allocating macroeconomic travel and business-event spend across hotel tiers — and Bottom-Up modelling using group room-night capacity, meeting-space inventory, average group rate and per-person incentive spend. Divergence between methods is reconciled against reported segment revenue before final sizing.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
Value in USD for base year
Bottom-up group room-night & revenue triangulation
 Luxury Mice Hotels Market