 Europe Swimming Sports Apparel Accessories Market
 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 220

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Europe Swimming Sports Apparel Accessories Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 9.660 B |
| 2025 | 9.970 B |
| 2026 | 10.29 B |
| 2027 | 10.62 B |
| 2028 | 10.96 B |
| 2029 | 11.31 B |
| 2030 | 11.67 B |

The Europe swimming sports apparel and accessories market covers performance and leisure swimwear — swimsuits, trunks, jammers, wetsuits, rash guards — plus goggles, caps, earplugs, training aids and swim-tracking devices sold across European countries. It serves competitive clubs, fitness lap swimmers, triathletes, open-water enthusiasts and holiday/recreational buyers.
This analysis covers apparel and accessories sold through supermarkets and hypermarkets, sporting goods retailers, online channels, exclusive brand outlets and other retail formats across Europe. It spans competitive, fitness and leisure end uses. This analysis does not cover non-swim water sports equipment such as surfboards, diving gear or boats, nor pool construction, water-treatment chemicals or aquatic facility management services.
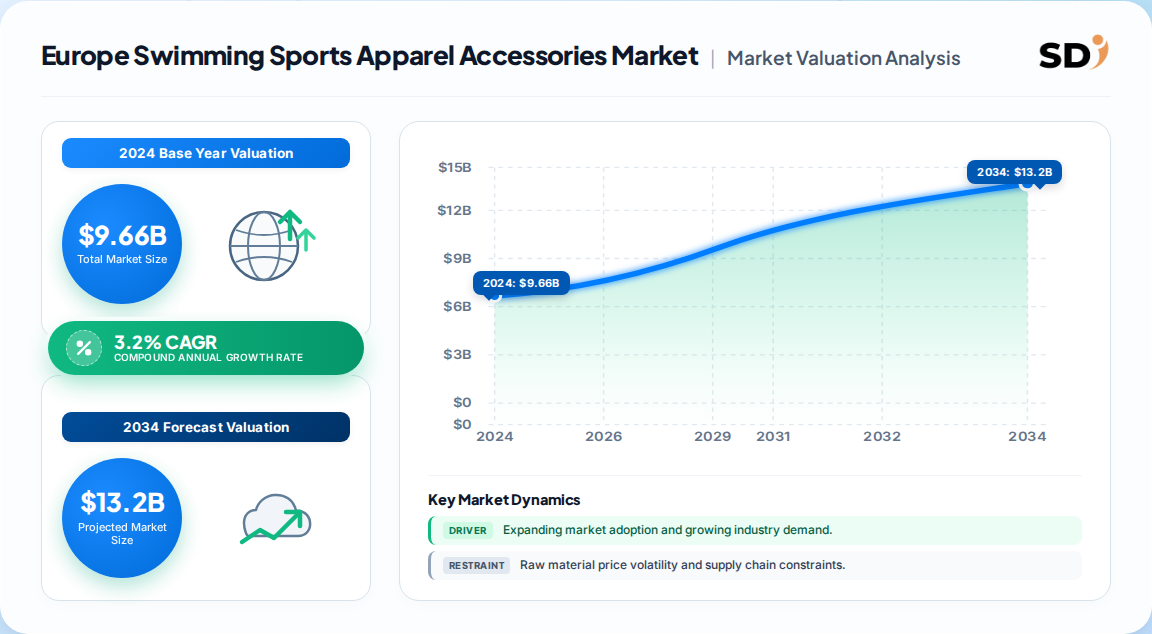
One published estimate puts the region at USD 9.66 billion in 2024, growing at 3.2% CAGR from 2025 to 2030. That figure is the most defensible regional baseline because it is anchored to European retail sell-through rather than global wholesale shipments.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 9.66 Billion | 2024 | 2025–2030 | 3.2% | Europe apparel + accessories, retail value | One published estimate |
| 31.6 Billion (global, 2025) | 2025 | 2025–2034 | 4.7% | Global swim gear incl. equipment, manufacturer value | Competing analysis |
| 12.17 Billion (global, 2024) | 2024 | 2024–2034 | 5.6% | Global swimwear, caps, goggles, all channels | Competing analysis |
| 729.4 Million (Spain, 2025) | 2025 | 2026–2033 | 4.63% | Spain apparel + accessories, retail value | Data-book publisher |
The apparent conflict between 3.2% and 4.7–5.6% global rates is a scope artefact, not a contradiction. Global figures bundle high-growth Asia-Pacific demand and manufacturer-level pricing; Europe is a mature, replacement-led region. Our analysis suggests the 3.2% regional rate is the correct planning anchor, with country-level upside concentrated in southern Europe — Spain alone is projected at 4.63% CAGR to 2033, and Italy is identified as the region's fastest-growing major market.
Trade data corroborates scale without contradicting it: EU imports of men's synthetic-fibre knit swimwear reached USD 95.1 million and 25.99 million units in 2024, led by China (USD 42.6M), Tunisia, Vietnam, Sri Lanka and Cambodia.
Segmentation runs on two axes: product category and distribution channel. Apparel is the revenue engine; channel mix is where competitive disruption is actually happening.
| Parent Segment | Children | 2024 Position |
|---|---|---|
| Category | Apparel; Accessories | Apparel >67.2% share; accessories 3.3% CAGR |
| Distribution Channel | Supermarkets & Hypermarkets; Sporting Goods Retailers; Online; Exclusive Brand Outlets; Others | Supermarkets 35.2% share |
| End Use (implied) | Competitive; Fitness; Leisure & Holiday | Competitive drives ASP; fitness drives volume |
Apparel's dominance is structural: swimsuits and trunks carry the highest ticket and strongest replacement cycle, while wetsuits and rash guards gained from triathlon and open-water participation. This divergence implies accessories — goggles, caps, training aids, swim-tracking wearables — is the better entry point for new entrants, since it is growing faster, is less brand-entrenched, and bundles naturally with apparel purchases.
Germany, the UK, France, Italy and Spain collectively drive the majority of regional revenue, with Italy flagged as the fastest-growing major market and the UK projected to remain the largest European country market through 2033.
Two demand regimes coexist. Northern Europe reports the highest swimmer participation rates globally, sustaining year-round indoor pool and club demand. Mediterranean markets layer seasonal tourism and holiday purchasing on top, creating sharper summer peaks. Our analysis suggests the northern club channel is the more defensible base for premium technical apparel, while southern markets reward mid-price, fashion-forward ranges with compressed selling windows.
Growth rests on entrenched swimming culture, rising health consciousness and sustainability-led premiumisation. Restraints are structural rather than cyclical: low regional growth, weather-dependent seasonality in the south, and input-cost volatility in recycled synthetics.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Health and low-impact fitness trend | Driver | High | Broadens participation across ages; lifts replacement frequency |
| Sustainability and recycled fabrics | Driver | High | Justifies premium price; brand switching toward eco-certified ranges |
| Fabric technology (chlorine resistance, UV, drag reduction) | Driver | High | Shortens replacement cycle; supports ASP uplift |
| Events and elite visibility | Driver | Medium | Olympics and European Championships lift aspirational demand |
| Mature regional demand | Restraint | High | 3.2% CAGR caps volume-led growth |
| Seasonality and climate dependency | Restraint | Medium | Concentrates revenue into Q2–Q3; stresses working capital |
| Import concentration and freight cost | Restraint | Medium | China supplies 45% of EU men's synthetic swimwear imports |
The balance favours incumbents with technical credibility. Sustainability is no longer differentiation — it is a qualifying criterion, and brands without traceable recycled content are being pushed into price competition. Simultaneously, import concentration in China creates a genuine supply-chain exposure that procurement teams have under-priced.
Speedo, Arena, Decathlon, Zoggs, TYR, adidas, Nike and Aquasphere anchor a fragmented field in which no single vendor holds dominant regional share.
| Company | HQ | Core strength | Strategic posture |
|---|---|---|---|
| Speedo | UK heritage, global | Performance swimwear, brand equity | Sustainability collaborations; lifestyle crossover |
| Arena | Italy | Competitive tech suits, athlete partnerships | Elite-to-mass technology transfer |
| Decathlon | France | Vertical retail, value pricing | Own-brand volume across channels |
| Zoggs | UK | Goggles, caps, eco ranges | Econyl-based Ecolast positioning |
| TYR Sport | USA | Triathlon and competitive | Official World Aquatics partnerships |
| adidas / Nike | Germany / USA | Mass athletic retail | Distribution breadth, seasonal swim lines |
The moats differ by tier. Arena and Speedo defend through elite competition credibility that cascades into retail. Decathlon's moat is cost and vertical control — it competes on access, not performance claims. Zoggs and Aquasphere occupy specialist accessory niches where technical specification matters more than fashion. This divergence implies acquisitions and licences will target accessory specialists and adaptive/inclusive swimwear, the two least consolidated pockets.
Selection criteria differ sharply by buyer type. Club and team procurement prioritises chlorine durability, consistent sizing and World Aquatics-approved competition compliance; retailers prioritise sell-through velocity, size-curve breadth and margin protection. The most under-managed risk is specification drift: fabric durability claims vary widely, and buyers relying on certification alone are exposed to mid-season returns.
Switching costs are low for leisure buyers and high for competitive teams locked into tech-suit fit and athlete familiarity. Regulatory exposure centres on textile labelling, chemical restrictions on dyes and finishes, and green-claims substantiation under EU consumer-protection rules — an area where recycled-content marketing is drawing increasing scrutiny. Online channel partners additionally face sizing-return economics that erode margin on low-ticket accessories.
The balance of evidence favours a selective-growth strategy, not a volume strategy. Europe's 3.2% CAGR is real but modest, and the profit pools are concentrating in sustainability-certified apparel and technically differentiated accessories. Vendors treating the region as a homogeneous market will over-invest in seasonal fashion and under-invest in the club and fitness channels that deliver predictable recurrence.
The strongest counter-argument is that sustainability premiumisation is saturating — recycled content is now table stakes, and several national markets show price sensitivity rising faster than eco-willingness to pay. That argument has merit, but it describes commoditisation of the claim, not of the product: chlorine-resistance and fit engineering remain genuinely defensible, and the Spain and Italy growth differentials suggest southern Europe still rewards premium innovation.
Actionable strategy:
What would change our conclusion: a sustained move above 4% regional CAGR — most plausibly driven by adaptive and inclusive swimwear scaling faster than expected — would shift the recommendation from selective growth toward aggressive capacity expansion.
| Region | Market Share (%) |
|---|---|
| Germany | 0.19% |
| United Kingdom | 0.18% |
| France | 0.14% |
| Italy | 0.13% |
| Spain | 0.11% |
| Netherlands & Nordics | 0.12% |
| Rest of Europe | 0.13% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.2% from 2020-2034 |
| Segmentation |
|
It was estimated at USD 9.66 billion in 2024. One published forecast projects 3.2% CAGR from 2025 to 2030, implying roughly 11.7 billion by 2030.
Apparel held over 67% of revenue in 2024, led by swimsuits and trunks. Accessories is smaller but faster-growing at 3.3% CAGR, driven by goggles, caps and training aids.
Italy is identified as the fastest-growing major European market. Spain is projected at 4.63% CAGR to reach USD 1,046.2 million by 2033, while the UK remains the largest.
Supply concentration. China accounted for roughly 45% of EU men's synthetic-fibre swimwear import value in 2024, exposing buyers to freight, tariff and currency volatility.
It is now a qualifying criterion rather than an advantage. Recycled fabrics are widely adopted, so differentiation is shifting to durability engineering, fit and inclusive design.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our 70/30 primary-to-secondary research split anchors this study in verified operator experience. Fieldwork comprised in-depth interviews across the swimwear value chain: technical textile and recycled-yarn suppliers, specialist swimwear manufacturers, contract production partners in North Africa and Southern Europe, and pan-European sporting goods distributors. Within these organisations we engaged decision-makers holding designated responsibility for category strategy — VP-level Sourcing, Heads of Product Development and Fabric R&D, Technical Directors overseeing competition-standard compliance, and Commercial Operations Leads managing retail channel mix.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Directors | 35% |
| Product Development & Fabric R&D Heads | 35% |
| Technical & Compliance Directors | 30% |
| Company Type | Representation (%) |
|---|---|
| Swimwear Manufacturers & Contract Producers | 40% |
| Technical Fabric & Yarn Suppliers | 30% |
| Distributors & Sporting Goods Retailers | 30% |
All demand estimates were cross-checked against official multilateral trade statistics, principally UN Comtrade and Eurostat HS6 swimwear classifications (611231, 611241, 611249), alongside WTO tariff schedules, national customs releases and corporate annual filings for listed sportswear manufacturers. Patent filings covering chlorine-resistant fibres, UV-responsive textiles and drag-reduction constructions were reviewed to date technology transitions, and published standards from technical bodies informed compliance assessment.
We ran simultaneous top-down and bottom-up models. The top-down approach allocated European sportswear and aquatic-participation spend to swim categories using retail channel and participation data. The bottom-up approach modelled manufacturer revenue, unit volumes and channel mark-ups by country. Divergence between the two constrained the reported range.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |