 Sports Apparel Market
 Size, Growth & Forecast to 2033
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 210

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Sports Apparel Market
Vijayashree Ugale
Research Analyst

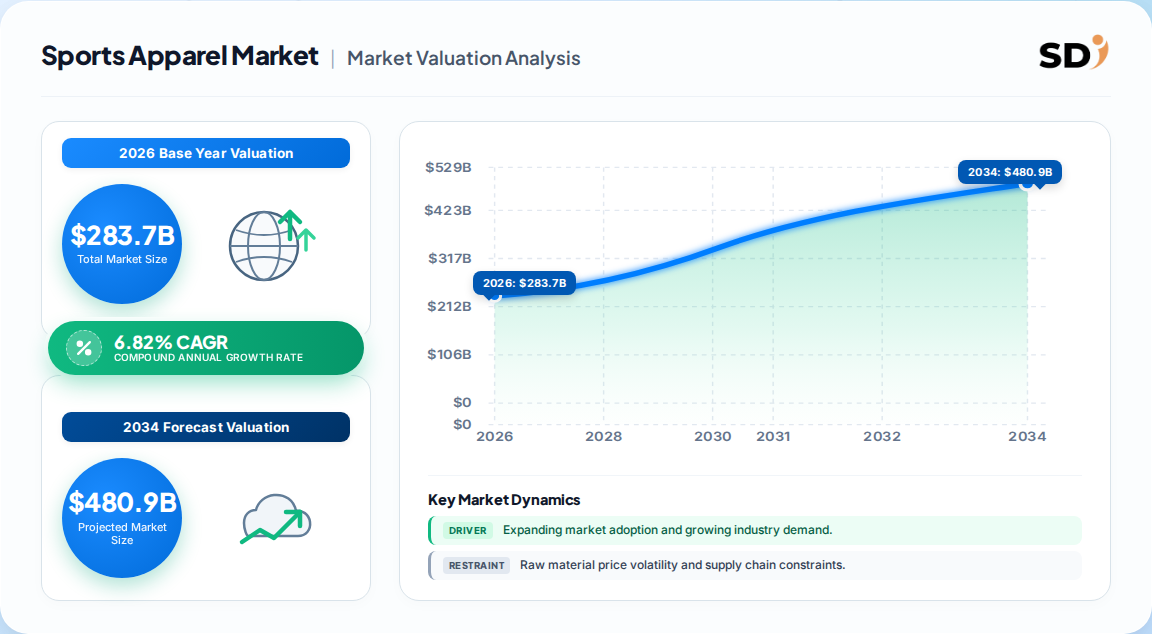
| Year | Market Size |
|---|---|
| 2026 | 283.7 B |
| 2027 | 304.0 B |
| 2028 | 324.7 B |
| 2029 | 346.8 B |
| 2030 | 370.5 B |
| 2031 | 395.7 B |
| 2032 | 422.8 B |

Sports apparel is purpose-built and athleisure clothing for athletic activity and active lifestyles, spanning tops, bottoms, outerwear and accessories engineered for movement, moisture management and durability. It excludes athletic footwear and hard sporting goods, though most published estimates bundle footwear into a broader sportswear definition.
This report covers the global sports apparel market by product type, sport type, end user and distribution channel, with regional coverage of North America, Europe, Asia-Pacific, South America and Middle East & Africa. This analysis does not cover athletic footwear, hard sporting goods, fitness equipment or wearable electronics, which are tracked as adjacent categories.
Published estimates diverge by more than USD 130 billion because definitions differ. The most defensible planning base is the narrower apparel-only figure near USD 304 billion for 2027, because it isolates garments from footwear, which alone represents roughly 64% of broad sportswear value.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 304 Billion | 2027 | 2032 | 6.82% | Apparel only: top, bottom, outerwear; excludes footwear | One published estimate |
| USD 437.4 Billion | 2026 | 2033 | 10.7% | Broad sportswear: footwear plus apparel | A competing analysis |
| USD 213.31 Billion | 2024 | 2032 | 5.53% | Apparel only, sport-segmented, print-inclusive | Another published estimate |
| USD 283.7 Billion | 2026 | 2032 | 6.82% | Apparel only, base-year entry point | One published estimate |
Our analysis suggests the 5.53% and 10.7% CAGRs bracket the plausible range: the lower figure reflects mature-market replacement demand, while the higher figure is inflated by footwear inclusion and emerging-market digital penetration. For procurement and capacity planning, the 6.8% apparel-only trajectory is the safer anchor.
Segmentation matters because growth is highly uneven across product, sport and channel. Outer wear and children's lines outgrow the headline, while offline retail retains volume leadership despite losing share to online.
| Parent | Children | 2026 share | Fastest-growing child |
|---|---|---|---|
| Product type | Top wear, bottom wear, outer wear, accessories | Top wear 36.48% | Outer wear, 7.1% CAGR |
| Sport type | Running, soccer, basketball, training, others | Running 37.67% | Running, 7.5% CAGR |
| End user | Men, women, children | Men 58.23% | Children, 7.9% CAGR |
| Distribution | Offline retail, online retail | Offline 64.84% | Online, 8.3% CAGR |
North America leads with 48.47% of apparel-only value in 2026, though its share is structurally eroding as Middle East & Africa (8.8% CAGR) and Asia-Pacific scale fastest. The regional tree below reflects the reporting hierarchy used in this analysis.
| Region | Market Share (%) |
|---|---|
| North America | 0.33% |
| Europe | 0.24% |
| Asia-Pacific | 0.3% |
| South America | 0.06% |
| Middle East & Africa | 0.07% |
The Middle East & Africa growth premium is partly a low-base effect, but government sports-culture initiatives and retail formalization give it durability. Europe's trajectory is shaped less by volume than by regulation: EU extra-EU sporting goods imports rose 16.3% between 2020 and 2025, with China supplying over 40% of value — a concentration risk for European buyers.
Women's sports participation is the highest-impact driver at +2.4% CAGR, followed by brand marketing spend (+2.1%) and social/celebrity influence (+1.8%). Counterfeits (-1.2%) and fragmented regulation (-0.9%) are the material drags — both disproportionately affecting cross-border sellers.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Women's sports participation | +2.4% CAGR | Strong (US tennis +10%, Football Australia +4%) | Broadens functional range needs |
| Brand marketing spend | +2.1% CAGR | Strong (Nike demand creation USD 4.75B) | Builds consideration and pricing power |
| Social media and celebrity | +1.8% CAGR | Moderate | Converts attention into product discovery |
| Government sports policy | +1.6% CAGR | Moderate (India INR 364.4B outlay) | Expands participation infrastructure |
| Fabric technology | +1.0% CAGR | Moderate | Supports premium price realization |
| Athleisure adoption | +0.9% CAGR | Strong | Extends wear occasions beyond sport |
| Counterfeit proliferation | -1.2% CAGR | Strong (UK-centric) | Diverts volume, erodes brand equity |
| Regulatory fragmentation | -0.9% CAGR | Moderate (EU) | Raises compliance cost per SKU |
The balance favors growth: drivers sum to roughly +9.8% versus restraints at -2.1%, implying net mid-single-digit real expansion once pricing and base effects are stripped out. The key second-order effect is that regulatory and counterfeit drags are channel-specific — they hit online cross-border sellers hardest, which is precisely where the fastest growth (8.3%) sits. That tension, not demand, is the binding constraint.
Nike, Adidas, Puma, Lululemon and New Balance lead a medium-concentration market where scale in marketing and fabric IP is the primary moat. Differentiation increasingly rests on activity-specific ranges and localized collections rather than broad lifestyle portfolios.
| Company | HQ | Core strength | Strategic posture |
|---|---|---|---|
| Nike Inc. | USA | Brand scale, USD 4.75B demand creation | Premium performance plus lifestyle |
| Adidas Group | Germany | Football/club licensing, localized activations | Club-led merchandise expansion |
| Puma SE | Germany | Speed-to-market, football and running | Mid-premium challenger |
| Lululemon Athletica | Canada | Women's premium, community retail | DTC-led, high margin |
| New Balance Athletics | USA | Fit breadth, running credibility | Performance-first |
| V.F. Corporation | USA | Outdoor and lifestyle portfolio | Multi-brand outdoor |
Our analysis suggests the moat is shifting from sponsorship inventory to fabric engineering and direct consumer data. Club-linked merchandise — Adidas' Liverpool kit launch being the club's most successful ever — shows licensed local relevance can outperform global campaigns in conversion.
Procurement decisions now hinge on three mission-critical criteria: verified fabric performance claims, compliance readiness for destination-specific labeling and origin rules, and counterfeit-resistant distribution design. The Colombian manufacturer case illustrates the pattern — export-ready capacity exists, but EU entry requires work on textile compliance, traceability and rules of origin before commercial scaling.
Switching costs are moderate for commodity basics but high for technical outerwear, where supplier certification and tooling amortization lock buyers in. Operators should treat online channel expansion cautiously: it is the fastest-growing channel (8.3%) but also where counterfeit (-1.2%) and regulatory (-0.9%) drags concentrate. Dual-sourcing across EU and non-EU origins mitigates the China concentration risk in European imports.
The balance of evidence favors the apparel-only, mid-single-digit growth thesis (6.8% CAGR) over the double-digit broad-sportswear narrative. The higher figure is not wrong — it is measuring footwear. Buyers who conflate the two will over-forecast garment demand by roughly a third and over-commit capacity. The strongest counter-argument is that athleisure has permanently blurred the apparel/footwear boundary at retail, making scope separation commercially artificial; we accept the point but note that sourcing, tooling and compliance remain distinct, so the separation holds operationally.
Second, growth is migrating from volume leaders to niche winners: outer wear, children's, running and online each outpace the headline. This implies a barbell strategy — defend top-wear volume with cost discipline while funding outerwear premiumization and children's assortment depth. Middle East & Africa's 8.8% growth is real but low-base; treat it as an option, not a pillar.
Actionable strategy:
What would change our conclusion: a sustained shift in women's participation or a harmonized EU textile regulation would move the CAGR toward the high single digits and justify re-basing forecasts upward. Absent that, the 6.8% anchor stands — and the full report quantifies the sub-segment variance that aggregate figures conceal.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.82% from 2020-2034 |
| Segmentation |
|
The apparel-only market was valued near USD 283.7 billion in 2026 and USD 304 billion in 2027, reaching USD 422.8 billion by 2032 at a 6.82% CAGR. Broader sportswear estimates including footwear run materially higher.
Outer wear is the fastest-growing product type at 7.1% CAGR, while running leads sport types at 7.5% and children are the fastest-growing end user at 7.9% CAGR through 2032.
North America leads with 48.47% of apparel-only value in 2026, though Middle East & Africa is forecast to grow fastest at 8.8% CAGR and Asia-Pacific scales on digital penetration.
Nike, Adidas, Puma, Lululemon and New Balance lead a medium-concentration market, competing on brand marketing scale, fabric technology and activity-specific range depth.
Definitions differ: broad sportswear estimates include footwear, which is roughly 64% of value, while apparel-only estimates isolate garments. Reconciling scope before planning is essential to avoid mis-sizing demand by over USD 130 billion.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain with raw material and technical fabric suppliers, specialized apparel manufacturers, contract manufacturing formulators, and global distributors and retail operators. Decision-maker designations interviewed include VP of Sourcing, Heads of Product R&D, Technical Directors, and Commercial Operations Leads, ensuring both demand-side and supply-side perspectives inform every estimate.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Product R&D & Technical Directors | 40% |
| Commercial Operations & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Technical Fabric & Material Suppliers | 40% |
| Apparel Manufacturers & Contract Producers | 35% |
| Distributors & Retail Operators | 25% |
Findings are benchmarked against official multilateral trade databases (UN Comtrade, WTO, Eurostat, US ITC), corporate annual filings and investor presentations (10-K, SEC filings), patent databases for fabric technology, and recognized non-profit technical standards and industry associations. Public trade flows — including EU extra-EU sporting goods imports and export values — are used to validate demand estimates at country level.
We apply simultaneous Top-Down modeling (macroeconomic activity, segment allocation, per-capita participation) and Bottom-Up modeling (manufacturer capacity, product pricing, end-use consumption). Divergences between the two are reconciled through weighted triangulation, with apparel-only and footwear-inclusive scopes kept separate to preserve definitional integrity.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |