 Snow Sports Apparel Market
 Size, Forecast & Trends 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 217

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Snow Sports Apparel Market
Vijayashree Ugale
Research Analyst

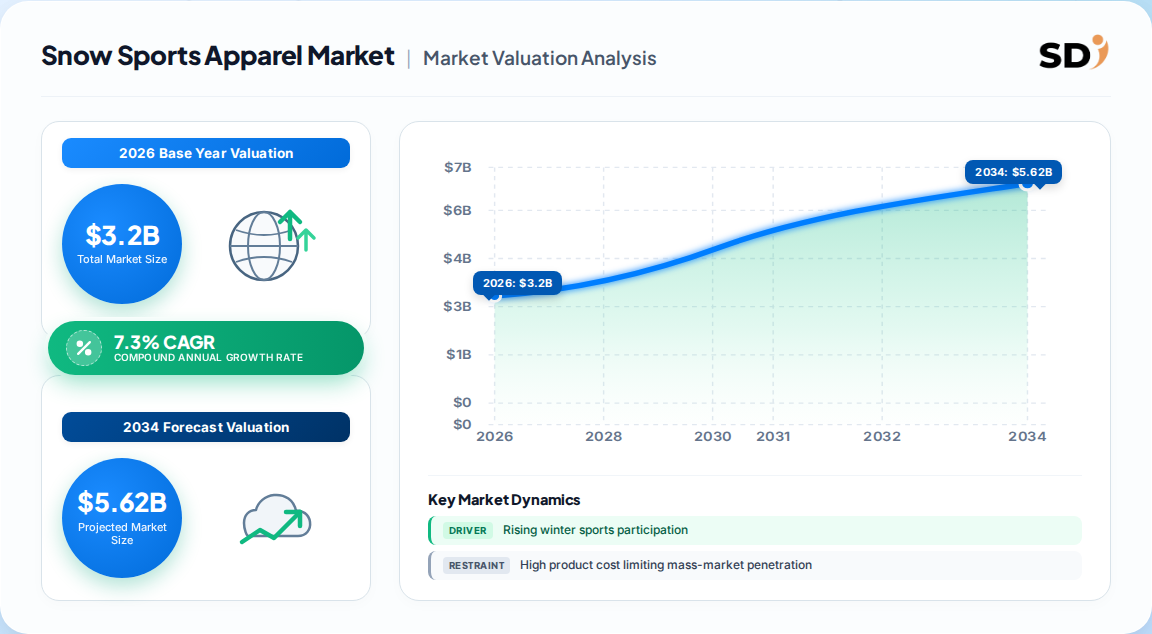
| Year | Market Size |
|---|---|
| 2025 | 3.000 B |
| 2026 | 3.200 B |
| 2027 | 3.400 B |
| 2028 | 3.700 B |
| 2029 | 4.000 B |
| 2030 | 4.200 B |
| 2031 | 4.600 B |

The Snow Sports Apparel market covers specialized clothing engineered for skiing, snowboarding, alpine touring, snowshoeing and related winter activities — including technical jackets, shells, insulated mid-layers, base layers, snow pants, suits and accessories such as gloves, helmets, goggles and socks. Products prioritize waterproofing, breathability, thermal regulation and durability in extreme weather.
This analysis covers the global Snow Sports Apparel market across product (top apparel, bottom apparel, accessories), application (men, women, kids), distribution channel (offline, online) and price tier (economy through super-premium). It includes apparel and soft accessories only. This analysis does not cover hard goods such as skis, snowboards, bindings, boots or protective equipment, nor general winter fashion or everyday cold-weather clothing.
Estimates vary widely — from roughly USD 1.6 billion to USD 18.2 billion — because published studies differ fundamentally in scope, channel coverage and terminology. Our consensus reading anchors on the mid-range apparel-only figure.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 3.2 Billion | 2026 | 2033 | 7.3% | Apparel-only, global, all channels | One published estimate |
| USD 1.6 Billion | 2025 | 2032 | 2.2% | Apparel-only, narrower channel definition | A competing analysis |
| USD 18.2 Billion | 2023 | 2033 | 11.2% | Broad snow apparel incl. casual winter wear | A competing analysis |
| USD 3.1 Billion | 2025 | 2035 | 7.4% | Apparel-only, aligned to GVR scope | A competing analysis |
| +USD 1.63 Billion opportunity | 2023 | 2028 | 6.07% | Apparel-only, global | A competing analysis |
Our analysis suggests the USD 3.0–3.2 billion 2025–2026 consensus is the most defensible for pure snow sports apparel, given three independent estimates cluster within a 5% band. The USD 18.2 billion figure almost certainly inflates scope by including general winter clothing and casual outerwear. The 2.2% CAGR likely underweights technical innovation and premiumization — making the ~7.3% consensus the more credible planning base.
The market is segmented primarily by product, application and distribution channel — with accessories the fastest-growing product type and women's apparel the fastest-growing application.
| Parent Segment | Children | Largest Share | Fastest Growth |
|---|---|---|---|
| Product | Top Apparel, Bottom Apparel, Accessories | Top Apparel (~59%) | Accessories |
| Application | Men, Women, Kids | Men (~62%) | Women |
| Distribution Channel | Offline, Online | Offline (~60%) | Online |
| Price Tier | Economy, Mid-Range, Premium, Super-Premium | Mid-Range | Premium |
Implication for buyers: Accessories — helmets, goggles, gloves, face masks — are the highest-velocity innovation pocket, while women's lines represent the under-served growth frontier. Portfolio strategy that leans into these two segments captures disproportionate share of incremental value.
North America leads the global Snow Sports Apparel market with roughly 38.5% revenue share, driven by deep ski resort infrastructure, high participation rates and strong premium brand presence across the U.S. and Canada.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.31% |
| Asia-Pacific | 0.22% |
| South America | 0.05% |
| Middle East & Africa | 0.04% |
Geography structure:
| Region | 2025 Share | Growth Outlook |
|---|---|---|
| North America | 38.5% | Moderate, premium-led |
| Europe | 31.0% | Stable, value-driven |
| Asia-Pacific | 22.0% | Fastest CAGR |
| Latin America | 4.5% | Emerging |
| Middle East & Africa | 4.0% | Niche |
Asia-Pacific is the prize for long-horizon positioning — China's winter sports policy push and Japan's premium destination status create a compounding demand pool, even if current share remains modest. Investors underweighting APAC will miss the highest-growth structural margin pool of the next decade.
Growth is powered by rising winter sports participation and technical fabric innovation, while high price points and weather variability restrain broader adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising winter sports participation | Driver | High | 29.9M Americans engaged in winter activities; 11.6M active skiers/snowboarders |
| Technical fabric innovation | Driver | High | Waterproof, breathable, lightweight, PFAS-free advances |
| Winter tourism & resort expansion | Driver | High | China resort build-out; global ski tourism recovery |
| Sustainability demand | Driver | Medium-High | Recycled fibers, PFAS-free finishes, circular manufacturing |
| Omnichannel & D2C expansion | Driver | Medium-High | Brands reach premium consumers directly |
| High product cost | Restraint | Medium | Premium price points limit mass-market penetration |
| Weather variability | Restraint | Medium | Snowfall uncertainty affects seasonal demand |
| Supply chain complexity | Restraint | Medium | China concentration (~50% of production) creates risk |
The balance favors growth. Drivers are structural and multi-year — participation, tourism and innovation — while restraints are cyclical and manageable. The sustainability shift is the single biggest realignment: it converts compliance pressure into a differentiation lever for brands that move early.
The competitive landscape is fragmented across technical specialists, outdoor conglomerates and mass-market sportswear brands — with The North Face, Columbia and Amer Sports anchoring the premium tier.
| Company | Headquarters | Key Brands / Position | Differentiation |
|---|---|---|---|
| VF Corporation | USA | The North Face, Futurelight/DryVent tech | Premium technical outerwear leadership |
| Columbia Sportswear | USA | Columbia, Mountain Hardwear | Broad price-tier coverage |
| Amer Sports | Finland | Arc'teryx, Atomic, Salomon | Premium performance + gear adjacency |
| Kering | France | Kering outdoor brands | Luxury-technical crossover |
| Adidas AG | Germany | Adidas outdoor lines | Global brand equity |
| Descente Ltd. | Japan | Descente, ski racing heritage | Japanese technical credibility |
| Decathlon SA | France | Wedze, in-house value | Mass affordability |
| Goldwin Inc. | Japan | Goldwin, The North Face Japan licensee | Japan market stronghold |
| Burton | USA | Burton Snowboards | Snowboard culture authenticity |
| Norrona | Norway | Norrona | Premium Scandinavian technical |
| Helly Hansen | Norway | Helly Hansen | Maritime-heritage technical |
| Rossignol | France | Rossignol apparel | Ski brand halo |
Competitive moats center on material technology IP (Futurelight, DryVent), athlete sponsorship, resort-retail relationships and sustainability credentials. Pure brand marketing is a shrinking differentiator — buyers increasingly verify fabric performance claims, and D2C data advantages give incumbents compounding insight into consumer preference.
For procurement and category managers, selection criteria are shifting from brand prestige toward verifiable technical performance and sustainability documentation. Mission-critical factors include waterproof/breathability ratings (e.g., 20K/20K), thermal rating transparency, and PFAS-free certification — increasingly required by European regulators.
Procurement risks cluster in supply chain concentration: roughly half of global production sits in China, creating tariff and geopolitical exposure. Dual-sourcing across Vietnam, Bangladesh and Eastern Europe is now a strategic imperative, not a cost lever.
Switching costs are moderate for buyers (multi-year brand contracts, sponsored athlete alignment) but high for operators (tooling, fabric sourcing relationships, certification). Regulatory compliance — EU PFAS restrictions, textile labelling, extended producer responsibility — is becoming a gatekeeping capability. Buyers should demand full material traceability from vendors before committing to multi-season agreements.
The balance of evidence favors premiumization anchored in verified technical and sustainability performance. The market is not expanding through volume — participation is growing modestly — but through value per unit as consumers trade up to certified, high-performance technical apparel. Brands that compete on price alone face structural margin compression.
The strongest counter-argument is that premium pricing will cap the mass-market opportunity, and that mid-tier brands like Decathlon and Columbia will capture disproportionate volume as emerging-market participation grows. This is a real risk, but it is a volume story, not a value story — and the value pool is where strategic margins lie.
Our analysis suggests three strategic priorities for 2026–2033:
What would change our conclusion: a meaningful slowdown in Asia-Pacific resort development, or a sustained multi-season decline in Western participation rates, would push the market toward the lower CAGR band and favor value brands over premium players.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.3% from 2020-2034 |
| Segmentation |
|
The global Snow Sports Apparel market was valued at approximately USD 3.0 billion in 2025 and is estimated at USD 3.2 billion in 2026, with a projected reach of USD 5.3 billion by 2033 at a 7.3% CAGR.
North America leads with roughly 38.5% revenue share in 2025, supported by high skiing and snowboarding participation, extensive resort infrastructure and strong premium brand presence across the U.S. and Canada.
Accessories (helmets, gloves, goggles, socks) is the fastest-growing product segment, while women's apparel is the fastest-growing application segment as female participation and premium sportswear demand rise.
Key players include VF Corporation (The North Face), Columbia Sportswear, Amer Sports (Arc'teryx, Salomon), Kering, Adidas, Descente, Decathlon, Goldwin, Burton, Norrona and Helly Hansen.
Rising winter sports participation, expanding ski resort infrastructure, winter tourism growth, technical fabric innovation, sustainability demand and omnichannel/D2C expansion are the primary growth drivers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews across the value chain — raw material suppliers (technical fabric and membrane producers), specialized apparel manufacturers, contract formulators (finishing and DWR treatment specialists), and global distributors — targeting decision-makers including VP of Sourcing, Heads of Product R&D, Technical Directors and Commercial Operations Leads. Interviews focused on capacity, pricing, PFAS-free transition timelines and channel dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 35% |
| Heads of Product R&D | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Technical Fabric & Membrane Producers | 40% |
| Specialized Apparel Manufacturers | 30% |
| Finishing & DWR Treatment Specialists | 18% |
| Global Distributors & Retailers | 12% |
We triangulated against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat) for cross-border apparel flows, corporate annual filings (10-K, SEC filings, investor presentations) from listed players, patent databases for technical fabric IP, and recognized technical standards bodies and industry associations.
We ran simultaneous Top-Down (macroeconomic sizing, segment allocation) and Bottom-Up (manufacturer capacity, unit pricing, end-use consumption) models, reconciling divergent estimates to a consensus planning base.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |