 J Beauty Products Market
 Size, Share & Forecast to 2033
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 222

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 J Beauty Products Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 37.20 B |
| 2026 | 39.00 B |
| 2027 | 41.50 B |
| 2028 | 44.10 B |
| 2029 | 46.90 B |
| 2030 | 49.80 B |
| 2031 | 53.00 B |

The J Beauty Products Market covers Japanese-origin skincare, haircare, color cosmetics and body care built on minimalist, preventive, multi-step routines. It emphasizes gentle formulations, fermentation science and traditional ingredients such as rice bran, green tea and camellia oil, positioned around long-term skin health rather than corrective treatment.
This analysis covers finished J-Beauty skincare, haircare, color cosmetics, fragrance and bath-and-body products sold through retail, pharmacy, specialty and e-commerce channels worldwide. Both conventional and organic formulations are included across mass, mid and prestige price tiers. This analysis does not cover professional salon-only treatments, aesthetic injectables, beauty devices, oral care, or K-Beauty and Western indie brands positioned outside Japanese formulation heritage.
Estimates diverge sharply on absolute size and growth, largely because publishers define J-Beauty differently — some count only Japanese-branded exports, others fold in Japan-domestic consumption and licensee production. The table below reconciles the leading published figures.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 37.2 Billion → 59.8 Billion | 2025 | 2033 | 6.3% | Broad global J-Beauty finished goods, all channels | One published estimate |
| 32.1 Billion → 44.3 Billion | 2023 | 2033 | 3.27% | Conventional + organic, narrower channel set | A competing analysis |
| 8.4 Billion → 15.3 Billion | 2025 | 2033 | 6.9% | Japanese-brand product only, ex-licensee output | A narrower-scope estimate |
Our analysis favors the 37.2 Billion (2025) baseline and 6.3% trajectory as most defensible. It aligns with observed cross-border e-commerce expansion, travel-retail recovery and the preventive-skincare shift, while the 3.27% figure appears anchored to pre-2023 channel data. The 8.4 Billion reading is credible only under a strict brand-origin definition. Buyers should expect true global spend to sit between 37 and 45 Billion for 2025 depending on licensee inclusion.
Segmentation follows product, formulation type, price tier, gender and channel. Skincare is the anchor category and the fastest-growing; mass pricing and pharmacy distribution reflect the market's accessible-premium character rather than pure luxury positioning.
| Parent segment | Children | 2025 share |
|---|---|---|
| Product | Skincare, Haircare, Color Cosmetics, Fragrance, Bath & Body | Skincare 48.9% |
| Type | Conventional, Organic | Conventional 73.5% |
| Price tier | Mass, Mid, Prestige | Mass 62.8% |
| Gender | Women, Men, Unisex | Women 78.0% |
| Distribution | Pharmacies & Drugstores, Specialty Stores, E-commerce, Hypermarkets, Others | Pharmacies 40.5% |
Skincare's dominance is structural: essence, lotion and sunscreen formats map directly onto the minimalist routine that defines J-Beauty's global appeal. Haircare (~21%) and makeup (~16%) are stable repeat-purchase categories, while fragrance and bath-and-body are smaller but benefit from gifting and wellness positioning.
Asia Pacific leads with 60.8% of 2025 global revenue, driven by Japan's brand-origin dominance and rising cross-border demand from China, South Korea and Southeast Asia. North America and Europe follow as premium-import markets.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.61% |
| North America | 0.16% |
| Europe | 0.11% |
| Middle East & Africa | 0.07% |
| Latin America | 0.05% |
Japan alone represents roughly 28% of global value, and the U.S. contributes about 9.7% under a narrower origin definition — underscoring how much depends on whether licensee production is counted.
The primary growth driver is the global shift toward preventive, minimalist skincare that prioritizes barrier health, hydration and UV protection over multi-step corrective routines. This is reinforced by e-commerce access and ingredient-led social content.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Preventive skincare shift | Growth | High | Fewer, higher-efficacy daily products |
| Traditional ingredient appeal | Growth | High | Rice bran, green tea, fermentation trust |
| Cross-border e-commerce | Growth | High | Direct overseas access, lower entry cost |
| Anti-aging as prevention | Growth | Medium | Younger buyers invest earlier |
| Limited digital marketing | Restraint | Medium | Slower trend adoption vs K-Beauty |
| Global prestige competition | Restraint | High | Dermocosmetic and Western pressure |
Our analysis suggests the restraint side is underweighted by most forecasts. J-Beauty's slower social-media cadence and conservative brand storytelling limit younger-consumer capture against aggressive K-Beauty and Western dermobrands. The net effect: volume growth is steady but share-defense requires digital investment, not just formulation quality.
The market is moderately concentrated in Japan but fragmented globally. Shiseido leads on brand equity and distribution reach; Kao leverages household penetration; POLA and Kosé balance premium and mass; DHC anchors direct-sales value.
| Company | Position | Key strength |
|---|---|---|
| Shiseido | Market leader | Brand equity, broad skincare portfolio, global reach |
| Kao | Major player | Household penetration, trusted skin and hair brands |
| Kosé | Major player | Balanced mass and premium portfolio |
| POLA Orbis | Premium specialist | Anti-aging positioning, loyal base |
| DHC | Value / direct sales | Broad catalog, DTC recognition |
| Mandom | Mass / men's grooming | Everyday beauty reach |
| FANCL | Preservative-free niche | Additive-free formulation trust |
Competitive moats rest on formulation IP, ingredient provenance and routine-based brand education. Emerging players compete on minimalist positioning and refill sustainability, but scale and trust remain decisive advantages for incumbents in pharmacy and premium channels.
Procurement decisions hinge on formulation stability, ingredient provenance and certification continuity more than headline price. J-Beauty's value proposition is trust — buyers should verify rice-bran, fermentation and camellia-oil sourcing claims against supplier documentation, since authenticity underpins the entire premium narrative.
Switching costs are moderate to high. Regulatory divergence across markets (ingredient labeling, UV-filter approvals, quasi-drug classifications in Japan versus cosmetic status elsewhere) creates re-registration burden that locks in established suppliers. Buyers entering cross-border channels should prioritize vendors with localized fulfillment and compliant dossiers, as delivery speed and label accuracy now drive repeat purchase as much as formulation quality. Refill and sustainable-packaging formats are becoming a procurement differentiator, not a niche add-on.
The balance of evidence favors a constructive but selective outlook: the market compounds near 6–7% to 2033, but growth concentrates in preventive skincare and mass-to-mid tiers rather than prestige anti-aging alone. Vendors that lean into sunscreen, barrier-care and refill sustainability align with where demand is actually accelerating.
The strongest counter-argument is that J-Beauty's measured brand storytelling limits younger-consumer capture, ceding share to faster-moving K-Beauty and Western dermobrands — a real risk that could compress the higher CAGR readings if digital investment lags. We treat the 3.27% low-end estimate as a scenario, not a base case, since it predates the cross-border e-commerce inflection.
Actionable Strategy:
What would change this conclusion: a sustained deceleration in Asia Pacific cross-border demand, or regulatory tightening on UV filters and quasi-drug claims in the U.S. and EU, would push us toward the conservative forecast and a defensive positioning stance.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.3% from 2020-2034 |
| Segmentation |
|
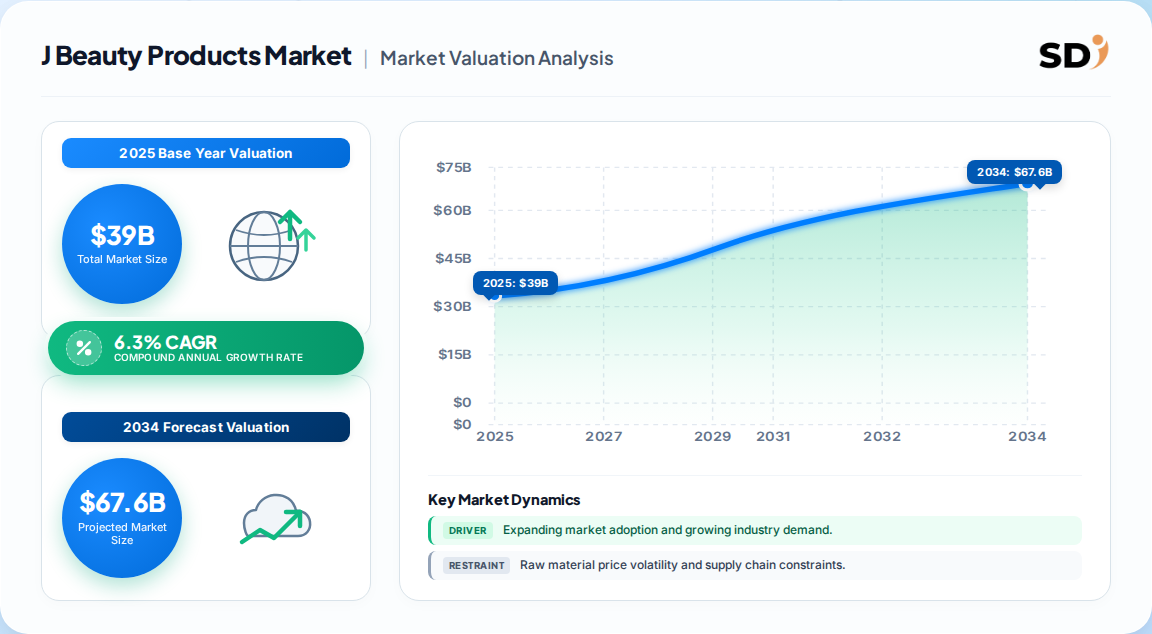
The J Beauty Products Market was valued at roughly 37.2 Billion in 2025 and an estimated 39.0 Billion in 2026. Broader definitions including licensee production push the figure higher, while brand-origin-only estimates sit near 8.4 Billion.
Most published forecasts cluster around a 6.3% CAGR through 2033, reaching roughly 59.8 Billion. A conservative competing estimate sits near 3.27%, reflecting narrower scope and pre-2023 channel data rather than a genuine slowdown.
Asia Pacific leads with about 60.8% of global revenue in 2025, anchored by Japan as the origin market. North America is the fastest-growing export region, followed by Europe and the Middle East, where premium skincare demand is rising.
Skincare is the largest segment at roughly 48.9% of revenue, driven by moisturizers, essences and sunscreen built around barrier-care routines. Haircare and color cosmetics follow as stable repeat-purchase categories with steady demand.
Shiseido, Kao, Kosé, POLA Orbis and DHC anchor the competitive field, alongside Mandom, FANCL and Kracie. Incumbents compete on formulation IP, ingredient provenance and routine-based brand education rather than price alone.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the value chain, spanning raw material and botanical ingredient suppliers, specialized cosmetic formulators, contract manufacturers, Japanese brand owners and global distributors. Interview designations included VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring supply-side capacity data is triangulated against commercial demand signals.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Quality Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Botanical Ingredient Suppliers | 30% |
| Cosmetic Formulators & Contract Manufacturers | 30% |
| Japanese Brand Owners & Licensees | 25% |
| Global Distributors & Retail Channels | 15% |
Secondary validation draws on UN Comtrade and WTO cross-border cosmetic trade flows, US ITC and Eurostat import-export records, corporate annual filings and investor presentations (10-K, SEC filings), patent databases for fermentation and encapsulation technology, and recognized technical standards from cosmetic chemistry associations and ISO cosmetic guidelines.
We run simultaneous Top-Down allocation (macroeconomic beauty spend, regional segment shares) and Bottom-Up modeling (manufacturer capacity, price-per-unit, end-use consumption) to triangulate value. Divergent outputs are reconciled against channel-level sell-through and cross-border trade data before a base-year figure is fixed.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |