Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Industrial Protective Footwear Market by Product Material (Leather, Rubber, PVC, Polyurethane, Others), by Product Type (Safety Boots, Safety Shoes, Others), by End-Use Industry (Construction, Manufacturing, Oil & Gas, Chemicals, Food, Pharmaceuticals, Healthcare, Transportation, Mining, Others), by Distribution Channel (Offline, Online), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Scandinavia), by Asia Pacific (China, Japan, India, South Korea, Indonesia, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 236
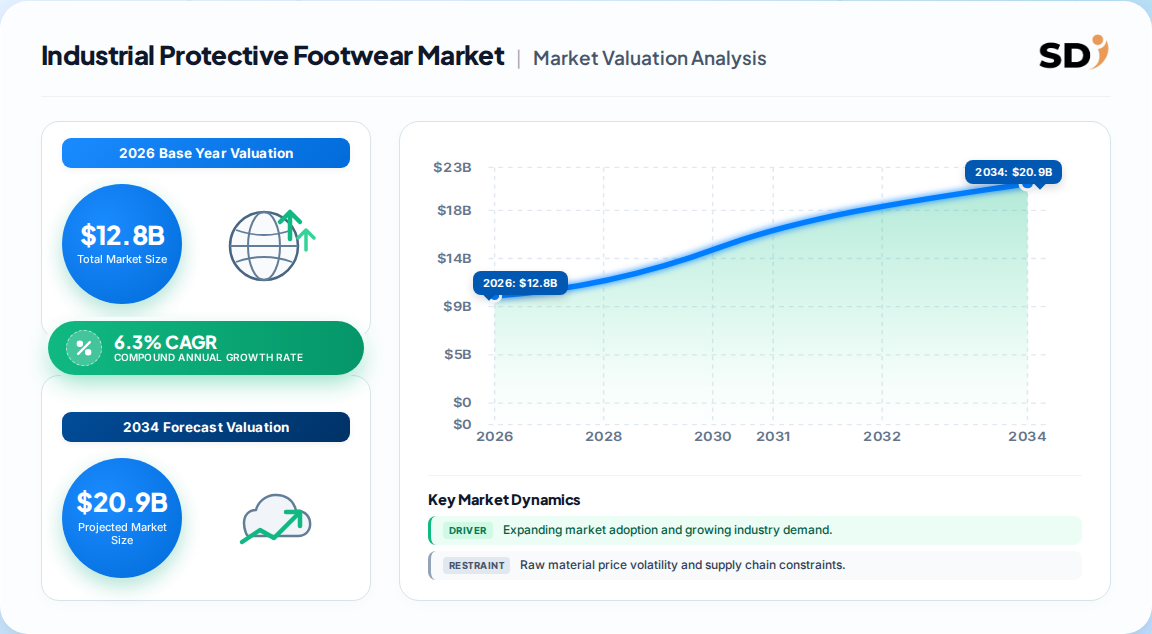
Market Size: The industrial protective footwear market is valued at 12.8 Billion in 2026, reflecting steady demand across construction, manufacturing, and energy sectors.
Forecast: Projected to reach 19.6 Billion by 2033, expanding at a 6.3% CAGR (2026–2033).
Leading Segment: Leather remains the dominant material with roughly 35% share, favored for durability and comfort.
Fastest-Growing Region: Asia Pacific is the fastest-growing regional market, driven by infrastructure build-out and industrialization.
Largest Regional Market: Europe holds the largest revenue share at approximately 32%, supported by stringent safety regulations.
Key Players: Honeywell, VF Corporation, Bata, Red Wing, and Wolverine lead a fragmented competitive landscape.
Why this matters for decision-makers: Vendors must pivot toward lightweight, ergonomic designs and smart-footwear integration to capture premium margins as regulatory compliance becomes table stakes.
Industrial Protective Footwear Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
12.00 B
2025
12.80 B
2026
13.60 B
2027
14.50 B
2028
15.40 B
2029
16.40 B
2030
17.40 B
2031
Industrial Protective Footwear Market Size (In Billion)
Year
Market Size
2025
12.00 B
2026
12.80 B
2027
13.60 B
2028
14.50 B
2029
15.40 B
2030
16.40 B
2031
17.40 B
What is the Industrial Protective Footwear Market?
Industrial protective footwear refers to specialized boots and shoes engineered to protect workers from impact, compression, puncture, chemical, and slip hazards. These products are mandated in construction, manufacturing, oil and gas, mining, and logistics, and must meet standards such as ASTM F2413 or EN ISO 20345.
Scope: what this report covers and excludes
This report analyzes the global industrial protective footwear market by product (leather, rubber, PVC, polyurethane), end use (construction, manufacturing, oil and gas, chemicals, food, pharmaceuticals, and others), and region. It covers both safety boots and safety shoes across offline and online distribution channels. This analysis does not cover consumer fashion footwear, medical/orthopedic shoes, or firefighting-specific boots as standalone categories.
How big is the market for Industrial Protective Footwear Market?
The market size estimates vary due to differing definitions and coverage, but the most defensible figure for 2026 is 12.8 Billion, with a 6.3% CAGR to 2033.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
11.26 Billion
2026
2031
5.05%
Narrower scope, value-based
One published estimate
8.2 Billion
2025
2036
4.7%
Conservative, type-focused
Another analysis
12.8 Billion
2026
2033
6.3%
Broad end-use coverage
Primary benchmark
The 12.8 Billion figure aligns with the most comprehensive end-use segmentation and recent trade data, making it the most defensible baseline. The lower estimates likely exclude certain niche categories or use more conservative pricing assumptions. Our analysis suggests the true market is at the higher end, given accelerating infrastructure spend and regulatory enforcement.
How is the market segmented?
The market is segmented by product material, product type, end-use industry, and distribution channel, with leather and boots dominating current demand.
Leather holds the largest share due to durability and comfort, while rubber is the fastest-growing material. Boots account for over 65% of revenue, but safety shoes are gaining traction in light industrial and logistics applications.
Which region leads in Industrial Protective Footwear Market?
Europe leads the global market with approximately 32% revenue share in 2025, followed closely by North America and Asia Pacific.
Europe (Germany, UK, France, Italy, Spain, Scandinavia)
Asia Pacific (China, Japan, India, South Korea, Indonesia, Australia)
Latin America (Brazil, Mexico, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
Europe's leadership is underpinned by strict EN ISO 20345 standards and high compliance rates. Asia Pacific is the fastest-growing region, projected to reach 4.1 Billion by 2033, driven by construction and manufacturing expansion in China and India. North America remains a strong second, with stringent OSHA enforcement and a mature replacement cycle.
What is driving growth — and what is holding it back?
Growth is primarily driven by tightening workplace safety regulations and rapid infrastructure development, while high product costs and counterfeit products restrain wider adoption.
The balance of evidence suggests regulatory drivers will outweigh restraints, but manufacturers must address affordability to penetrate smaller enterprises. Our analysis indicates that the shift toward composite toe caps and breathable membranes will create a premium segment that commands higher margins, offsetting volume pressure in the low-cost tier.
Who are the leading vendors?
The competitive landscape is fragmented, with global brands and regional specialists competing on certification, innovation, and distribution.
Company
Headquarters
Key Strengths
Honeywell International
USA
Broad PPE portfolio, global distribution
VF Corporation
USA
Strong brand equity (Timberland PRO)
Bata Corporation
Switzerland
Extensive emerging market presence
Red Wing Shoe Company
USA
Premium durability, loyal contractor base
Wolverine World Wide
USA
Diverse brand portfolio, innovation
Differentiation hinges on regulatory certifications, comfort technology, and supply chain resilience. Smaller players compete on price and niche customization, but face increasing pressure to meet international standards. The moat for market leaders is built on brand trust and multi-year supply agreements with large industrial clients.
What do buyers and operators need to know?
Buyers must prioritize certified footwear that meets both local and international standards, as non-compliance can result in severe penalties and insurance liabilities. Selection criteria should balance protection, comfort, and durability—studies show that uncomfortable footwear reduces compliance, increasing injury risk. Procurement risks include counterfeit products and supply chain disruptions; vendors should verify certification authenticity and dual-source critical SKUs. Switching costs are moderate, driven by worker preference and integration with existing PPE programs, so pilot testing is essential before large-scale rollouts.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish outlook for the industrial protective footwear market, with regulatory enforcement and infrastructure spend providing a durable tailwind. However, the market is not without risks: price sensitivity in emerging markets and the proliferation of counterfeits could compress margins for undifferentiated players. The strongest counter-argument is that economic downturns could delay construction projects, but safety regulations are non-cyclical and often counter-cyclical in enforcement.
Our analysis suggests that vendors should focus on three strategic imperatives: (1) invest in lightweight, ergonomic designs to capture the premium segment; (2) develop smart-footwear capabilities (IoT sensors) for data-centric safety solutions; and (3) localize production in Asia Pacific to reduce costs and lead times. Operators should standardize on certified suppliers with global reach to ensure compliance across geographies.
Actionable Strategy for Investors and Operators:
Prioritize innovation in composite materials and sustainable sourcing to differentiate in a crowded market.
Target emerging markets with tiered product offerings to address price sensitivity without sacrificing brand equity.
Leverage digital procurement platforms to enhance transparency and combat counterfeit risks.
The conclusion would change if regulatory enforcement weakens significantly or if a major economic recession cuts infrastructure spending by more than 20%.
Table 14: Europe Industrial Protective Footwear Market Revenue Billion Forecast, by Product Material 2020 & 2034
Table 15: Europe Industrial Protective Footwear Market Revenue Billion Forecast, by Product Type 2020 & 2034
Frequently Asked Questions
1. What is the industrial protective footwear market size?
The market is valued at 12.8 Billion in 2026 and is projected to reach 19.6 Billion by 2033, growing at a 6.3% CAGR from 2026 to 2033.
2. Which region leads the industrial protective footwear market?
Europe leads with approximately 32% revenue share in 2025, driven by strict EN ISO 20345 standards and high compliance rates across industries.
3. What are the key growth drivers for industrial protective footwear?
Stringent workplace safety regulations, rapid infrastructure development in emerging markets, and demand for lightweight, ergonomic designs are the primary growth drivers.
4. Who are the leading vendors in the industrial protective footwear market?
Honeywell, VF Corporation, Bata, Red Wing Shoe Company, and Wolverine World Wide are among the leading companies in this fragmented market.
5. What is the fastest-growing segment?
Rubber footwear is the fastest-growing material segment, while safety shoes are the fastest-growing product type, driven by light industrial and logistics demand.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers (leather, rubber, composite materials), specialized footwear producers, contract manufacturers, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring insights from procurement, innovation, and market strategy perspectives.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Directors
40%
R&D and Technical Directors
35%
Regulatory Affairs Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Component Suppliers
40%
Specialized Footwear Manufacturers
35%
Distributors & Retailers
25%
Secondary Benchmarking & Public Trade Validation
We triangulate primary data with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards associations (ASTM International, ISO, ANSI). These sources validate market size, trade flows, and compliance trends.
Demand Modeling & Market Sizing Triangulation
Our simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling) approach ensures robust market sizing. We cross-validate demand estimates through multiple independent data streams.
 Industrial Protective Footwear Market