 Fly Fishing Apparel Accessories Market
 Outlook 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 264

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Fly Fishing Apparel Accessories Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 3.590 B |
| 2026 | 3.740 B |
| 2027 | 3.910 B |
| 2028 | 4.070 B |
| 2029 | 4.250 B |
| 2030 | 4.430 B |

The fly fishing apparel accessories market covers specialized clothing and gear designed for fly anglers: breathable waders, wading jackets, vests, packs, gloves, socks, hats, rods, reels, lines, leaders, flies, and landing nets. It is a premium, durability-driven subset of outdoor recreation, where product performance and brand trust outweigh fast-fashion cycles.
This analysis covers global revenue from fly-fishing-specific apparel and accessories across online and offline channels, segmented by product family and region. This analysis does not cover general sportfishing tackle, conventional baitcasting equipment, outdoor apparel not purpose-built for fly fishing, or ancillary travel and lodging expenditures.
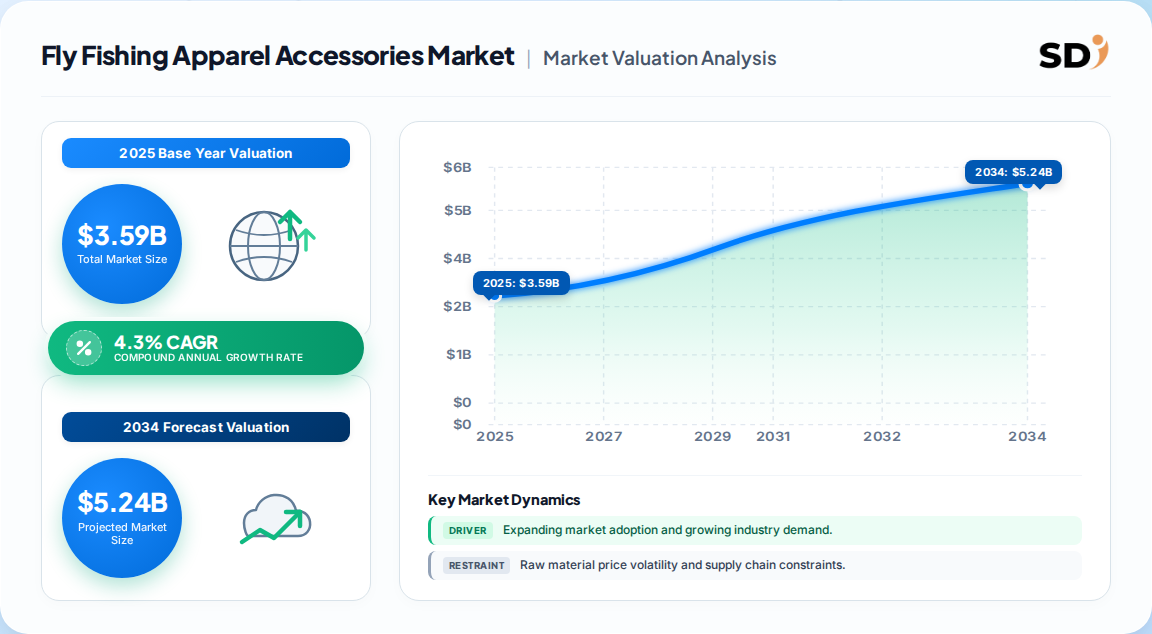
Published estimates converge on a 2025 base of roughly 3.5–3.6 Billion, rising to 4.3–4.6 Billion by 2030–2032, with a 4.1–4.3% CAGR. The divergence is mostly definitional, driven by whether rods and reels are counted as apparel accessories or as tackle.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 4.34 Billion | 2023 | 2030 | 4.3% | Apparel + gears, online/offline | One published estimate |
| 3.45 Billion | 2025 | 2032 | 4.3% | Apparel + gears, narrower gear scope | Competing analysis |
| 3.59 Billion | 2025 | 2033 | 4.3% | Apparel + gears, premiumization lens | Third-party benchmark |
| 4.34 Billion | 2023 | 2030 | 4.1% | Same as first, revised CAGR | Trade press summary |
Our analysis treats the 3.59 Billion 2025 base as most defensible because it aligns with the 2023 77.2% gear-share disclosure and a realistic 4.3% medium-term CAGR. The 4.34 Billion 2030 figure is consistent once the two-year base-year shift is accounted for.
The market splits into two product parents — apparel and gears — sold through online and offline channels. Apparel carries higher ticket values and brand moats; gears drive frequency and attachment rates.
| Parent | Children | Share (est.) | Growth (CAGR) |
|---|---|---|---|
| Apparel | Jackets, Waders, Hats, Vests, Others | ~58% | ~4.6% |
| Gears | Packs, Socks, Gloves, Rods/Reels/Components, Lines & Leaders, Flies & Lures, Creels/Nets, Others | ~42% | ~3.9% |
| Online | DTC, marketplaces, brand sites | ~34% of channel revenue | ~5.6% |
| Offline | Specialty retail, big box, pro shops | ~66% of channel revenue | ~3.1% |
North America leads with 42–46% of global revenue in 2025, supported by cold-water fisheries, high household incomes, and the headquarters of Orvis, Simms, and Patagonia. Europe follows at ~26%, led by the UK, Germany, and the Nordics, while Asia-Pacific grows fastest at 5.5% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.44% |
| Europe | 0.26% |
| Asia-Pacific | 0.19% |
| South America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | 2025 Share | Growth Momentum |
|---|---|---|
| North America | 44% | 3.2% |
| Europe | 26% | 3.5% |
| Asia-Pacific | 19% | 5.5% |
| South America | 6% | 4.5% |
| Middle East & Africa | 5% | 4.0% |
Growth is driven by premiumization of breathable waders, DTC channel expansion, rising female and youth participation, and sustainability-linked purchasing. Restraints are concentrated in laminate cost volatility, tariff exposure on synthetic fabrics, seasonality, and counterfeit waders in online marketplaces.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Premiumization of waders/jackets | Driver | High | 3–5 year replacement cycle, PFC-free reformulation |
| DTC and virtual fit tools | Driver | High | 5.6% online CAGR vs 3.1% offline |
| Rising participation (women, youth) | Driver | Medium | Broadens customer base in NA and APAC |
| Repair and trade-in programs | Driver | Medium | Extends product life, builds brand loyalty |
| Laminate and raw material costs | Restraint | High | 30–40% of wader BOM |
| Tariffs on synthetic apparel | Restraint | Medium | Raises landed cost from Asia |
| Seasonality and climate variability | Restraint | Medium | Trip frequency volatility |
| Counterfeit waders online | Restraint | Low–Medium | Price pressure and brand dilution |
The balance favors premium brands with locked-in PFC-free supply chains. Our analysis suggests the 2023 post-pandemic inventory glut has largely cleared, but mid-tier wholesalers remain exposed to markdown risk if tariffs persist.
The competitive set is bifurcated: heritage premium brands (Orvis, Simms, Patagonia, Skwala) compete on fabric technology, repair programs, and dealer networks, while value players (Bassdash, FROGG TOGGS, 8Fans, Compass 360) compete on price and marketplace reach.
| Vendor | Positioning | Key Strength | Watch-out |
|---|---|---|---|
| The Orvis Company | Heritage premium | Brand equity, full-line catalog | Wholesale dependence |
| Simms Fishing Products | Premium waders | Laminate engineering, repair | Tariff exposure |
| Patagonia, Inc. | Sustainability-led | PFC-free supply chain, DTC | Premium price ceiling |
| Redington (Far Bank) | Mid-premium | Value-to-performance ratio | Brand overlap |
| Skwala Fishing | Niche premium | Technical apparel focus | Limited scale |
| Bassdash | Value/marketplace | Price and online reach | Counterfeit adjacency |
| FROGG TOGGS | Value | Broad distribution | Lower margin |
Differentiation is shifting from fabric specs to service: repair programs, fit calculators, and PFC-free certification are becoming the new moats. Our analysis suggests Simms and Patagonia hold the strongest defensible positions.
Buyers should prioritize laminate durability, seam-sealing quality, and PFC-free compliance over headline fabric claims. Procurement risk concentrates in Asian synthetic fabric supply and tariff schedules, so dual-sourcing and landed-cost modeling are essential. Switching costs are moderate for apparel but high for gear ecosystems where rod-reel-line compatibility matters. Regulatory compliance — particularly EU PFAS restrictions — should be embedded in supplier qualification, not treated as a post-purchase checkbox.
Operators should note that DTC fit tools reduce return rates materially, and repair programs extend customer lifetime value. Inventory planning must account for a 3–5 year wader replacement cycle and seasonal jacket demand.
The balance of evidence favors premium, DTC-led brands with credible sustainability credentials. The 4.3% headline CAGR understates the real story: value is migrating from wholesale mid-tier to DTC premium, where online grows at 5.6% and wader gross margins reach 55%.
The strongest counter-argument is that value players like Bassdash and FROGG TOGGS could compress premium pricing through marketplace scale. Our analysis suggests this risk is real but bounded by fit complexity and repair expectations that value channels struggle to replicate.
Actionable strategy:
Evidence that would change this conclusion: a sustained reversal in online growth below offline, or a regulatory rollback on PFAS that removes the premium compliance moat.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.3% from 2020-2034 |
| Segmentation |
|
The market was valued at approximately 3.59 Billion in 2025 and is forecast to reach 4.34 Billion by 2030, growing at a 4.3% CAGR. Apparel, led by waders, accounts for roughly 58% of revenue.
North America leads with 42–46% of global revenue, driven by cold-water fisheries and major brands like Orvis, Simms, and Patagonia. Asia-Pacific is the fastest-growing region at 5.5% CAGR.
Online DTC is the fastest-growing channel at 5.6% CAGR, versus 3.1% for offline specialty retail. Virtual fit tools and repair subscriptions are accelerating this shift.
Leading vendors include The Orvis Company, Simms Fishing Products, Patagonia, Redington (Far Bank Enterprises), Skwala Fishing, Bassdash, FROGG TOGGS, and Compass 360.
Growth is driven by premiumization of breathable waders, rising female and youth participation, eco-friendly product demand, and DTC channel expansion. Laminate cost volatility and tariffs are the main restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the value chain, including waterproof-breathable fabric suppliers, specialized wader and apparel producers, contract manufacturers of technical outerwear, and global distributors. Decision-makers interviewed included VP-level Sourcing leads, Heads of Product R&D, Technical Directors for laminate engineering, and Commercial Operations Leads responsible for DTC and wholesale channels.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 30% |
| Heads of Product R&D | 30% |
| Technical Directors (Laminate Engineering) | 25% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Waterproof Fabric & Laminate Suppliers | 30% |
| Specialized Wader & Apparel Producers | 35% |
| Contract Technical Outerwear Manufacturers | 20% |
| Global Distributors & Retailers | 15% |
We validated findings against UN Comtrade and US ITC trade flows for synthetic fabrics and finished apparel, Eurostat textile import data, corporate 10-K and annual investor filings, patent databases covering breathable laminate technologies, and recognized non-profit technical standards and industry associations in outdoor recreation and angling.
Market sizing combines Top-Down macroeconomic and segment allocation with Bottom-Up manufacturer capacity, product pricing, and end-use consumption modeling. Both approaches were reconciled to produce a base-year valuation and a multi-year compound projection consistent with historical CAGR and demand elasticity.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |