 Asia Pacific Footwear Market
: Size, Growth & Forecast to 2031
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 273

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Asia Pacific Footwear Market
Vijayashree Ugale
Research Analyst

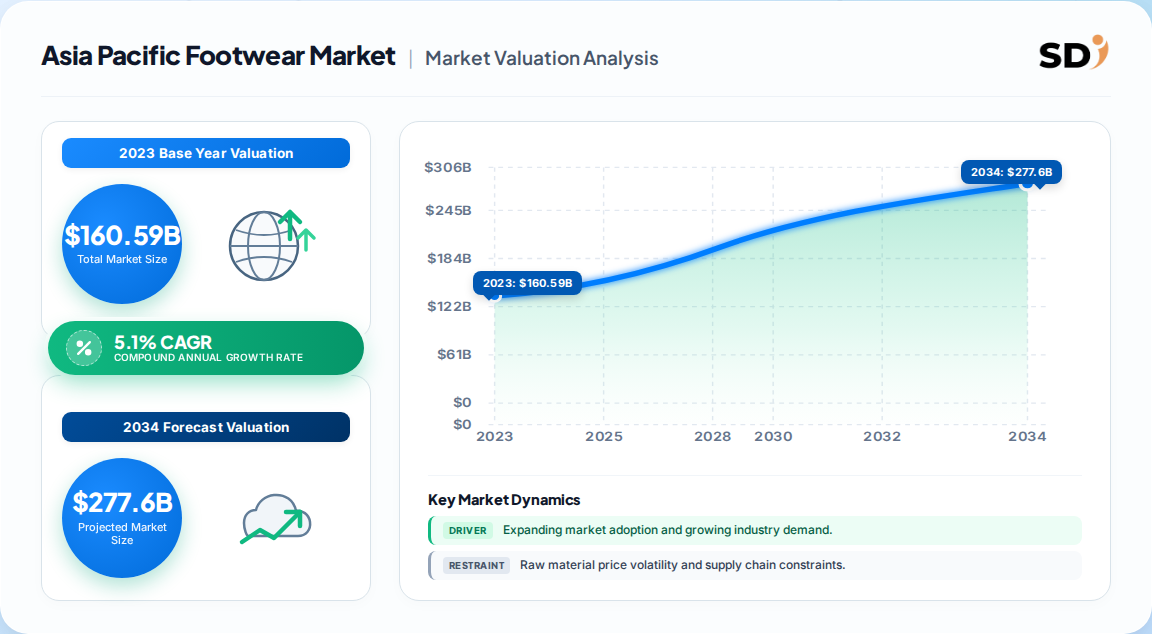
| Year | Market Size |
|---|---|
| 2023 | 160.6 B |
| 2024 | 168.8 B |
| 2025 | 177.4 B |
| 2026 | 186.4 B |
| 2027 | 195.9 B |
| 2028 | 205.9 B |
| 2029 | 216.4 B |

The Asia Pacific footwear market is the total revenue from footwear sold across China, Japan, India, Australia, and the rest of Asia Pacific, spanning athletic footwear (running, sports, hiking, aerobic) and non-athletic footwear (casual, formal, sandals, boots) sold through retail and online channels to men, women, and children. It represented roughly 40% of global footwear value in 2023.
This analysis covers athletic and non-athletic footwear across the Asia Pacific geography, segmented by type, activity, product, end user, price category, and distribution channel. Market values are stated in USD at retail or revenue level depending on source.
This analysis does not cover footwear manufacturing equipment, raw-material supply chains (leather, synthetics, foams), repair and aftermarket services, or adjacent segments such as handbags, apparel, and technical accessories. Orthopaedic and medical-grade therapeutic footwear is excluded except where sold through athletic channels.
The most defensible reading is a two-tier structure: a broad USD 160.59 Billion total footwear base growing near 5.1%, with a USD 67.52 Billion athletic subset in 2026 accelerating at roughly 9.88% — meaning athletic is both the largest single category and the one reshaping the total.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 160.59 Billion | 2023 | 2024–2030 | 5.1% | Total footwear, athletic + non-athletic, retail value | One published estimate |
| USD 61.45 Billion | 2025 | 2026–2031 | 9.88% | Athletic footwear only, revenue value | A competing analysis |
| ~40% of global footwear | 2023 | — | — | Asia Pacific share of global footwear value | Global industry benchmark |
| USD 125.98 Billion | 2024 | 2025–2033 | 3.76% | Global athletic footwear (context only) | One published estimate |
Which figure to trust? The total-footwear figure captures the true addressable base, but the athletic figure is the one that matters for planning. Our analysis suggests the 9.88% athletic CAGR is credible given China's 59% concentration and India's 11.52% trajectory, though it likely overstates near-term growth if mass-market price pressure persists.
Segment logic is best read as overlapping lenses rather than mutually exclusive buckets: product form dominates value, activity defines demand drivers, and end user and price tier govern margin.
| Parent Segment | Children |
|---|---|
| By Type | Athletic Footwear, Non-Athletic Footwear |
| By Activity | Running Shoes, Sports Shoes, Aerobic Shoes, Walking Shoes, Trekking & Hiking Shoes |
| By Product Type | Shoes, Boots |
| By End User | Men, Women, Kids/Children |
| By Category | Premium, Mass |
| By Distribution Channel | Sports & Athletic Goods Stores, Supermarkets/Hypermarkets, Brand Outlets, Specialty Stores, Online Retail |
Shoes commanded 86.68% of athletic value in 2025, but boots are compounding at 10.11% — a niche with outsized momentum for vendors seeking differentiation.
China leads decisively, holding 58.64% of 2025 athletic footwear value and about 59.27% of 2024 regional sales; Japan and India are the next most material, with India on the steepest growth curve at 11.52% CAGR to 2031.
| Geography | Share of Regional Value |
|---|---|
| China | 58.6% |
| India | 12.1% |
| Japan | 9.8% |
| Australia | 5.2% |
| Rest of Asia Pacific | 14.3% |
Our analysis suggests China concentration is a double-edged exposure: it underwrites regional scale but imports Chinese consumer-credit risk into every regional forecast.
Growth is demand-pull, not supply-push: young populations, sports policy, and premiumization are expanding the pool of buyers, while cost inflation, counterfeits, and tariff friction cap how much value that pool converts into branded revenue.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Youth population & influencer culture | Driver | Strong (+2.1% CAGR impact) | Social media normalizes sneaker culture and repeat purchase |
| Favorable government sports initiatives | Driver | Strong (+1.8%) | Facilities and programs raise participation baseline |
| Rising health and fitness awareness | Driver | Moderate-strong (+1.6%) | Fitness routines convert to specialized footwear demand |
| Aggressive brand marketing | Driver | Moderate (+1.5%) | Localized content and athlete partnerships build share |
| Women's sports participation | Driver | Moderate (+1.2%) | Expands underserved female-specific product demand |
| Sustainability preference | Driver | Emerging (+1.0%) | Recycled uppers command premium in urban Japan, Australia, China |
| Counterfeiting and grey-market imports | Restraint | Moderate | Erodes branded price integrity in mass tiers |
| Input cost and tariff volatility | Restraint | Moderate | Compresses margins in low-price segments |
Read together, the driver stack is worth roughly 7-8 percentage points of incremental CAGR, which explains why athletic growth outpaces total footwear. The restraints are margin-side rather than volume-side — which is why premiumization is the strategic lever, not price cutting.
The competitive field is medium-concentration, with global performance brands holding technology and brand equity while regional and domestic players compete aggressively on price, distribution depth, and local relevance.
| Company | Positioning | Key Regional Strength | Moat Type |
|---|---|---|---|
| Nike Inc. | Global performance leader | China, Japan, Australia | Brand, R&D, DTC data |
| Adidas AG | Global performance and lifestyle | China, India, Japan | Brand, football heritage |
| ASICS Corporation | Technical running specialist | Japan, Australia | Running credibility, cushioning IP |
| Puma SE | Sport-lifestyle hybrid | India, China | Marketing agility, price reach |
| New Balance Inc. | Premium lifestyle-performance | Japan, China | Fit, premium perception |
| Skechers Inc. | Comfort mass-market | China, India, Southeast Asia | Comfort positioning, value price |
| Under Armour Inc. | Performance training | Australia, Japan | Training category equity |
| Domestic Chinese brands | Value-to-mid domestic | China tier-2/3 cities | Distribution reach, price |
Differentiation is increasingly software-mediated: loyalty data, virtual try-on, and DTC app ecosystems are becoming the durable moat, not just footwear engineering. Regional challengers are eroding share precisely where global brands have the thinnest local content pipelines.
Selection criteria now hinge on four tests: fit-for-region sizing (Asian lasts differ materially from Western), channel economics (DTC versus wholesale margin split), compliance with country-specific labelling and chemical-safety rules, and supply-chain resilience given concentrated sourcing. Procurement teams should stress-test landed costs against tariff shifts and freight volatility, because a 9.88% category CAGR does not guarantee brand-level margin expansion.
Switching costs in this market are low for consumers but high for operators — retail shelf space, distributor relationships, and marketing calendars create real lock-in on the supply side. Counterfeit risk in mass tiers is a brand-dilution hazard, so authenticity and traceability programs are operational necessities, not marketing extras. Regulatory compliance varies sharply by country, and footwear labelling, chemical restrictions, and import duties should be validated market by market before scale commitments. Our analysis suggests operators that lock in local content and distribution depth early will outearn those chasing short-term volume.
The balance of evidence favors a re-weighted Asia Pacific strategy: athletic-first, China-anchored but India-diversified, and digitally routed. The 5.1% total-market CAGR understates the opportunity because it blends a decelerating non-athletic base with a near-10% athletic engine; investors treating the region as a single number will misprice it. The strongest counter-argument is that China's 58.6% concentration and consumer-credit softness could drag the regional blended figure below forecast, and the athletic premium may compress if mass-tier price wars intensify.
Our judgment: the growth is real but unevenly distributed. The winners will be those who treat women's and kids' segments as primary rather than extension markets, because those are the segments compounding above 10% while men's remains a share-defense game. Sustainability is not yet a revenue driver at scale, but it is fast becoming a procurement gate in Japan and Australia.
Actionable strategy:
What would change this conclusion: a sustained sub-3% China consumption print, or a sharp reversal in athletic premiumization, would invalidate the athletic-led thesis and favor a defensive mass-market posture.
This study applies a 70/30 primary-to-secondary research split, reflecting the need for ground-truth verification in a market where retail pricing, channel mix, and country-level demand diverge sharply. In-depth interviews were conducted with stakeholders across the value chain, including raw-material and component suppliers, specialized footwear producers, contract manufacturers, regional distributors, and omnichannel retailers. Decision-maker interviews targeted VP-level Sourcing, Heads of Product Development, Commercial Operations Leads, and Regional Category Directors across China, India, Japan, and Australia.
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO), national statistical agencies, customs and tariff schedules, corporate annual filings and investor presentations, patent databases for cushioning and material technologies, and recognized industry associations and technical standards bodies active in footwear safety and labelling.
Sizing combined top-down macroeconomic allocation (population, disposable income, urbanisation, sports participation rates) with bottom-up modeling of manufacturer capacity, product pricing, and end-use consumption across athletic and non-athletic lines. Country-level figures were reconciled to regional totals and cross-checked against trade flow data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Region | Market Share (%) |
|---|---|
| China | 0.59% |
| Japan | 0.1% |
| India | 0.12% |
| Australia | 0.05% |
| Rest of Asia Pacific | 0.14% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.1% from 2020-2034 |
| Segmentation |
|
The total Asia Pacific footwear market was estimated at USD 160.59 Billion in 2023. Athletic footwear alone was valued at USD 67.52 Billion in 2026 and is forecast to reach USD 108.16 Billion by 2031.
Total footwear is growing near 5.1% annually, while athletic footwear compounds at roughly 9.88% through 2031. The spread shows athletic lines taking share from non-athletic categories.
China dominates with about 58.6% of regional athletic footwear value in 2025. India is the fastest-growing major market at an 11.52% CAGR through 2031.
Online retail leads channel growth at 11.21% CAGR, while premium (10.76%) and kids (10.58%) outpace other segments. Boots at 10.11% are the standout non-shoe product form.
Nike, Adidas, ASICS, Puma, New Balance, Skechers, and Under Armour lead the branded field, competing with fast-scaling domestic Chinese brands in a moderately concentrated market.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split, reflecting the need for ground-truth verification in a market where retail pricing, channel mix, and country-level demand diverge sharply. In-depth interviews were conducted with stakeholders across the value chain, including raw-material and component suppliers, specialized footwear producers, contract manufacturers, regional distributors, and omnichannel retailers. Decision-maker interviews targeted VP-level Sourcing, Heads of Product Development, Commercial Operations Leads, and Regional Category Directors across China, India, Japan, and Australia.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Product Development Heads | 30% |
| Commercial Operations Leads | 20% |
| Regional Category Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Footwear Manufacturers & Contract Producers | 40% |
| Raw Material & Component Suppliers | 25% |
| Distributors & Retailers | 25% |
| Brand Owners & Licensees | 10% |
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO), national statistical agencies, customs and tariff schedules, corporate annual filings and investor presentations, patent databases for cushioning and material technologies, and recognized industry associations and technical standards bodies active in footwear safety and labelling.
Sizing combined top-down macroeconomic allocation (population, disposable income, urbanisation, sports participation rates) with bottom-up modeling of manufacturer capacity, product pricing, and end-use consumption across athletic and non-athletic lines. Country-level figures were reconciled to regional totals and cross-checked against trade flow data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |