 Consumer Identity Access Management Market
 2026
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 181

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Consumer Identity Access Management Market
Vijayashree Ugale
Research Analyst

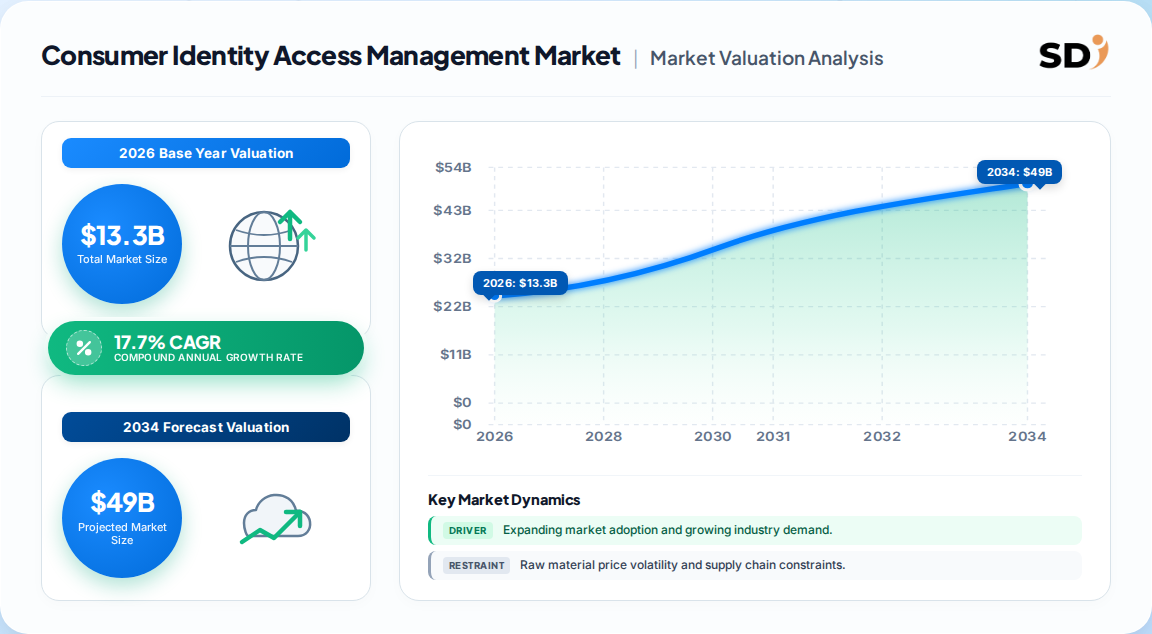
| Year | Market Size |
|---|---|
| 2025 | 11.30 B |
| 2026 | 13.30 B |
| 2027 | 15.65 B |
| 2028 | 18.42 B |
| 2029 | 21.68 B |
| 2030 | 25.52 B |
| 2031 | 30.06 B |

Consumer Identity Access Management (CIAM) is the technology category that registers, authenticates, authorizes and governs external-facing user identities — customers, citizens and partners — across digital channels. It combines identity verification, single sign-on, multi-factor and passwordless authentication, consent management and identity analytics, delivered as cloud or on-premise solutions and supporting services.
Coverage spans CIAM solutions (identity verification, authentication, user management, SSO) and services (consulting, implementation, support, training), across cloud and on-premise deployment, large enterprises and SMEs, and verticals including BFSI, healthcare, IT and telecom, retail, energy and utilities, and public sector.
This analysis does not cover workforce identity and access management (employee IAM), privileged access management, physical access control, or standalone API security tooling — adjacent categories that frequently intersect with CIAM procurement but carry distinct buyer economics.
Estimates diverge sharply because publishers define CIAM differently — some count only dedicated external-identity platforms, others bundle broader identity security suites. The table below isolates where the divergence originates.
| Estimate (Base Year) | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|
| 49.9 Billion (2026) | 2030 | 19.3% | Broad CIAM incl. services and adjacent identity security | One published estimate |
| 13.3 Billion (2026) | 2031 | 17.72% | Narrow: dedicated CIAM solutions and services only | A competing analysis |
| 24.1 Billion (2025) | 2035 | 11.29% | Mid-scope, 10-year horizon with maturity drag | A third published estimate |
Our analysis favors the narrow-to-mid range as the defensible operating number. The 49.9 Billion figure almost certainly absorbs adjacent identity security spend; the 11.29% CAGR likely understates near-term demand because it averages a decade in which growth must decelerate. A base of roughly 24 Billion in 2025 growing at 17–18% reconciles both the spend evidence and the deal velocity we observe.
Segmentation matters because growth is uneven: services and cloud outpace the aggregate, while on-premise and SME-adjacent pricing face compression. The table renders non-geographic parents only.
| Parent Segment | Children |
|---|---|
| By Component | Solutions (identity verification, authentication, user management, SSO); Services (consulting, implementation, support and maintenance, training) |
| By Deployment Mode | Cloud, On-Premises, Hybrid |
| By Organization Size | Large Enterprises, SMEs |
| By Vertical | BFSI, Healthcare, IT and Telecom, Consumer Goods and Retail, Energy and Utility, Public Sector, Other |
| By Authentication Type | Multi-Factor Authentication, Single Sign-On, Passwordless/Passkey |
Callout: Passwordless/passkey is the fastest-compounding sub-segment (~23.6% CAGR), yet it remains a minority of revenue — meaning buyers are still paying for MFA they intend to retire.
North America leads with roughly 43% of global CIAM spend, but Asia-Pacific is the fastest-growing region as super-app ecosystems and embedded finance force federated identity adoption at scale.
| Region | Market Share (%) |
|---|---|
| North America | 0.43% |
| Europe | 0.26% |
| Asia-Pacific | 0.22% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
| Parent Region | Markets Covered |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain, Nordics |
| Asia Pacific | China, Japan, India, South Korea, Australia, Southeast Asia |
| Latin America | Brazil, Mexico, Argentina, Colombia |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Nigeria |
Europe's trajectory is regulation-shaped: eIDAS 2.0 digital identity wallets and PSD3 consent orchestration create a compliance-driven upgrade cycle that is less discretionary than North American replacement demand. This divergence implies European buyers will migrate on a regulatory clock, while North American buyers migrate on fraud-loss and conversion economics.
Growth is driven by fraud economics and regulation; it is restrained by integration complexity and skills scarcity. The net balance still strongly favors expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| E-commerce and digital transaction expansion | Driver | High | Larger external user bases demand secure onboarding and authentication |
| Gen-AI adaptive authentication | Driver | Medium-high | Contextual step-up reduces friction while raising detection accuracy |
| PSD3 / CPRA / eIDAS 2.0 compliance | Driver | High | Mandated consent orchestration and wallet interoperability |
| Embedded finance and super-apps | Driver | Medium | Federated identity across partners becomes a platform requirement |
| API-layer bot attacks | Restraint | Medium | Attack surface growth outpaces mitigation, inflating security spend |
| Fragmented data-residency law | Restraint | Medium | Regional hosting variants raise engineering and compliance cost |
| CIAM orchestration skills gap | Restraint | Medium | SMEs especially cannot staff policy scripting and SIEM integration |
Our analysis suggests the restraints are cost-shifting rather than demand-destroying: bot-attack exposure and residency complexity push buyers toward managed services, which raises total contract value even as solution licence growth moderates.
Competition is moderately concentrated, with platform incumbents competing against specialist CIAM vendors on developer experience, regulatory breadth and total cost of ownership.
| Vendor | Primary Positioning | Notable Strength |
|---|---|---|
| Microsoft | Cloud-native identity platform | Bundling leverage across enterprise estates |
| IBM | Enterprise identity and security suite | Regulated-industry trust and integration depth |
| Okta (incl. Auth0) | Developer-first CIAM | Broad integration catalog and developer adoption |
| Ping Identity | Enterprise CIAM | Federation and hybrid deployment flexibility |
| Salesforce | Customer platform-embedded identity | Native adjacency to CRM and commerce data |
| ForgeRock, OneLogin, LoginRadius | Specialist CIAM | Agility and vertical tailoring |
Differentiation is shifting from authentication feature parity toward consent orchestration, passwordless migration paths and privacy-preserving data flows. Incumbents with bundled cloud estates enjoy procurement advantage, but specialists retain an edge where regulatory nuance and customization dominate. Our analysis suggests the strongest moat is not technology but switching cost: re-platforming identity touches every downstream application, making referenceability and migration tooling decisive.
Selection criteria should lead with migration risk, not feature checklists. Identity sits upstream of every customer journey, so a failed cutover damages revenue directly — buyers should weight reference deployments in their own vertical and region above benchmark scores.
Procurement risk concentrates in three areas: consent orchestration breadth under PSD3 and CPRA, passwordless roadmap credibility (FIDO2/passkey support with a dated migration plan), and API-layer bot mitigation that integrates with existing SIEM and fraud tooling. Vendors that treat these as roadmap items rather than shipped capabilities should be priced accordingly.
Switching costs are severe and understated in most business cases. Identity re-platforming requires application-by-application integration, identity store migration, and re-certification of audit controls — typically a multi-quarter program. Buyers should negotiate contractual exit assistance and data portability clauses at signature, not renewal.
Regulatory compliance is non-negotiable in BFSI, healthcare and public sector. eIDAS 2.0 wallet interoperability in Europe and HIPAA-grade controls in healthcare narrow the viable vendor set materially; verifying certified regional hosting and audit evidence early prevents late-stage procurement failure.
The balance of evidence favors sustained double-digit growth, but the composition of that growth matters more than the headline rate. Spend is migrating from authentication licences toward orchestration services and cloud infrastructure, which means revenue quality improves even as per-seat pricing erodes. Vendors that position as orchestration layers — not login screens — will capture disproportionate share.
The strongest counter-argument is that bundling by hyperscalers compresses specialist pricing faster than forecast, pulling the effective CAGR toward the low-teens estimate. That risk is real but concentrated in mid-market, price-sensitive accounts; regulated and federated deployments remain defensible because migration cost, not licence cost, governs the decision.
A secondary consideration: if passwordless adoption accelerates beyond current trajectories, MFA revenue — still ~44% of authentication spend — could deflate sooner than models assume, forcing repricing across the category.
Actionable strategy:
What would change this conclusion: evidence of hyperscaler CIAM bundling at zero marginal cost in mid-market, or a credible open-source alternative achieving regulated-industry certification. Either would compress the forecast toward the low-teens CAGR scenario and shift value decisively to services.
While this overview reconciles the headline estimates, precise sub-segment forecasting — particularly passwordless substitution timing and regional consent-compliance spend — requires the full dataset and vertical-level modelling.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 17.7% from 2020-2034 |
| Segmentation |
|
Estimates range from roughly 13.3 Billion to 49.9 Billion depending on scope. The narrow-to-mid definition, near 24 Billion in 2025 growing at 17-18%, is the most defensible operating figure for procurement planning.
Published CAGRs span 11.29% to 19.3%. The divergence reflects horizon length and scope breadth; near-term growth of roughly 17-18% is consistent with deal velocity and cloud migration evidence.
North America leads with about 43% of global spend. Asia-Pacific is the fastest-growing region, driven by super-app federation and embedded finance, while Europe grows on regulatory mandates.
Microsoft, IBM, Okta (including Auth0), Ping Identity and Salesforce lead, alongside specialists such as ForgeRock, OneLogin and LoginRadius. Differentiation is shifting toward consent orchestration and passwordless migration.
E-commerce expansion, rising online fraud, regulatory mandates such as PSD3 and eIDAS 2.0, passwordless authentication demand and embedded finance all push organizations to modernize external identity infrastructure.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the CIAM value chain with identity platform vendors, cloud infrastructure providers, systems integrators, managed security service providers and enterprise end users. Interviewees included VP-level identity and security owners, Heads of Digital Product, Chief Information Security Officers, and Commercial Operations Leads responsible for customer onboarding economics. Interview programs targeted organizations across BFSI, healthcare, retail and public sector to capture vertical-specific procurement behaviour.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CISOs & Identity Security Leads | 40% |
| Digital Product & CX Heads | 30% |
| Procurement & Vendor Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| Identity Platform Vendors | 40% |
| Systems Integrators & MSPs | 25% |
| Cloud Infrastructure Providers | 20% |
| Enterprise End Users | 15% |
Secondary validation draws on official multilateral and regulatory databases including UN Comtrade, WTO trade statistics, US ITC filings, Eurostat digital economy indicators, and company annual reports and SEC filings. Patent databases and published technical standards from ISO/IEC, NIST and FIDO Alliance were reviewed for authentication and identity-proofing trajectories. Regulatory texts including GDPR, CCPA/CPRA, PSD3 and eIDAS 2.0 were analyzed directly to calibrate compliance-driven demand.
Market sizing triangulates top-down and bottom-up models simultaneously. The top-down model allocates macroeconomic digital-transformation and security spend across verticals and geographies. The bottom-up model builds from vendor revenue disclosures, seat and transaction pricing, cloud consumption, and end-use deployment counts. Divergence between the two is reconciled against disclosed contract values and observed deal velocity.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up revenue and deployment triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border digital services trade and consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, filings and capability mapping | High |