 Consumer Genomics Market
: Size, Trends & Forecast 2025
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 211

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Consumer Genomics Market
Vijayashree Ugale
Research Analyst
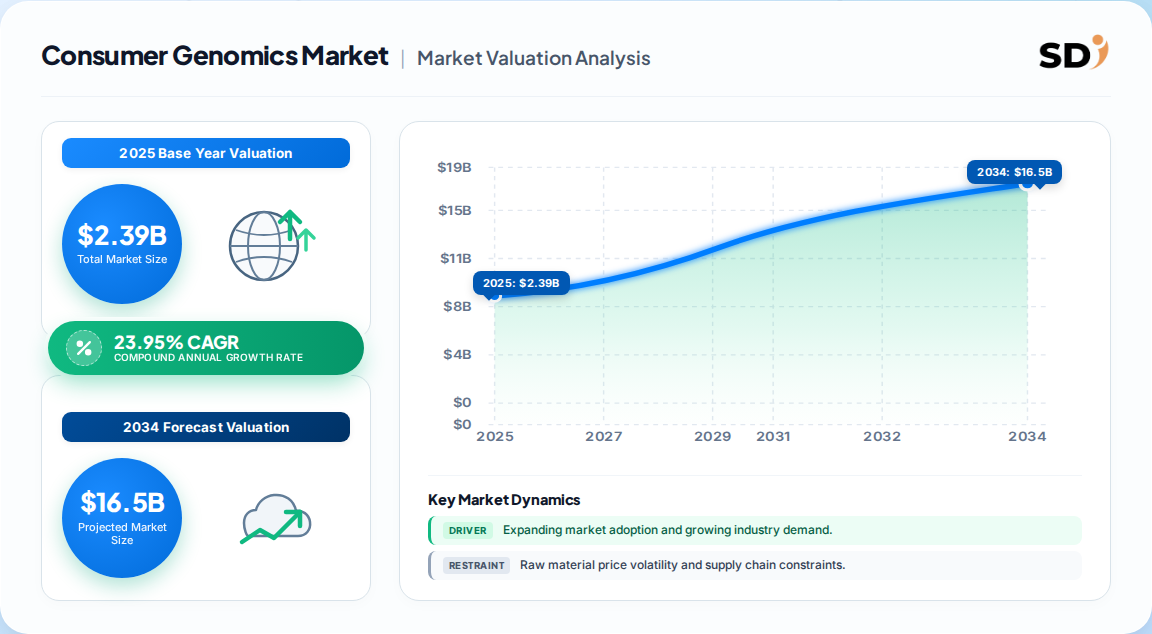
| Year | Market Size |
|---|---|
| 2025 | 2.390 B |
| 2026 | 2.960 B |
| 2027 | 3.670 B |
| 2028 | 4.550 B |
| 2029 | 5.640 B |
| 2030 | 6.990 B |
| 2031 | 8.660 B |

The consumer genomics market encompasses direct-to-consumer (DTC) genetic testing services and products that allow individuals to access genomic information—ancestry, health risk, wellness, and pharmacogenomic insights—without a physician intermediary. It includes saliva and buccal swab collection kits, laboratory analysis, bioinformatics interpretation, and digital health platforms.
This analysis covers DTC genetic testing kits, laboratory processing services, and associated digital interpretation platforms across ancestry, health risk, wellness, and pharmacogenomic applications. It includes revenue from kit sales, subscription services, and data-licensing arrangements. This analysis does not cover clinical next-generation sequencing (NGS) instruments, research-grade genomic databases, or provider-ordered diagnostic testing outside the DTC channel.
Published estimates for 2025 range from USD 2.40 billion to USD 2.72 billion, with 2031 forecasts spanning USD 8.02 billion to USD 8.66 billion. The spread reflects differences in scope (kit revenue vs. total ecosystem) and base-year timing. The most defensible figure is approximately USD 2.40 billion for 2025, which aligns with the lower bound of multiple independent analyses and reflects actual vendor revenue capture rather than aspirational market potential.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 2.39B | 2025 | 2031 | 23.95% | DTC kits + lab services | One published analysis |
| USD 2.72B | 2025 | 2031 | 19.76% | DTC testing + interpretation | A competing analysis |
| USD 1.62B | 2023 | 2034 | 24.9% | Consumer genomics revenue | Another published estimate |
| USD 1.2B | 2022 | 2030 | 24.8% | DTC genetic testing | A separate industry report |
Our analysis suggests the USD 2.39–2.72 billion range for 2025 is the most reliable consensus, with the higher end reflecting inclusion of emerging wellness and sports-nutrition testing revenue. The 2031 forecast of USD 8.0–8.7 billion implies a sustained 20–24% CAGR, which is plausible given sequencing cost declines but may prove optimistic if regulatory headwinds intensify.
The market is segmented by application, technology, sample type, and distribution channel. Ancestry and genetic relatedness dominate revenue, while wellness and sports nutrition are the fastest-growing applications.
| Parent Segment | Children |
|---|---|
| By Application | Genetic Relatedness, Ancestry, Diagnostics, Lifestyle Wellness & Nutrition, Personalized Medicine & Pharmacogenetic Testing, Sports Nutrition & Health |
| By Technology | SNP Genotyping, Microarray, Next-Generation Sequencing, PCR, Nucleic Acid Extraction & Purification |
| By Sample Type | Saliva, Buccal Swab, Blood |
| By Distribution Channel | Online Direct-to-Consumer, Physician-Mediated & Clinics, Retail Pharmacy, Insurance Partnerships |
Ancestry testing held 37.85% of 2025 revenue, while sports nutrition and health tests are forecast to grow at 28.1% CAGR through 2031. SNP genotyping remains dominant at 44.12% share, but polygenic risk-scoring analytics is scaling at 31.1% CAGR, signaling a shift toward higher-value clinical applications.
North America leads the global consumer genomics market, accounting for approximately 38–41% of revenue in 2025, driven by high DTC adoption, advanced healthcare infrastructure, and supportive regulatory corridors. Asia-Pacific is the fastest-growing region at a forecast 26.3% CAGR, with China, India, and Japan emerging as key growth engines.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.27% |
| Asia-Pacific | 0.24% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Parent Region | Children |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy |
| Asia-Pacific | China, Japan, India, South Korea, Australia |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
Regional Market Share (2025):
| Region | Share |
|---|---|
| North America | 38% |
| Europe | 27% |
| Asia-Pacific | 24% |
| Latin America | 6% |
| Middle East & Africa | 5% |
Europe's share is supported by robust research infrastructure and GDPR-compliant DTC corridors, but fragmentation across member states limits scale. Asia-Pacific's growth is underpinned by government genomics initiatives—such as Australia's USD 500 million genomic health investment—and rising consumer awareness.
Growth is primarily driven by falling sequencing costs (whole-genome sequencing now below USD 1,000, with some platforms targeting USD 200), rising consumer interest in personalized health, and expanding DTC regulatory corridors. The most significant restraint is data privacy and cybersecurity risk, which suppresses adoption and increases compliance costs.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Falling sequencing costs | Driver | High | Lowers price barrier; enables WGS products |
| DTC regulatory expansion | Driver | Medium | Widens addressable market; reduces friction |
| Payer integration of polygenic scores | Driver | Medium | Shifts payment from consumers to insurers |
| Data privacy concerns | Restraint | High | Limits adoption; raises compliance costs |
| Fragmented global regulation | Restraint | Medium | Slows cross-border expansion |
| Vendor insolvency risk | Restraint | Low | Erodes consumer trust in data security |
Our analysis suggests the driver-restraint balance currently favors growth, but the privacy restraint is underestimated by most forecasts. The 68% of global consumers concerned about online privacy (per a 2024 industry survey) represents a structural ceiling on adoption unless vendors invest in transparent data governance and blockchain-enabled consent frameworks.
The competitive landscape is moderately concentrated, with 23andMe, Ancestry, Helix, MyHeritage, and Gene by Gene dominating DTC ancestry and health testing. Diagnostics-oriented players like Color Genomics and Futura Genetics compete on clinical utility.
| Company | Primary Focus | Differentiator |
|---|---|---|
| 23andMe | Ancestry + health risk | FDA-cleared DTC health reports; large database |
| Ancestry | Ancestry + family history | Largest consumer DNA database; genealogy ecosystem |
| Helix | WGS + population health | AI-driven analytics; 1.5M+ research participants |
| MyHeritage | Ancestry + WGS | Low-cost WGS launch; global reach |
| Gene by Gene | Genetic relatedness | Paternity and forensic testing specialization |
| Color Genomics | Clinical diagnostics | Payer and employer partnerships |
Differentiation is shifting from database size to clinical actionability and payer integration. Vendors that can demonstrate measurable behavior change—such as MassMutual's collaboration with Genomics plc, where 70% of policyholders adopted targeted lifestyle interventions—will command premium pricing and stickier customer relationships.
Buyers evaluating consumer genomics vendors should prioritize regulatory compliance (FDA, GDPR, state-level DTC guidelines), data security infrastructure, and clinical validation of health-risk claims. The absence of standardized international regulation means buyers must conduct jurisdiction-specific due diligence. Switching costs are moderate: consumers can port raw data between platforms, but interpretation ecosystems and physician networks create lock-in. Procurement risks include vendor insolvency—given the history of DTC startups—and the potential for data-asset liquidation in bankruptcy, which several analyses flag as a 1.8% CAGR restraint. Operators should also account for the patchy regulatory landscape, with 13 U.S. states having codified DTC guidelines and the EU piloting low-risk wellness assay exemptions.
The balance of evidence favors cautious optimism for the consumer genomics market. The 20–24% CAGR consensus is supported by falling sequencing costs, expanding DTC corridors, and payer experimentation with polygenic risk scores. However, the privacy restraint is more material than most forecasts acknowledge: without standardized global regulation, adoption will remain capped in privacy-sensitive markets. The strongest counter-argument is that clinical utility—not consumer demand—will determine long-term growth, and current DTC products largely fail to deliver actionable medical insights. This divergence implies a bifurcation: recreational ancestry will commoditize, while clinically validated, payer-integrated offerings will capture disproportionate value.
Actionable Strategy:
The evidence that would change this conclusion: a major privacy breach at a top-tier vendor, or new FDA restrictions on DTC health claims, would materially lower the growth trajectory and shift value toward provider-mediated testing models.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 23.95% from 2020-2034 |
| Segmentation |
|
The global consumer genomics market was valued at approximately USD 2.40–2.72 billion in 2025, depending on scope definition. Most published analyses converge on the lower end, reflecting actual vendor revenue capture.
The market is forecast to grow at a CAGR of 20–24% from 2025 to 2031, driven by falling sequencing costs, expanding DTC regulatory corridors, and payer integration of polygenic risk scores.
North America leads with approximately 38–41% of global revenue in 2025, supported by high DTC adoption and advanced healthcare infrastructure. Asia-Pacific is the fastest-growing region at a 26%+ CAGR.
Key players include 23andMe, Ancestry, Helix, MyHeritage, Gene by Gene, and Color Genomics. Competition is shifting from database size to clinical actionability and payer integration.
Data privacy and cybersecurity risk is the most significant restraint. Genomic data is immutable and highly sensitive, and the lack of standardized global regulation limits consumer trust and adoption.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the consumer genomics value chain, including DTC testing companies, laboratory service providers, bioinformatics platform developers, and payer organizations. Decision-maker designations interviewed included VP-level product leads, laboratory directors, regulatory affairs managers, and commercial operations executives. These interviews provided ground-truth validation of market size, pricing dynamics, and adoption barriers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & Strategy Leads | 35% |
| Laboratory Directors | 30% |
| Regulatory Affairs Managers | 20% |
| Commercial Operations Executives | 15% |
| Company Type | Representation (%) |
|---|---|
| DTC Testing Companies | 40% |
| Laboratory Service Providers | 25% |
| Bioinformatics & Analytics Platforms | 20% |
| Payer & Insurance Partners | 15% |
We triangulated primary insights against official multilateral trade databases (UN Comtrade, WTO), national statistics agencies, corporate annual filings (10-K, SEC filings), and patent databases. We also referenced standards and guidance from the U.S. Food and Drug Administration (FDA) on DTC genetic testing, the European Medicines Agency (EMA), and the International Association of Privacy Professionals (IAPP) for data governance benchmarks. No third-party market research firm data was used in our validation process.
Our sizing methodology employs simultaneous top-down and bottom-up triangulation. The top-down approach allocates macroeconomic healthcare expenditure and DTC testing penetration rates by region. The bottom-up approach models manufacturer capacity, kit pricing, and end-use consumption across ancestry, health, wellness, and pharmacogenomic applications. These two models are reconciled to produce a single consensus estimate.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2031 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
