 Fitness App Market
 Outlook 2026: Size, Growth & Vendors
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 225

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Fitness App Market
Vijayashree Ugale
Research Analyst

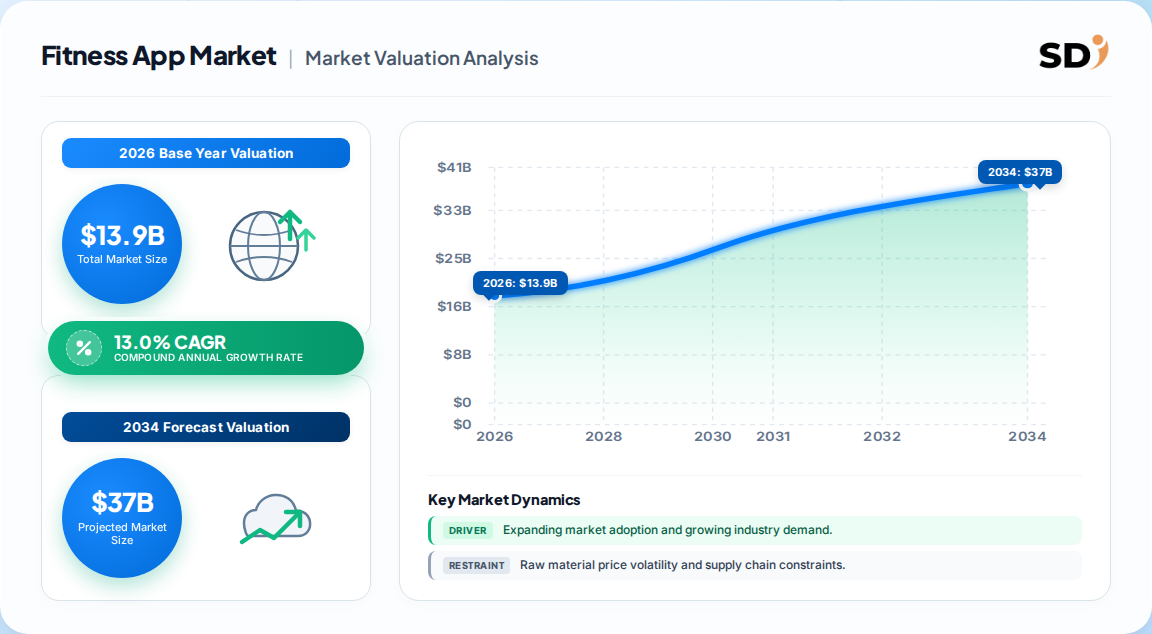
| Year | Market Size |
|---|---|
| 2026 | 13.90 B |
| 2027 | 15.70 B |
| 2028 | 17.70 B |
| 2029 | 20.00 B |
| 2030 | 22.60 B |
| 2031 | 25.60 B |
| 2032 | 28.90 B |

The fitness app market encompasses software applications for smartphones, tablets, and wearables that detect, track, analyze, and share vitality and fitness achievements. It covers exercise and weight loss, diet and nutrition, and activity tracking apps, monetized through subscriptions, freemium upgrades, and in-app purchases — excluding advertising and app-download revenue.
This report covers B2C fitness applications spanning exercise and weight loss, diet and nutrition, activity tracking, and wellness coaching across iOS, Android, and wearable platforms. Revenue includes paid app subscriptions and in-app purchases only. This analysis does not cover nutrition apps as a standalone category, digital therapeutics, connected biosensors, fitness trackers hardware, or B2B/C2C revenue streams.
The market was valued at US$9.12 billion in 2026 by one published estimate, while competing analyses place 2026 revenue between US$13.6 billion and US$15.4 billion. The divergence reflects scope differences in app categories and revenue definitions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| US$9.12B | 2026 | 2031 | 11.12% | B2C fitness apps; paid apps and in-app purchases only | Statista Market Insights |
| US$13.9B | 2026 | 2033 | 13.4% | Exercise, diet, activity tracking; all platforms | One published estimate |
| US$15.35B | 2026 | 2031 | 13.01% | Digital fitness apps incl. meditation and mind-wellness | One published estimate |
| US$13.56B | 2026 | 2034 | 13.0% | Fitness apps by type and device | One published estimate |
Our analysis suggests the US$13.6–15.4 billion range is most defensible for total fitness app revenue because it captures the full app-type taxonomy. The US$9.12 billion figure likely excludes wellness and meditation adjacencies, making it a conservative lower bound. Buyers should anchor on the ~13% CAGR consensus rather than any single base value.
The market segments primarily by app type, platform, device, subscription model, and user demographic, with exercise and weight loss leading at 53.7% share and freemium emerging as the fastest-growing monetization model.
| Parent Segment | Children |
|---|---|
| By Type | Exercise & Weight Loss, Diet & Nutrition, Activity Tracking, Wellness Coach |
| By Platform | iOS, Android, Web-based |
| By Device | Smartphones, Tablets, Wearable Devices |
| By Subscription Model | Free, Freemium, Paid |
| By User Demographic | Adults, Teenagers, Seniors, Children |
This segmentation matters because the fastest-growing cells — wearables (20.1% CAGR), freemium (14.9% CAGR), and healthcare provider/insurer end users (14.8% CAGR) — are where margin expansion is concentrating. Vendors anchored only in smartphone-based paid subscriptions face the steepest competitive pressure.
North America leads the fitness app market with 38.5–39.8% revenue share in 2025, driven by high smartphone penetration, strong fitness culture, and insurer-funded wellness programs. Asia-Pacific is the fastest-growing region at 14.7–20.4% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.24% |
| Asia-Pacific | 0.27% |
| Latin America | 0.06% |
| Middle East & Africa | 0.04% |
| Region | Revenue Share (2025) | Growth Outlook |
|---|---|---|
| North America | 38.5–39.8% | Mature; insurer/employer-funded growth |
| Europe | ~24% | Moderate; GDPR compliance constrains acquisition |
| Asia-Pacific | ~27% | Fastest CAGR (14.7–20.4%) |
| Latin America | ~6% | Emerging; smartphone-led adoption |
| Middle East & Africa | ~4% | Nascent; infrastructure-limited |
North America(USA, Canada, Mexico), Europe(Germany, UK, France, Italy, Spain), Asia-Pacific(China, Japan, India, South Korea, Australia), Latin America(Brazil, Mexico, Argentina), Middle East & Africa(Saudi Arabia, UAE, South Africa)
Our analysis suggests Asia-Pacific's growth premium is underappreciated: with 27% share but the highest CAGR, it will account for the majority of incremental revenue through 2031. Vendors with North America-only distribution will cede share.
Growth is driven by AI personalization, wearable integration, insurer and employer subsidies, and rising health consciousness, while data-privacy regulation, user churn, and acquisition-cost inflation are the primary restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| AI voice-coach differentiation | Driver | High | Personalized coaching lifts engagement and premium conversion |
| Insurer/employer incentives | Driver | High | Subsidies reduce churn; multiyear contracts |
| Wearable penetration | Driver | High | Continuous data loops improve retention |
| GLP-1 program integration | Driver | Medium | Extends engagement beyond 90-day churn horizon |
| Data-privacy regulation | Restraint | High | GDPR/DMA compliance raises cost and limits targeting |
| Post-pandemic app fatigue | Restraint | Medium | Retention drop-off elevates CAC |
| Free-app competition | Restraint | High | Pricing pressure caps premium revenue |
The balance favors growth: driver impacts (+2.8% AI, +2.5% insurer incentives) outweigh restraint drags (-1.8% privacy, -1.5% churn). This implies the market's trajectory is structurally sound, but margin accrues to vendors who can convert subsidized distribution into clinical-grade engagement.
The market is moderately concentrated, with MyFitnessPal, Fitbit, Strava, Nike Training Club, Samsung Health, and Google Fit leading through distinct moats in nutrition data, wearable ecosystems, social networks, and free content libraries.
| Vendor | Key Features | Scale Indicator | Differentiation |
|---|---|---|---|
| MyFitnessPal | 14M+ food database, nutrition tracking | Category leader | Nutrition data moat |
| Fitbit | Wearable integration, health metrics | 50M+ downloads | Hardware-software lock-in |
| Strava | Social features, Athlete Intelligence | Category leader | Social network effects |
| Nike Training Club | Free workout library, expert guidance | 10M+ downloads | Brand and free content |
| Samsung Health | Smartphone-native tracking | Embedded base | Device pre-installation |
| Google Fit | Activity tracking, open APIs | Embedded base | Platform ecosystem |
Differentiation is shifting from content libraries to data moats: vendors with proprietary behavioral datasets feed superior AI personalization, raising switching costs. Free-content players like Nike face monetization pressure, while ecosystem players (Samsung, Google) benefit from pre-installation distribution.
Selection criteria should prioritize clinical validation, wearable API depth, and insurer integration readiness over raw content volume. Procurement risk concentrates in data-privacy compliance (GDPR, DMA, ADPPA) and vendor lock-in through proprietary sensor pipelines.
Switching costs rise steeply once a vendor integrates with a user's wearable ecosystem and employer wellness platform; operators should model multiyear contract value, not monthly churn. Regulatory compliance is non-negotiable for insurer-funded distribution — vendors lacking HIPAA-grade infrastructure are excluded from the fastest-growing end-user segment. Buyers should also scrutinize tracking accuracy claims, as clinical-grade gaps invite regulatory scrutiny and erode trust.
The balance of evidence favors a ~13% CAGR consensus over the conservative 11.12% figure, because the higher estimates capture wellness adjacencies and insurer-funded channels that are expanding faster than core app subscriptions. The strongest counter-argument is that app fatigue and free-app competition could compress paid conversion, pulling growth toward the lower bound — but insurer and employer subsidies structurally offset consumer churn.
Our analysis suggests the decisive strategic variable is distribution, not product. Vendors that secure insurer and employer channels convert volatile B2C churn into multiyear contracts, while AI voice-coaching raises engagement enough to justify premium tiers. The GLP-1 integration wave is a second-order accelerant that extends engagement cycles well beyond the traditional 90-day horizon.
Actionable strategy for operators and investors:
Evidence that would change this conclusion: a sustained decline in wearable shipments, regulatory action restricting health-data use in insurer programs, or freemium conversion rates falling below 3% would favor the conservative 11.12% scenario.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 13.0% from 2020-2034 |
| Segmentation |
|
Estimates range from US$9.12 billion to US$15.35 billion for 2026, depending on scope. The consensus midpoint is approximately US$13.9 billion, reflecting ~13% annual growth through the early 2030s.
Published CAGRs range from 11.12% to 13.4% for 2026–2031/2033. Our analysis favors the ~13% consensus, driven by AI personalization, wearable integration, and insurer-funded wellness programs.
North America leads with 38.5–39.8% revenue share in 2025. Asia-Pacific is the fastest-growing region at 14.7–20.4% CAGR and will capture most incremental revenue through 2031.
MyFitnessPal, Fitbit, Strava, Nike Training Club, Samsung Health, and Google Fit lead the market through nutrition data, wearable ecosystems, social networks, and device pre-installation distribution.
Exercise and weight loss holds the largest share at 53.7% in 2025. Smartphones remain the dominant device (66.7%), while wearable devices grow fastest at approximately 20.1% CAGR.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews across the fitness app value chain: app developers and publishers, wearable device manufacturers, health insurer program managers, corporate wellness administrators, and app-store distribution platforms. Decision-maker designations interviewed include VP of Product, Head of Growth and Monetization, Chief Privacy Officer, and Commercial Partnerships Leads. Interviews probe monetization strategy, churn dynamics, clinical validation requirements, and channel economics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & Growth Leads | 40% |
| Privacy & Regulatory Officers | 25% |
| Commercial Partnerships Leads | 20% |
| Clinical & Data Science Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| App Developers & Publishers | 40% |
| Wearable Device Manufacturers | 25% |
| Health Insurers & Corporate Wellness | 20% |
| App-Store & Distribution Platforms | 15% |
We validate findings against official multilateral and regulatory databases, including UN Comtrade for digital services trade flows, WTO digital-trade statistics, US ITC reports, and Eurostat digital-health indicators. Corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit standards bodies — including ISO health-informatics standards and HL7 interoperability frameworks — anchor vendor and technology benchmarks. No third-party market-research publisher data is used as a validation source.
We apply simultaneous top-down allocation (macroeconomic indicators, smartphone and wearable penetration, healthcare spending) and bottom-up modeling (developer revenue, subscription pricing, end-user consumption) to triangulate market size. Forecasts use S-curve adoption functions and exponential trend smoothing appropriate to digital products.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |