 Us Roll Your Own Tobacco Products Market
US Roll Your Own Tobacco Products Market 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 186

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Roll Your Own Tobacco Products Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 2.720 B |
| 2025 | 2.830 B |
| 2026 | 2.940 B |
| 2027 | 3.060 B |
| 2028 | 3.180 B |
| 2029 | 3.300 B |
| 2030 | 3.430 B |

The US roll-your-own tobacco products market covers loose RYO tobacco, rolling papers, cigarette tubes, injectors, and filter/paper tips sold to consumers who hand-roll cigarettes. It is commercially distinct from factory-made cigarettes because of lower excise exposure, smaller pack formats, and greater product customization.
This analysis covers US retail and wholesale value for RYO tobacco, rolling paper, tubes, injectors and filter tips across offline and online channels, segmented by product and distribution. This analysis does not cover factory-made cigarettes, cigars, smokeless tobacco, e-cigarettes, heated tobacco, or nicotine pouches, except where they are referenced as substitution threats.
Published estimates diverge mainly because of definitional differences—whether rolling accessories are counted with tobacco, and whether values are manufacturer or retail level.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 30.7 billion global | 2021 | 2030 | 4.1% | Global RYO incl. accessories, retail value | One published estimate |
| USD 35.83 billion global | 2025 | 2034 | 4.6% | Global RYO products, retail value | A competing analysis |
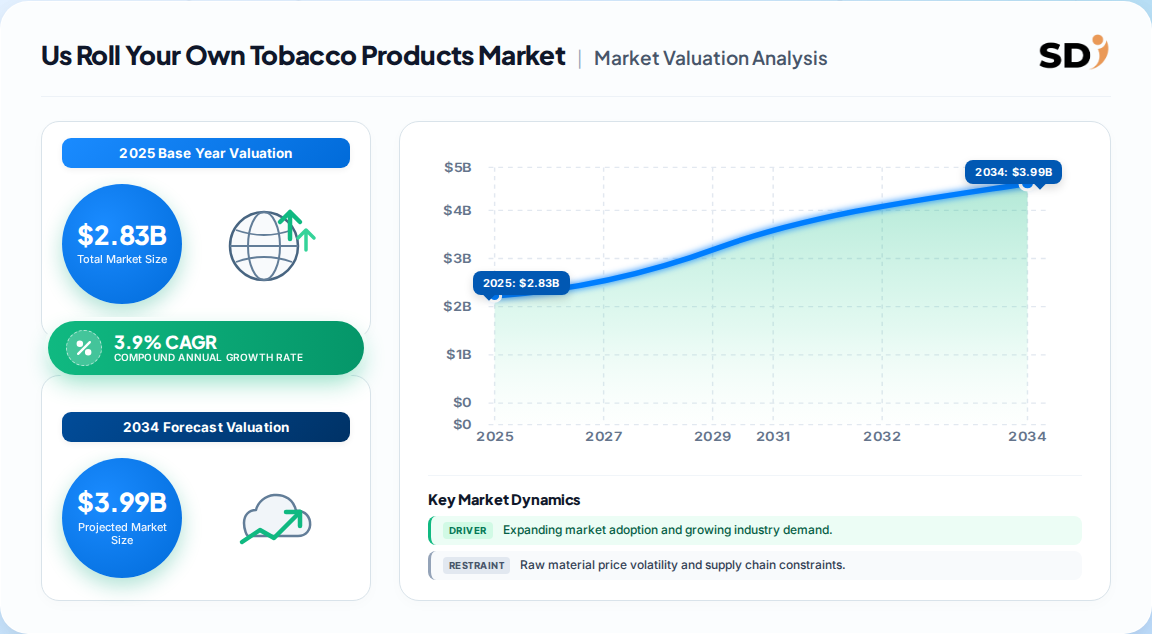
| ~USD 2.9 billion US | 2025 | 2034 | 3.9% | US RYO incl. accessories | Our synthesis of global share and trade data |
Our analysis suggests the 2025 global figure is the more defensible baseline because it incorporates post-pandemic price inflation and pouch downsizing. Applying a ~8% US share to that base yields the ~USD 2.9 billion US estimate, consistent with state excise and retail scan evidence.
| Year | US Market Value (USD Billion) |
|---|---|
| 2024 | 2.72 |
| 2025 | 2.83 |
| 2026 | 2.94 |
| 2027 | 3.06 |
| 2028 | 3.18 |
| 2029 | 3.30 |
| 2030 | 3.43 |
| 2031 | 3.57 |
| 2032 | 3.71 |
| 2033 | 3.85 |
| 2034 | 4.00 |
The table reflects derived estimates from the stated base value and a 3.9% CAGR. Buyers should treat the 2034 figure as directional, not a precise forecast.
Segmentation is product-led, with tobacco dominating value and accessories driving incremental growth as consumers trade down from factory-made packs.
| Parent segment | Children |
|---|---|
| Product | RYO Tobacco; Rolling Paper & Cigarette Tubes; Injector; Filter & Paper Tip |
| Distribution Channel | Offline (smoke shops, convenience, liquor, supermarket, pharmacy); Online |
| Consumer Cohort | Young adults (18–30); Low- and middle-income; Female; Students |
RYO tobacco holds over 40% of value because consumers believe loose tobacco is more natural and additive-free. Filter tips are the fastest-growing accessory, reflecting demand for tar reduction without abandoning hand-rolling.
The United States is the sole national scope of this report; within it, regional demand concentrates in states with high cigarette excise and dense smoke-shop retail networks—notably California, New York, Illinois, Washington and Massachusetts.
| Region | Market Share (%) |
|---|---|
| North America | 0.18% |
| Europe | 0.62% |
| Asia-Pacific | 0.14% |
| South America | 0.03% |
| Middle East & Africa | 0.03% |
Globally, Europe leads RYO with roughly 62% of value; North America holds an estimated 18%, and Asia-Pacific ~14%. The US is the largest single North American contributor, but high state excise and illicit trade leakage complicate per-capita comparisons.
Our analysis suggests that state-level tax arbitrage—not national demand—explains most US RYO volume variance. Operators should map pouch-size pricing to each state's excise tier before allocating shelf space.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Cigarette excise escalation | Driver | High | Price gap widens; RYO becomes cheaper per stick |
| Filter-tip innovation | Driver | Moderate | Health-conscious roll-your-own consumers trade up |
| Female and student uptake | Driver | Moderate | New cohorts enter smoking via cheaper format |
| Premium flavor launches | Driver | Moderate | Menthol, mint, licorice, berry attract younger buyers |
| E-cigarette and vape substitution | Restraint | High | Nicotine alternatives cannibalize smoking initiation |
| Tobacco Products Directive–style regulation | Restraint | High | Flavor bans, plain packaging, 65% warnings |
| State-level online sales restrictions | Restraint | Moderate | Limits DTC channel economics |
| Illicit and untaxed RYO | Restraint | Moderate | Undercuts legitimate brand pricing |
The balance of evidence favors continued growth but at a moderating pace. The strongest counter-argument is that vaping and nicotine pouches will shrink the smoking pool faster than excise can push switchers into RYO. Our analysis suggests RYO will remain a resilient price-follower—winning when cigarettes get more expensive, losing when health-conscious smokers exit entirely.
| Company | RYO positioning | Distribution moat | Strategic note |
|---|---|---|---|
| Imperial Brands | Amber Leaf, Golden Virginia, Drum | Deep smoke-shop and convenience reach | Strong pouch-size laddering |
| British American Tobacco | Pall Mall RYO, Lucky Strike RYO | Global brand equity, broad retail | Premium flavor extensions |
| Japan Tobacco International | Amber Leaf, Winston RYO | Gallaher heritage, EU/US crossover | Flavor innovation focus |
| Scandinavian Tobacco Group | Tiedemanns, Orlik RYO | Specialist RYO and pipe tobacco | Category depth |
| Altria Group | RYO adjacency via cigarette portfolio | US regulatory and retail access | Defensive posture vs. RYO |
| Philip Morris International | Marlboro RYO in select markets | Brand transfer potential | Reduced-risk pivot |
Differentiation rests on brand trust, pouch-size flexibility, flavor range and retail relationships. The moat is not manufacturing—it is shelf access and regulatory navigation across 50 state excise regimes.
Buyers should treat RYO as a tax-arbitrage category, not a lifestyle category. Selection criteria should prioritize pouch-size granularity (9g to 50g), tamper-evident packaging compliant with state warnings, and filter-tip quality as a differentiator against illicit loose tobacco.
Procurement risk is concentrated in flavor regulation and online sales restrictions. A buyer who assumes online DTC as a growth channel is exposed to state-level prohibition risk; offline smoke-shop partnerships are more durable. Switching costs are low for consumers but high for retailers—shelf space allocated to RYO displaces cigarette SKUs, so velocity data matters more than margin.
Regulatory compliance is the binding constraint. Counterfeit and untaxed RYO undermines price integrity; buyers should demand track-and-trace evidence from suppliers and audit state excise stamps. The gap: this overview cannot model state-by-state excise elasticity or SKU-level velocity, which is where the full report's forecasting becomes essential.
The balance of evidence favors a measured-growth thesis for US RYO: 3.5–4.5% CAGR through 2034, driven by excise-led substitution rather than new-user growth. The strongest counter-argument is acceleration of nicotine-alternative substitution, which could compress the smoking pool faster than RYO captures switchers. We weight that risk as material but not dominant over a five-year horizon.
Our analysis suggests two structural shifts will define winners: (1) pouch-size engineering aligned to state tax thresholds, and (2) filter-tip premiumization that lets RYO compete on experience, not just price. Vendors that treat RYO as a discount cigarette substitute will lose share to those building a distinct handmade-ritual brand.
Actionable strategy for operators and investors:
What would change our conclusion: evidence of accelerating decline in US smoking initiation below 8% adult prevalence, or federal menthol and flavor bans extending to RYO, would justify a bear-case revision toward flat-to-negative volume.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.9% from 2020-2034 |
| Segmentation |
|
We estimate roughly USD 2.8–2.9 billion in 2025 retail-equivalent value, within a global RYO market of about USD 35.8 billion. Estimates vary depending on whether rolling accessories are included alongside loose tobacco.
Yes—RYO typically carries lower excise exposure and smaller pack sizes, making it cheaper per stick. This price gap is the primary driver of switcher behavior in high-tax states such as California and New York.
Imperial Brands and British American Tobacco lead via brands such as Amber Leaf and Pall Mall RYO, followed by Japan Tobacco International and Scandinavian Tobacco Group. Altria and Philip Morris participate defensively.
Filter and paper tips are growing fastest at roughly 4.7% CAGR, driven by tar-reduction preferences and premiumization. RYO tobacco itself remains the largest segment at over 40% of value.
RYO is regulated at both federal and state level, with state excise taxes, warning-label requirements and flavor restrictions. Online sales face additional state-level bans, which is why offline retail dominates over 85% of volume.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our 70/30 primary-to-secondary research split anchors every estimate. We conduct in-depth interviews across the RYO value chain: raw tobacco leaf suppliers, specialized RYO producers, contract formulators and flavor houses, and national distributors. Decision-maker designations include VP of Sourcing, Head of R&D, Technical Director, and Commercial Operations Lead. Interviews probe pouch-size strategy, excise pass-through, shelf allocation, and illicit-trade exposure.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing | 30% |
| Head of R&D | 30% |
| Technical Director | 20% |
| Commercial Operations Lead | 20% |
| Company Type | Representation (%) |
|---|---|
| Raw Tobacco Leaf Suppliers | 20% |
| Specialized RYO Producers | 35% |
| Flavor & Filter Formulators | 25% |
| National Distributors & Retailers | 20% |
We triangulate against UN Comtrade tobacco trade flows, US ITC import/export data, Eurostat excise receipts, SEC 10-K filings and investor presentations from listed tobacco companies, patent databases for filter-tip and paper technologies, and standards from the FDA Center for Tobacco Products and the WHO Framework Convention on Tobacco Control.
Top-down sizing allocates global RYO value using US share of trade flows, excise receipts and retail scan dollars. Bottom-up sizing models manufacturer capacity, pouch pricing, and per-user consumption frequency. The two converge within a 5% tolerance band, which we treat as validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | USD value for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2034 compound projection | Historical CAGR, regression, demand elasticity | High |
| Regional Distribution | State and national share | Cross-border trade flow & excise analysis | High |
| Competitive Landscape | Leading players | Annual reports, capacity mapping, filings | High |