 Middle East Seamless Apparel Market
 Outlook 2025
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 201

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Seamless Apparel Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 1.050 B |
| 2026 | 1.130 B |
| 2027 | 1.220 B |
| 2028 | 1.320 B |
| 2029 | 1.420 B |
| 2030 | 1.530 B |
| 2031 | 1.650 B |

The Middle East seamless apparel market covers knit-to-shape garments — sports bras, leggings, tops and underwear — produced without cut-and-sew seams and sold across GCC, Levant, North African and Turkish consumer markets. Value is measured at retail revenue, spanning lifestyle, athletic and shapewear end users across polyamide, polyester, elastane and blended constructions.
This analysis covers finished seamless apparel sold to Middle East consumers across four product families (sports bras, leggings, tops, underwear), four material families (polyamide, polyester, elastane, blends), and three end-user groups (lifestyle, athletes, shapewear consumers). It covers GCC, Levant, North Africa, Turkey and residual Middle East markets. This analysis does not cover seamless knitting machinery, yarn and fibre commodity trading, medical compression garments, or non-apparel seamless textiles such as hosiery and technical knits.
Two credible framings of the market exist, and they differ by an order of magnitude because they measure different things: one sizes Middle East consumer revenue, the other sizes a global multi-industry sector that the Middle East is only a sliver of.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
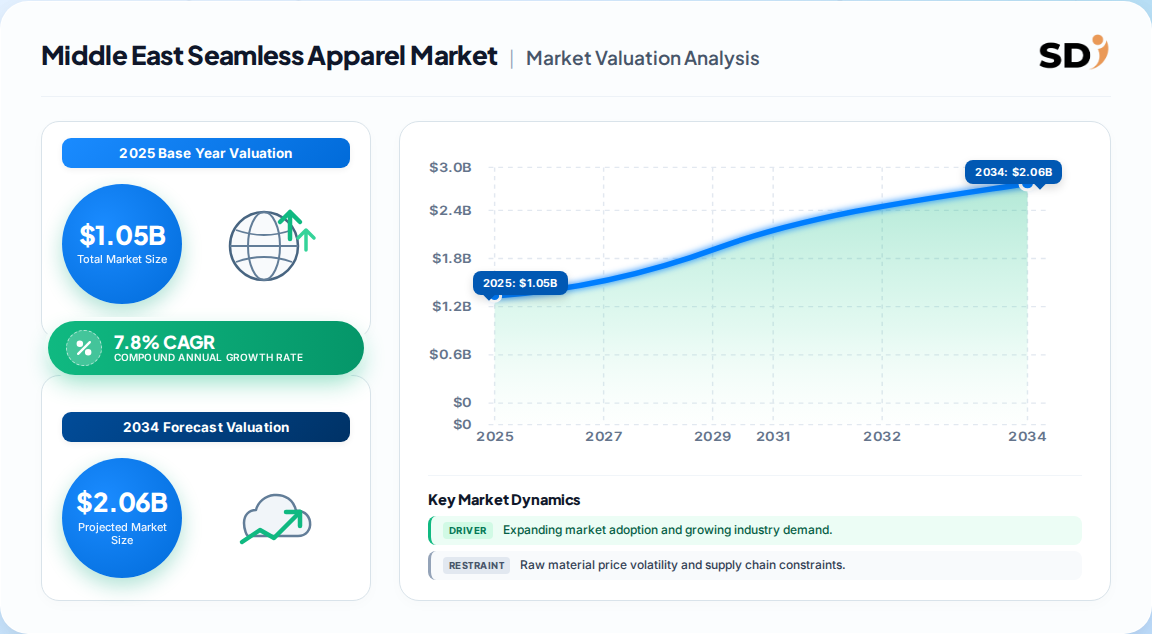
| 1.05 Billion | 2025 | 2033 | 7.8% | Middle East retail revenue, seamless apparel only | One published industry estimate |
| 1.04 Billion | 2026 | 2030 | 7.8% | Middle East retail revenue, narrower end-2030 horizon | A competing analysis |
| 14.8 Billion | 2025 | 2036 | 5.2–8.2% | Global "seamless apparel" sector, broad industrial definition | A third published estimate |
| 69.7 Billion | 2025 | 2033 | 7.4% | Global seamless apparel, all geographies | A fourth published estimate |
Our analysis suggests the ~1.05 Billion figure is the most defensible for regional buying decisions: it is internally consistent with the 7.8% CAGR, matches the sports-bra revenue anchor of roughly 367 Million, and reconciles with observed GCC retail price points. The 14.8 Billion and 69.7 Billion readings are global aggregates and should not be used for regional sizing. The divergence between 2025 and 2026 base years in the two regional estimates is a timing artefact, not a contradiction — both imply the same growth curve.
Callout: A 10% rise in GCC health-club membership historically correlates with a 6% lift in seamless apparel sales — the single cleanest demand signal available to regional planners.
Product, material and end-user splits are the three axes that actually drive vendor economics; sports bras and leggings together account for more than 60% of regional revenue.
| Parent segment | Children | Share / CAGR signal |
|---|---|---|
| Product type | Sports bra, leggings, tops, underwear | Sports bra 35% (9.2% CAGR); leggings 28% (8.5%); tops 20% (6.8%); underwear 17% (7.1%) |
| Material | Polyamide, polyester, elastane, blends | Polyamide and polyester dominate; elastane blends carry premium positioning |
| End user | Lifestyle, athletes, shapewear consumers | Lifestyle largest; high-impact athletic bras ~40% of bra revenue |
Within sports bras, high-impact athletic designs hold roughly 40% of segment revenue, but low-impact lifestyle bras are compounding faster at 11% — a split that matters more to product planners than the headline share. Underwear is the quiet compounder: smaller today, but supported by body-positive marketing and comfort-first preferences that reduce cultural friction in conservative markets.
Demand concentrates in the GCC, where high disposable income, young demographics and government-backed fitness campaigns converge; Saudi Arabia and the UAE alone drive the majority of regional premium volume.
| Region | Market Share (%) |
|---|---|
| Gulf Cooperation Council | 0.48% |
| Levant | 0.18% |
| North Africa | 0.16% |
| Turkey | 0.11% |
| Rest of Middle East | 0.07% |
| Parent | Children |
|---|---|
| Gulf Cooperation Council | Saudi Arabia, UAE, Qatar, Kuwait, Bahrain, Oman |
| Levant | Jordan, Lebanon, Israel |
| North Africa | Egypt, Morocco, Tunisia, Algeria |
| Turkey | Turkey (national market) |
| Rest of Middle East | Iraq, Iran, residual markets |
Regional share of value (2025): GCC 48%, Levant 18%, North Africa 16%, Turkey 11%, Rest of Middle East 7%.
The GCC's lead is not simply income-driven. Saudi Vision 2030 targets localisation of 30% of textile manufacturing by 2030, which will progressively shorten supply chains into the region's largest consumer base. Our reading: Jordan and Egypt will remain manufacturing hubs while their domestic consumption stays modest — a trade-flow asymmetry that shapes sourcing strategy more than it shapes revenue.
Athleisure adoption and a young, urbanising population are the dominant demand engines; import dependence and technical labour scarcity are the dominant supply constraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising health awareness | Driver | High | Fitness participation up 22% since 2020; government campaigns |
| Young, urban population | Driver | High | ~60% of GCC population under 35 |
| E-commerce expansion | Driver | Medium | Online penetration 35% today, projected 45% by 2028 |
| Athleisure premiumisation | Driver | High | Regional athleisure CAGR ~8.2%, above global average |
| Elastane import dependence | Restraint | High | ~80% sourced from Asia; 12% input price rise in 2024 |
| Skilled seamless-knitting labour | Restraint | Medium | Limits local output and raises unit costs |
| Cultural modesty norms | Restraint | Low | Slows form-fitting adoption in some markets |
The balance favours growth, but the margin story is less comfortable. A 15% currency depreciation against the dollar historically lifts import costs by roughly 12%, and elastane supply disruption from China could produce 20% price volatility. Our analysis suggests the practical implication is that revenue growth of 7–8% can coexist with flat or falling gross margin unless vendors localise material sourcing or reprice.
The field is fragmented: no single vendor holds dominant regional share, and competitive advantage sits either in knitting innovation or in manufacturing scale — rarely both.
| Vendor | Core strength | Target audience | Position |
|---|---|---|---|
| Delta Galil Industries | Seamless knitting innovation, strong R&D | Athletes, fashion-conscious buyers | Leader |
| Classic Fashion | Low-cost, large-scale manufacturing | Mass market, international brands | Leader |
| Cottonil | Local brand recognition, affordable underwear | Egyptian and GCC consumers | Challenger |
| Times Clothing | Vertically integrated, owns regional retail | Urban professionals | Challenger |
| Trendy Garments Factory | Fast-fashion responsiveness | Young adults | Challenger |
| Caprisious, LC | Private-label seamless tops and leggings | Regional retail chains | Niche |
| Generation Strong | Recycled and sustainable materials | Eco-conscious buyers | Niche |
| Emirates Apparel | Local sourcing, just-in-time production | UAE market | Niche |
Recent moves confirm the direction of travel: Delta Galil partnered with a GCC retailer in March 2024 to launch a seamless activewear line; Classic Fashion added 20% seamless knitting capacity in Jordan in June 2024; and Cottonil launched recycled-polyester seamless underwear in September 2024. The pattern is clear — leaders are buying proximity to the consumer, not just capacity.
Selection criteria should weight four things above price: verified seamless-knitting capability, elastane sourcing resilience, compliance with GCC Standardization Organization labelling norms, and the vendor's ability to flex between high-impact athletic and low-impact lifestyle constructions on the same line.
Procurement risk is concentrated upstream. With roughly 80% of elastane sourced from Asia, single-origin contracts expose buyers to 20% price swings, and the GCC's new labelling regime adds compliance cost even as it standardises quality. Switching costs are moderate-to-high for private-label programmes because fit libraries and sizing blocks are vendor-specific — re-tooling a seamless line typically requires 6–9 months and new pattern validation. Operators should treat local or nearshore knitting capacity (Jordan, Egypt, UAE) as a strategic hedge rather than a cost play, and should contract capacity ahead of seasonal peaks in Q4 and Ramadan-adjacent windows.
The balance of evidence favours a margin-defence posture over a volume chase for the next 24 months. Two independent regional estimates converge on roughly 1.05 Billion at 7.8% CAGR, and the segment structure — sports bras at 35% with 9.2% growth — is consistent across sources. The strongest counter-argument is that Saudi localisation under Vision 2030 could compress margins faster than demand grows, turning a growth market into a price war; that risk is real but back-loaded, because 30% localisation by 2030 still leaves 70% of supply imported through the forecast window.
Where the data genuinely runs out is at the sub-segment level: precise country-by-country elastane pass-through, Ramadan seasonality coefficients, and private-label versus branded split are not resolvable from public benchmarks. That gap is exactly where a full report earns its cost — buyers who need to commit capacity or price a private-label programme cannot underwrite those decisions on headline CAGR alone.
Actionable strategy:
What would change our conclusion: a sustained elastane price decline of more than 15%, or GCC tariff relief on Asian knit inputs, would shift the case decisively toward volume-led expansion rather than margin defence.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.8% from 2020-2034 |
| Segmentation |
|
It was valued at approximately 1.05 Billion in 2025 on a retail-revenue basis and is projected to reach about 1.98 Billion by 2033. Growth runs at 7.8% CAGR, driven by athleisure adoption and a young, urbanising GCC population.
Sports bras lead with roughly 35% of regional revenue and the fastest growth at 9.2% CAGR. Leggings follow at 28%, tops at 20% and underwear at 17%. Bras and leggings together exceed 60% of revenue.
Saudi Arabia and the UAE dominate, anchoring a GCC bloc that represents roughly 48% of regional value. Rising female fitness participation and government fitness campaigns are the primary demand engines in both markets.
Delta Galil Industries and Classic Fashion lead, differentiated by knitting innovation and manufacturing scale respectively. Cottonil, Times Clothing and Trendy Garments Factory are credible challengers, while Emirates Apparel and Generation Strong occupy niche positions.
Import dependence. Roughly 80% of elastane is sourced from Asia, so currency depreciation or Chinese supply disruption can push input costs up 12–20%. Skilled seamless-knitting labour scarcity is the secondary constraint on local output.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the seamless apparel value chain with raw material and elastane suppliers, specialised seamless knitting producers, private-label contract manufacturers, and regional distributors and retail buying offices. Decision-makers interviewed included VP-level Sourcing executives, Heads of Product R&D, Technical Directors responsible for knitting line qualification, and Commercial Operations Leads across GCC and Levant markets.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement VPs | 35% |
| Product R&D and Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Seamless Knitting Producers | 40% |
| Fibre & Elastane Suppliers | 25% |
| Private-Label Manufacturers | 20% |
| Distributors & Retail Buying Offices | 15% |
Trade flows were validated against UN Comtrade and World Bank WITS tariff and merchandise trade records, complemented by corporate annual filings and investor presentations from listed apparel manufacturers. Technical and quality standards were cross-checked against published conformity and labelling requirements, and patent and process literature informed the assessment of knit-to-shape manufacturing maturity.
Sizing was triangulated simultaneously from the top down (macroeconomic consumption allocation and apparel segment shares) and the bottom up (manufacturer capacity, unit pricing and end-use consumption modelling). Where published estimates diverged, the reconciliation was driven by definitional scope rather than averaging.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |