 Germany Consumer Appliances Market
: Size, Share & Trends 2026
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 246

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Germany Consumer Appliances Market
Vijayashree Ugale
Research Analyst

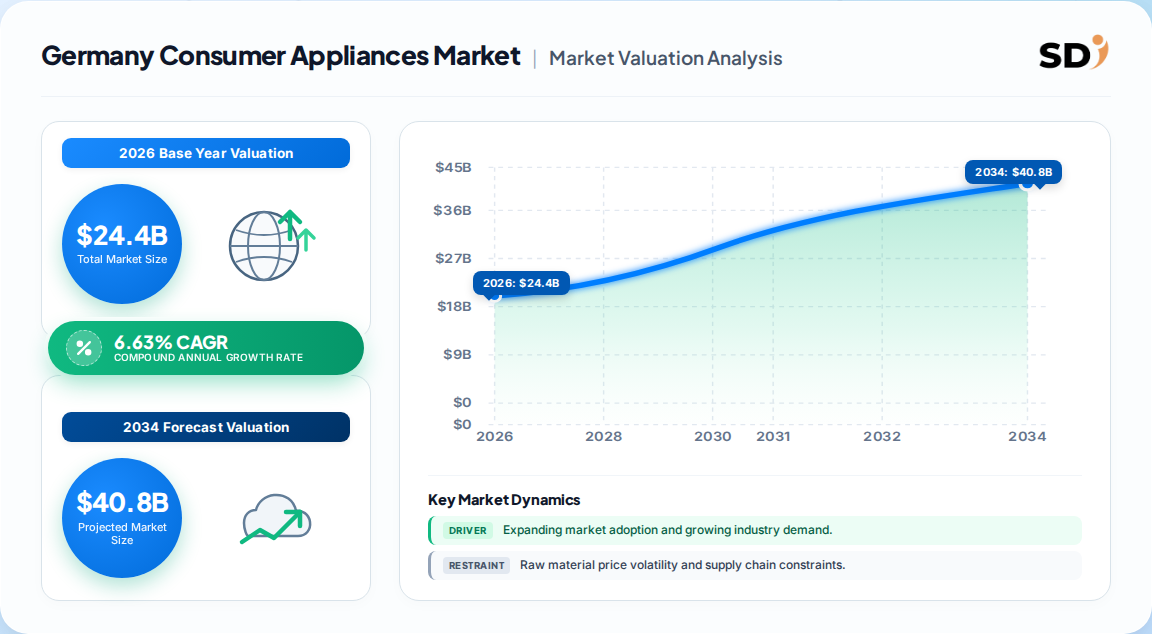
| Year | Market Size |
|---|---|
| 2025 | 22.40 B |
| 2026 | 24.40 B |
| 2027 | 26.00 B |
| 2028 | 27.70 B |
| 2029 | 29.60 B |
| 2030 | 31.50 B |
| 2031 | 33.60 B |

The Germany consumer appliances market covers household (white goods) and kitchen appliances sold to private consumers — refrigerators, washing machines, dishwashers, ovens, vacuums and small kitchen devices. Valued near USD 24.4 Billion in 2026, it is a mature, brand-concentrated market shaped by energy regulation, high electricity prices and omnichannel retail.
This analysis covers consumer appliances sold through B2C channels across Germany's 16 federal states, segmented by product (major and small appliances) and distribution channel (multi-brand stores, exclusive stores, online and others). This analysis does not cover consumer electronics (brown goods such as televisions and audio), professional/HoReCa equipment, fans and fan heaters, lamps, or standalone home-energy hardware such as heat pumps themselves.
Estimates converge on a national market in the low-to-mid USD 20 billions for 2025–2026, with the dispersion driven almost entirely by scope definitions — whether brown goods, small appliances and AAS models are included. The table below reconciles the competing figures.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 18.21 Billion | 2021 | 2030 | 6.4% | Household + kitchen appliances; broad white-goods definition | One published estimate |
| USD 18.8 Billion (→ USD 31.86 Bn) | 2022 | 2030 | 6.4% | Same publisher, later restatement | A competing analysis |
| USD 15.28 Billion | 2026 | 2031 | 3.24% | Major + small home appliances; policy-replacement framing | A competing analysis |
| USD 22.4 Billion (base 2025) → 24.4 Bn | 2025 | 2034 | 6.63% | Home appliances, major + small, full B2C | A competing analysis |
| Statista forecast | 2026 | 2030 | Disclosed in paid tier | Household appliances incl. small appliances | Statista Market Insights |
Our assessment: the USD 22.4–24.4 Billion band is the most defensible base-year anchor because it captures both major and small appliances in a single B2C perimeter, and its 6.63% CAGR is consistent with post-2022 inflation-adjusted replacement behavior. The USD 15.28 Billion figure appears to under-scope small appliances and reflects a deliberately conservative replacement-only model. The divergence between 3.24% and 6.63% is the single most consequential number in this market — one implies stagnation, the other a genuine upgrade cycle.
The market splits cleanly into product and channel axes, with major appliances anchoring revenue while small appliances carry volume and growth momentum.
| Parent segment | Children | Share / note |
|---|---|---|
| Major appliances | Refrigerators, freezers, dishwashers, washing machines, ovens, air conditioners | ~72.3% of 2025 value |
| Small appliances | Coffee/tea makers, food processors, vacuum cleaners, grills & roasters, air fryers | Fastest growth at ~4.93% CAGR |
| Multi-brand stores | Media Markt, Saturn, Euronics | ~47.6% of 2025 share |
| Exclusive brand stores | Miele, Bosch, Siemens outlets | Premium, experience-led |
| Online | Amazon, Otto, manufacturer D2C | ~5.85% CAGR to 2031 |
| Others | Discounters (Aldi, Lidl), department stores | Price-led, promotional |
North Rhine-Westphalia leads with approximately 24% of national value, reflecting its population density and urban household concentration; Bavaria is the fastest-growing state at a projected 4.46% CAGR through 2031.
Implication: Demand clusters where electricity prices and urban density are highest — North Rhine-Westphalia and Hesse churn fastest on energy-efficiency replacements, while Baden-Württemberg and Bavaria lead on smart, connected upgrades and heat-pump-adjacent dryers. Distributors should weight inventory and installer partnerships accordingly.
Growth is regulation-led and efficiency-driven rather than volume-led: energy-efficiency mandates, subsidy frameworks and omnichannel retail pull forward replacements, while high appliance penetration and long major-appliance lifecycles cap organic demand.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| EU/German energy-efficiency regulation | Driver | Strong (+1.2% CAGR) | A-class replacements pulled forward; standby rules tighten 2025–2027 |
| Smart, connected adoption (Matter, smart meters) | Driver | Strong (+0.9%) | Higher ASPs, AI diagnostics, service lock-in |
| E-commerce & omnichannel | Driver | Strong (+0.8%) | Click-and-collect, faster delivery, lower purchase risk |
| Federal BEG/KfW-BAFA subsidies | Driver | Moderate (+0.7%) | Heat-pump dryers, A-class grants steer upgrades |
| High household penetration | Restraint | Moderate | Replacement-only demand in major appliances |
| High electricity prices (~€0.32/kWh) | Restraint (short-term) | Moderate | Delays discretionary small-appliance spend |
| Discounter price competition | Restraint | Moderate | Margin compression at entry tier |
The balance: Our analysis suggests the regulatory driver (+1.2%) and subsidy driver (+0.7%) together offset penetration saturation, which is precisely why the 6.63% CAGR is credible against the 3.24% conservative case. The second-order effect is a shift in what consumers value — repairability scores and digital product passports now sit beside energy labels at the point of sale.
The market is concentrated around a German-anchored premium core (BSH, Miele) and multinational challengers (Electrolux, Whirlpool, Haier, LG, Samsung, Arçelik), with brand trust and service networks acting as the dominant moats.
| Vendor | Core strength | Strategic posture |
|---|---|---|
| BSH Hausgeräte (Bosch/Siemens) | Scale, smart home ecosystem, national service | Broad portfolio, AI diagnostics integration |
| Miele | Premium durability, brand loyalty | Repairability and longevity positioning |
| Electrolux (AEG) | European design, mid-premium | Efficiency-led product refresh |
| Whirlpool | Mass-market reach | Value and replacement cycles |
| Haier Group | Multi-brand scale, price agility | Share-gain through portfolio breadth |
| LG / Samsung | Smart connectivity, digital features | Ecosystem and interoperability (Matter) |
| Arçelik (Beko/Grundig) | Value-to-mid tier | Discounter and online channel leverage |
Differentiation is shifting from hardware to software: interoperability, app ecosystems and post-sale service are becoming the new competitive frontier, and vendors lacking Matter-ready connectivity risk premium-tier exclusion.
Procurement decisions now hinge on regulatory compliance and total cost of ownership, not headline price. Buyers must verify energy-label tier, repairability scoring, spare-part availability and digital product passport readiness before committing to volume orders.
Switching costs are rising for both consumers and retailers: proprietary ecosystems create lock-in, while retailer private-label and discounter programs compress margins for branded mid-tier lines. Operators should model subsidy eligibility carefully — KfW and BAFA grants materially alter consumer payback periods and can pull forward purchases ahead of rule inflection points.
Key risks include inventory obsolescence as labels tighten in 2025 and 2027, supply-chain exposure to component lead times, and returns handling for large online purchases. Compliance with e-waste and disposal regulations adds end-of-life cost that favors vendors with established take-back infrastructure.
The balance of evidence favors the higher-growth view: a 6.6% CAGR is credible because regulation and subsidy are functioning as demand-scheduling mechanisms, converting a saturated replacement market into a timed upgrade cycle. The strongest counter-argument is the 3.24% conservative case — if subsidy uptake stalls or electricity prices fall, replacement timing reverts to technical failure and growth compresses toward penetration rates.
Our judgment is that the conservative case underweights the compounding effect of repairability scoring and digital product passports on consumer choice, which effectively shortens perceived appliance lifespan. That pushes churn higher, not lower.
Actionable strategy:
Evidence that would change our conclusion: a sharp fall in electricity prices combined with subsidy withdrawal would shift the market decisively toward the 3.24% scenario.
| Region | Market Share (%) |
|---|---|
| North Rhine-Westphalia | 0.24% |
| Bavaria | 0.18% |
| Baden-Württemberg | 0.15% |
| Lower Saxony | 0.11% |
| Hesse | 0.1% |
| Rest of Germany | 0.22% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.63% from 2020-2034 |
| Segmentation |
|
The market is valued at approximately USD 24.4 Billion in 2026. Estimates vary by scope, but the most defensible band, covering major and small appliances, sits near USD 22–24 Billion, with growth projected to USD 40.7 Billion by 2034.
The market is projected to grow at a 6.63% CAGR from 2026 to 2034. A more conservative competing estimate puts growth at 3.24%, with the gap reflecting differing assumptions on regulation-driven replacement versus technical-failure-only demand.
Major appliances lead with roughly 72% of market value, driven by refrigerators, washing machines and ovens. Small appliances grow fastest at near 5% CAGR, led by air fryers, robotic vacuums and coffee machines.
Online channels are the fastest-growing distribution channel at approximately 5.85% CAGR through 2031. Multi-brand stores still hold around 48% of share, supported by in-store evaluation, click-and-collect and installation services for major appliances.
Key players include BSH Hausgeräte (Bosch and Siemens), Miele, Electrolux, Whirlpool, Haier, LG Electronics, Samsung and Arçelik. German-anchored brands dominate premium tiers through service networks and brand loyalty.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis rests on a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, spanning component and raw-material suppliers, OEM appliance manufacturers, contract assemblers, national distributors and omnichannel retailers. Decision-makers engaged included VP-level Sourcing leads, Heads of Product R&D, Technical and Compliance Directors, and Commercial Operations Leads, ensuring both demand-side and supply-side perspectives were captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| R&D & Product Directors | 30% |
| Regulatory & Compliance Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Appliance OEMs & Manufacturers | 40% |
| Component & Material Suppliers | 25% |
| National Distributors & Retailers | 22% |
| Service & Installation Providers | 13% |
Findings were cross-validated against official multilateral trade databases (UN Comtrade, Eurostat, WTO), corporate annual filings and investor presentations, patent databases for smart-appliance and efficiency technology, and recognized technical standards bodies including EU Ecodesign and energy-label frameworks. No competitor market-research publications were used as validation sources.
We applied simultaneous top-down allocation (macroeconomic household spending, energy-price indices, segment budgets) and bottom-up modeling (manufacturer capacity, product pricing tiers, end-use consumption by state) to triangulate market size and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |