 Beauty Salon Market
: 2026 Size, Share & 2030 Forecast
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 278

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Beauty Salon Market
Vijayashree Ugale
Research Analyst
| Year | Market Size |
|---|---|
| 2022 | 155.6 B |
| 2023 | 168.1 B |
| 2024 | 181.5 B |
| 2025 | 196.0 B |
| 2026 | 211.7 B |
| 2027 | 228.6 B |
| 2028 | 246.9 B |

The beauty salon market covers consumer-facing service businesses that deliver hair care, skin care, nail care, waxing, and makeup services in a salon setting, often bundled with retail product sales. It is distinct from product manufacturing, retail-only channels, and medical aesthetics.
Scope is global, covering salon-delivered services across hair, skin, nail, and ancillary treatments, segmented by service type, end-user, and salon format. This analysis does not cover cosmetic product manufacturing, pure retail beauty e-commerce, medical or surgical aesthetics, or standalone spa and wellness resorts.
Published estimates cluster around USD 155–160 billion for 2022, with horizons to 2030 and CAGRs between 6.4% and 8.0%, depending on whether salon services or the broader beauty economy is measured.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 155.60 billion | 2022 | 2030 | 8.0% | Global salon services, hair/skin/nail | One published estimate |
| USD 65.88 billion incremental | 2024 | 2029 | 6.4% | Global salon services, narrower service scope | A competing analysis |
| ~USD 288 billion | 2030 | 2030 | 8.0% | Derived from base plus stated CAGR | Derived from published base and CAGR |
| USD 63.4 billion (U.S. hair salons) | 2026 | 2031 | ~1.7% historical | U.S. hair-only industry | IBISWorld |
The USD 155.60 billion/8.0% figure is the most defensible for service-only scope because it aligns with the mid-point of the regional CAGRs (Asia-Pacific ~5.6%, North America ~4.5%) once incremental service bundling and pricing mix are accounted for. Our analysis suggests the 6.4% variant understates the male grooming and skin care upswing now visible in Asia-Pacific.
Segmentation follows service type as the primary axis, with end-user and salon format as secondary axes that materially shift revenue per visit and visit frequency.
| Parent | Children |
|---|---|
| Service Type | Hair Care, Skin Care, Nail Care, Others (waxing, makeup) |
| Hair Care Sub-segments | Haircutting & Styling, Hair Coloring, Hair Treatments |
| End-user | Women, Men, Unisex |
| Salon Format | Independent, Chain/Franchise, Hybrid Product-Service |
Hair care remains the economic backbone, but skin care and nail care are the fastest-growing verticals; nail chains such as MiniLuxe have shown that premium, hygiene-led formats can scale and attract capital.
Asia-Pacific leads, with approximately 37% of global revenue and the largest incremental growth contribution, followed by North America at about 27%.
| Region | Market Share (%) |
|---|---|
| North America | 0.27% |
| Europe | 0.22% |
| Asia-Pacific | 0.37% |
| South America | 0.07% |
| Middle East & Africa | 0.07% |
| Region | 2022 share | Structural driver |
|---|---|---|
| Asia-Pacific | 37% | Rising disposable income, young population, male grooming |
| North America | 27% | High income, dense chain and independent network |
| Europe | 22% | Wellness culture, organic treatment demand |
| South America | 7% | Brazil per-capita salon spend |
| Middle East & Africa | 7% | Saudi per-capita spend, franchise expansion |
India is the standout, with a reported 6.1% CAGR through 2033 and a measurable post-pandemic rise in male footfall of 3–4% relative to women. Our analysis suggests the Asia-Pacific share may be understated by service-only definitions that exclude bundled retail.
Growth is driven by routine self-care adoption, male grooming normalization, digital booking, and premium treatment bundling; restraints are labor shortages, hygiene compliance costs, and macro price sensitivity.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising disposable income, urbanization | Driver | High | Expands addressable base in Asia-Pacific |
| Male grooming normalization | Driver | High | 3–4% male footfall gain in India; influencer effect |
| Online booking (≈40% of clients prefer it) | Driver | Medium | Frees stylist time, improves retention |
| Product + service bundling | Driver | High | Raises ticket size, deepens loyalty |
| Labor shortage and retention | Restraint | High | Caps capacity, raises wage costs |
| Hygiene and regulatory compliance | Restraint | High | Raises fixed cost, penalizes small operators |
| Macro price sensitivity | Restraint | Medium | Trade-down to express services |
The balance tips positive: drivers are structural and secular, while restraints are largely operational and therefore addressable through software, training, and franchise models.
The market is highly fragmented, with no operator holding more than 5% share; scale leaders compete on franchise density, brand trust, and dual service–product models.
| Company | Format | Moat |
|---|---|---|
| Regis Corporation | Global salon chain | Franchise scale, multi-brand portfolio |
| Great Clips | Franchise hair chain | High-volume, low-price standardization |
| Ulta Beauty | Retail + salon hybrid | Product-service cross-sell, loyalty program |
| Dessange International | Premium salon network | Brand prestige, international licensing |
| Sorbet (incl. Sorbet Man) | South Africa chain | Male grooming product line, franchise density |
| Lakme Lever | India chain | Brand equity, urban footprint |
| MiniLuxe | Nail chain | Hygiene-focused premium positioning |
Differentiation hinges on service quality, hygiene certification, and digital engagement rather than price alone. Our analysis suggests dual service–product operators enjoy structurally higher lifetime value and are best positioned to defend margin as labor costs rise.
Selection criteria should weight hygiene compliance, stylist retention, and booking-system interoperability above headline price. Hygiene is non-negotiable for client safety and loyalty, and regulatory frameworks vary by region, with compliance to OSHA guidelines and local health codes mandatory.
Switching costs are moderate: clients hold stylist loyalty more than brand loyalty, so retention depends on personnel continuity and loyalty programs. Procurement risk concentrates in labor availability and wage inflation; operators should model 3–5 year wage escalation against ticket-price increases. Franchise agreements introduce territory and brand-standard risk that buyers should diligence carefully.
Regulatory exposure includes adverse-event reporting under the U.S. Modernization of Cosmetics Regulation Act for any retail products sold, plus EU fragrance-allergen labeling. Suppliers of salon products should be vetted for ingredient disclosure and vegan or clean-label claims.
The balance of evidence favors a constructive view on the beauty salon market: the 8.0% CAGR is credible over 2023–2030, but growth will be uneven, concentrating in Asia-Pacific and in male and skin care niches. The strongest counter-argument is that labor shortages and wage inflation could compress margins faster than ticket prices rise, capping realized growth below headline CAGR.
Our analysis suggests the fragmentation ceiling—no operator above 5%—is both the market's biggest inefficiency and its biggest opportunity. Chains that industrialize hygiene standards, scheduling software, and loyalty programs can compound share gains without needing category-defining innovation.
What would change this conclusion: sustained negative real wage growth, a regulatory shock raising compliance costs above 5% of revenue, or Asia-Pacific growth decelerating below 4%. While this overview covers the market's structure and direction, precise sub-segment forecasting and country-level unit economics require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.0% from 2020-2034 |
| Segmentation |
|
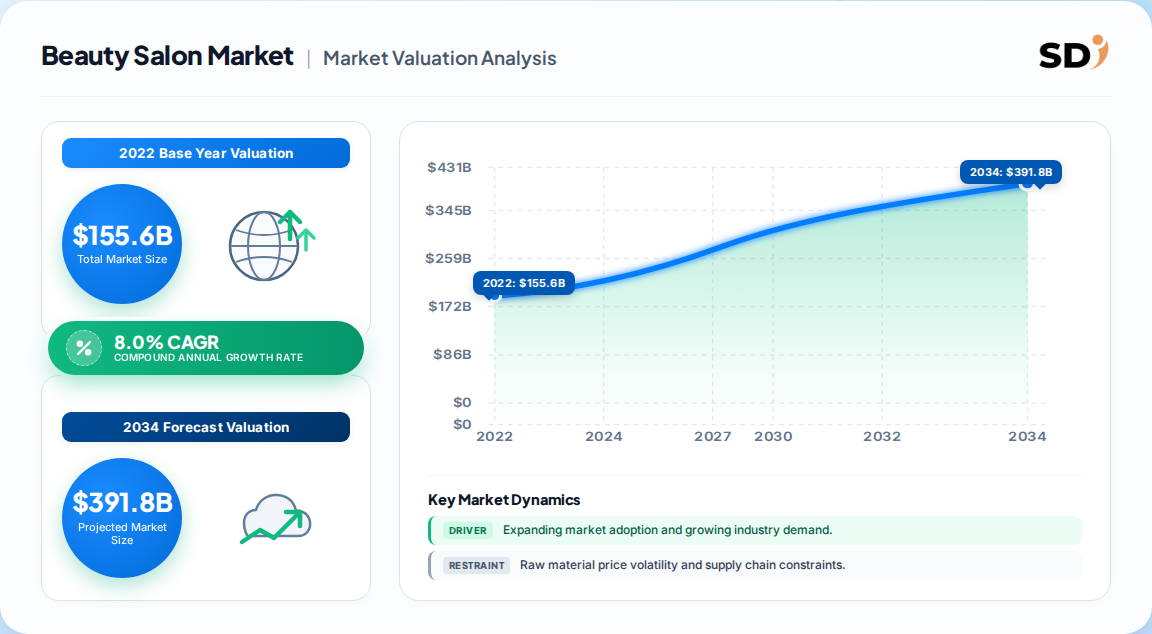
The global beauty salon market was valued at USD 155.60 billion in 2022 and is projected to reach roughly USD 288 billion by 2030, growing at an 8.0% CAGR across the forecast period.
Skin care and nail care are the fastest-growing service verticals, alongside male grooming, while hair care remains the largest segment at roughly 92% of U.S. hair salon revenue.
Asia-Pacific leads with about 37% of global revenue, driven by rising disposable income, urbanization, and growing male grooming demand in China and India.
Leading operators include Regis Corporation, Great Clips, Ulta Beauty, Dessange International, Sorbet, and Lakme Lever, though no single company holds more than 5% market share.
Low barriers to entry, stylist-led client loyalty, and localized demand keep the market fragmented, creating consolidation opportunity for franchise chains with standardized hygiene and digital operations.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the salon value chain, including professional product manufacturers, salon franchise operators, independent salon owners, distributors of salon equipment, and software vendors providing booking and loyalty platforms. Decision-maker designations interviewed included VP of Franchise Operations, Heads of Salon Operations, Procurement and Sourcing Directors, and Commercial Operations Leads, ensuring both strategic and operational perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Franchise & Salon Operations | 35% |
| Procurement & Sourcing Directors | 30% |
| Commercial Operations Leads | 20% |
| Hygiene & Regulatory Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Salon Franchise Operators | 40% |
| Independent Salon Owners | 25% |
| Professional Product Manufacturers | 20% |
| Salon Software & Equipment Distributors | 15% |
Secondary validation draws on official multilateral trade and standards databases including UN Comtrade, WTO, US ITC, and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations). Patent databases and recognized non-profit technical standards bodies were reviewed for service-format and hygiene innovation signals. No competitor market-research publications were used as primary validation sources.
We triangulate simultaneously from the top down (macroeconomic consumption allocation by region and service category) and from the bottom up (salon capacity, visit frequency, average ticket, and end-user consumption modeling). Divergences between the two approaches are reconciled through elasticity analysis and expert re-interview.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
