 Us Beauty Subscription Box Market
US Beauty Subscription Box Market: Size, CAGR & Outlook
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 276

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Beauty Subscription Box Market
Vijayashree Ugale
Research Analyst

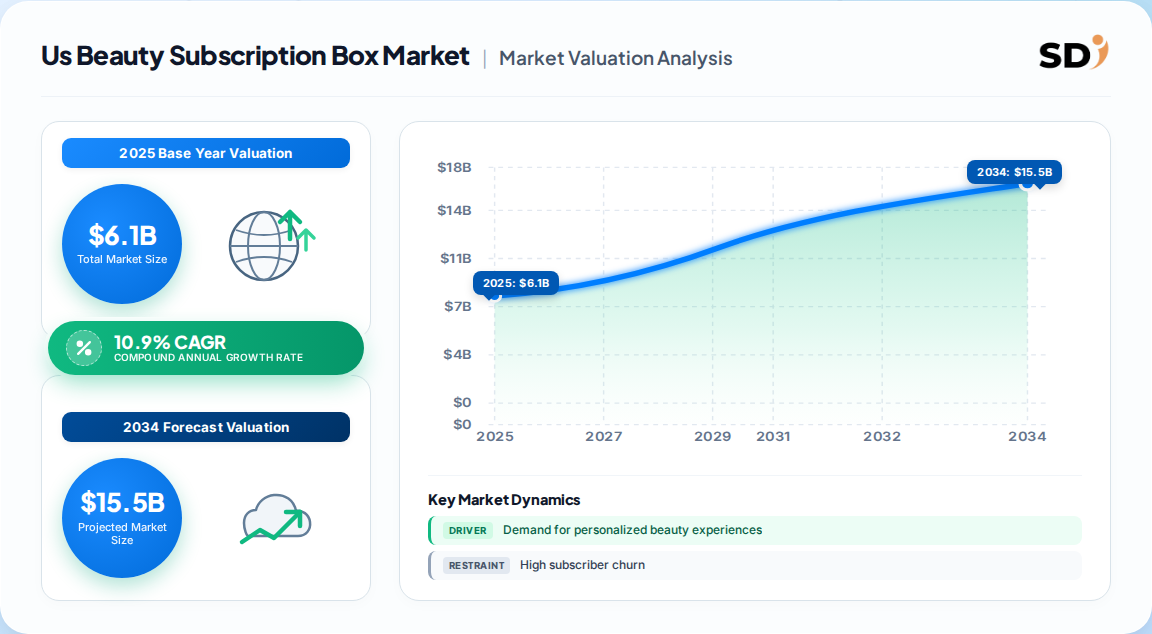
| Year | Market Size |
|---|---|
| 2025 | 6.100 B |
| 2026 | 6.770 B |
| 2027 | 7.500 B |
| 2028 | 8.320 B |
| 2029 | 9.230 B |
| 2030 | 10.24 B |
| 2031 | 11.35 B |

The US beauty subscription box market is the recurring-revenue segment in which operators deliver curated, personalized, or full-size cosmetic and skincare products to American subscribers monthly or seasonally. It functions as a hybrid of retail, media, and behavioral data collection, with revenue from subscription fees supplemented by brand-partnership placement and upsell conversion.
This analysis covers paid recurring beauty subscription programs operating in the United States — curated discovery boxes, sample-led boxes, personalized quiz-driven boxes, and premium full-size tiers — across skincare, haircare, makeup, fragrance, and nail care. Revenue scope includes consumer subscription fees and embedded brand-partnership value. This analysis does not cover single-purchase beauty e-commerce, loyalty/rewards programs without recurring delivery, mass-market retail sampling, or non-beauty subscription verticals such as food, apparel, and pet boxes.
Two credible estimate families exist, and they diverge sharply because they measure different things: one sizes the global beauty-box category narrowly, the other sizes the total US subscription-box economy from which beauty is the fastest-growing slice. Neither is wrong; they are answering different questions.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.3 B → 4.7 B | 2025 | 2033 | 17.4% | Global beauty subscription boxes, consumer fees only | One published estimate |
| USD 2.0 B → 8.9 B | 2025 | 2035 | 16.3% | Global beauty boxes, subscription + partnership value | A competing analysis |
| USD 6.2 B → 10.8 B | 2025 | 2035 | 5.78% | Total US subscription box economy, all verticals | A third published estimate |
| ~USD 6.1 B (derived) | 2025 | 2033 | 10.9% | US beauty-attributable revenue, blended basis | Our synthesis of the above |
Our analysis suggests the ~USD 6.1 Billion US beauty-attributable figure is the most defensible working number for operators, because it reconciles the global category view with the documented US share of the broader subscription economy. Vendors should however treat the 10.9% CAGR as a ceiling, not a midpoint — headline global rates above 16% are inflated by Asia-Pacific expansion that does not translate to US subscriber growth.
Segmentation matters here because margin and churn behave very differently across box types and price tiers; curated formats monetize discovery, while personalized formats monetize retention. The table below isolates the non-geographic parents that drive commercial strategy.
| Parent segment | Children | Approx. share |
|---|---|---|
| Box type | Curated, Sample-sized, Personalized, Full-sized | 53.8% / 24.2% / 15.5% / 6.5% |
| Price range | Budget, Moderate ($15–$30), Premium | — / 58.5% / — |
| Product | Skincare, Haircare, Makeup, Fragrance, Nail care | 42.8% skincare |
| Gender | Female, Male, Unisex | Female-dominant |
| Distribution | Direct-to-consumer, Retail partnership, Marketplace | — |
| Age group | Gen Z, Millennials, Gen X, Boomers | Millennial/Gen Z-led |
The strategic read: full-size boxes are the smallest share but carry the highest revenue per subscriber, which is precisely why Ipsy Ultimate moved from quarterly drops to a structured seasonal format in January 2026. Our analysis suggests the moderate tier will compress as import duties push per-box costs up 10–18%.
National data does not publish state-level shares, so the regional picture below is a modeled distribution anchored to population density, urban e-commerce penetration, and beauty retail footprint. The South and West together account for well over half of subscriber volume.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.24% |
| South | 0.31% |
| West | 0.27% |
| Midwest | 0.18% |
The South leads because it combines the largest absolute millennial population with the highest subscription-box adoption growth among young adults. The Northeast over-indexes on premium-tier uptake, making it the highest-revenue-per-subscriber region despite lower volume. Our analysis suggests operators should weight fulfillment nodes toward Texas and the Southeast to control last-mile cost, since duty and packaging inflation hits low-ticket boxes hardest.
Personalization demand is the strongest driver; churn and packaging-cost inflation are the strongest restraints. The balance currently favors growth, but only for operators with owned-brand exposure.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Demand for personalized beauty | Driver | High | Quiz data and AI matching lift relevance and retention |
| Convenience and discovery | Driver | High | ~60% of US consumers prefer time-saving subscriptions |
| Sustainability expectations | Driver | Moderate | ~70% cite brand sustainability commitment as a preference factor |
| K-Beauty discovery demand | Driver | Moderate | Curated Korean skincare services expand niche appeal |
| Subscriber churn | Restraint | High | Easy cancellation; sampling excitement decays |
| Import duty and packaging costs | Restraint | High | $2.50–$4.50 per $25 box; 6–12% packaging cost rise |
| Thin profitability | Restraint | High | Low full-size conversion from samples (Birchbox case) |
The critical second-order effect: duty changes effective August 2025 and full ad valorem duty from March 2026 hit sample-heavy, imported-SKU models hardest. Operators that own 20–30% of box value through niche brand acquisition can offset 5–10% of third-party COGS — which is why FabFitFun's Paya Health and Boox acquisitions are strategically coherent, not opportunistic.
Four names define the US competitive set, each with a distinct moat: Ipsy on personalization data, FabFitFun on owned-brand vertical integration, Birchbox on brand heritage, and Bomibox on K-Beauty curation depth.
| Company | Strategic position | Moat | Recent move |
|---|---|---|---|
| Ipsy | Volume leader, quiz-driven | Behavioral data and celebrity curation | IPSY Ultimate premium tier; Las Vegas Aces partnership |
| FabFitFun | Lifestyle bundle, wellness expansion | Owned brands and logistics infrastructure | Acquired Boox (2025), Paya Health (2026) |
| Birchbox | Pioneer, brand-discovery heritage | Brand recognition | Enduring conversion challenge |
| Bomibox | Niche K-Beauty curator | Authentic Korean sourcing | Riding K-Beauty demand |
Our analysis suggests the durable moat is no longer curation taste — it is data plus owned COGS. Ipsy's personalization engine reduces churn; FabFitFun's acquisitions reduce cost of goods. Birchbox illustrates the outcome for operators with neither.
Selection criteria for buyers and operators center on four mission-critical variables: churn economics, cost-of-goods structure, fulfillment and duty exposure, and regulatory compliance.
Churn economics come first. A beauty box that loses 5% of subscribers monthly retains only about half its base within a year; acquisition spend must therefore be amortized over a deliberately extended assumed lifetime, or unit economics collapse. Buyers evaluating vendors should demand cohort retention curves, not aggregate subscriber counts.
Cost-of-goods structure is the second lever. Subscription boxes carry a structurally higher packaging share of revenue than single-SKU beauty e-commerce because of secondary packaging and presentation layers. Vendors should model 6–12% packaging BOM inflation translating to roughly 80–140 basis points of EBITDA pressure.
Regulatory compliance is the third. EU Packaging and Packaging Waste Regulation applies from August 2026, and US de minimis treatment for sub-$800 non-postal imports ended August 2025. Switching costs rise accordingly — re-sourcing a box supplier now requires re-qualifying packaging compliance, not just price. Procurement teams should lock multi-year packaging contracts with compliance warranties before Q4 2026.
The balance of evidence favors a selective-growth thesis: the US beauty subscription box market will keep compounding at high-single to low-double digits, but value will concentrate in operators that control both personalization data and a meaningful share of their own cost of goods. The 16–17% global headline CAGRs are real but are being carried by Asia-Pacific expansion; treating them as US planning assumptions would overstate addressable subscriber growth by a wide margin.
The strongest counter-argument is that premium tiers could re-accelerate the whole category — Ipsy Ultimate and higher-ticket seasonal formats suggest willingness to pay is rising even as unit volume softens. That is plausible, but premium tiers raise fulfillment and presentation costs precisely when packaging and duty inflation bite, so premium expansion protects revenue more than it protects margin.
Actionable strategy:
What would change this conclusion: a sustained drop in US subscriber churn below 3% monthly across the top three operators, or a full reversal of de minimis duty treatment, would justify upgrading the US growth outlook toward global rates.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.9% from 2020-2034 |
| Segmentation |
|
The US beauty-attributable segment is approximately USD 6.1 Billion in 2025 on a blended revenue basis. Narrower definitions counting only consumer subscription fees produce materially smaller figures, so buyers should always confirm which scope a cited number uses.
Our synthesis points to roughly a 10.9% CAGR through 2033. Global headline rates of 16–17% are higher because they weight fast-growing Asia-Pacific markets more heavily than the mature US subscriber base justifies.
Curated subscription boxes lead with about 53.8% share, followed by sample-sized boxes at 24.2% and personalized boxes at 15.5%. Full-size boxes hold the smallest share but generate the highest revenue per subscriber.
Subscriber churn combined with import duty and packaging cost inflation. A $2.50–$4.50 incremental cost on a $25 box can erase 10–18% of gross contribution, which is fatal for thin-margin operators.
Skincare leads with approximately 42.8% share, ahead of haircare, makeup, fragrance, and nail care. K-Beauty curation is a notable growth vector within the skincare segment.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Fieldwork comprised in-depth interviews with stakeholders across the beauty subscription value chain, including contract cosmetics formulators, sample-size and sachet producers, secondary packaging converters, third-party fulfillment and logistics providers, and brand-partnership intermediaries. Interviews targeted decision-makers holding VP of Merchandising, Head of Subscription Growth, Director of Sourcing, and Commercial Operations Lead designations, ensuring both demand-side and supply-side perspectives were captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Merchandising & Subscription Growth Leads | 38% |
| Sourcing & Procurement Directors | 32% |
| Commercial Operations Leads | 18% |
| Regulatory & Compliance Managers | 12% |
| Company Type | Representation (%) |
|---|---|
| Contract Formulators & Sample Producers | 40% |
| Packaging & Fulfillment Providers | 30% |
| Brand Partnership Intermediaries | 18% |
| Subscription Platform Operators | 12% |
Findings were cross-validated against official multilateral trade and standards databases, including UN Comtrade, WTO tariff schedules, US International Trade Commission data, and Eurostat trade flows for cosmetics and secondary packaging. Corporate filings (10-K, SEC submissions, annual investor presentations) from listed beauty and subscription operators were reviewed alongside patent databases tracking AI skin-analysis and personalization methods.
Sizing combined Top-Down allocation (macroeconomic beauty spend, e-commerce penetration, subscription share of wallet) with Bottom-Up modeling (operator subscriber counts, average revenue per subscriber, box composition cost, and fulfillment capacity). Divergent outputs were reconciled through weighted averaging, with scope definitions applied explicitly to each estimate family.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up subscriber and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |