Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Chemical Protective Clothing Market: 2026 Size & Growth
Chemical Protective Clothing Market
Chemical Protective Clothing Market: 2026 Size & Growth
Chemical Protective Clothing Market by Product Type (Coveralls, Gloves, Aprons, Boots, Face Shields), by Material Type (Polyethylene, Polyvinyl Chloride, Nomex, Tyvek, Rubber, Aramid & Blends, Polyolefin, UHMW Polyethylene), by Performance Level (Type 1, Type 2, Type 3, Type 4, Type 5, Type 6), by End-Use Industry (Chemical Manufacturing, Oil & Gas, Healthcare/Medical, Construction & Manufacturing, Firefighting & Law Enforcement, Military/Defense, Mining, Hazardous Waste), by User Type (Industrial, Personal), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 207
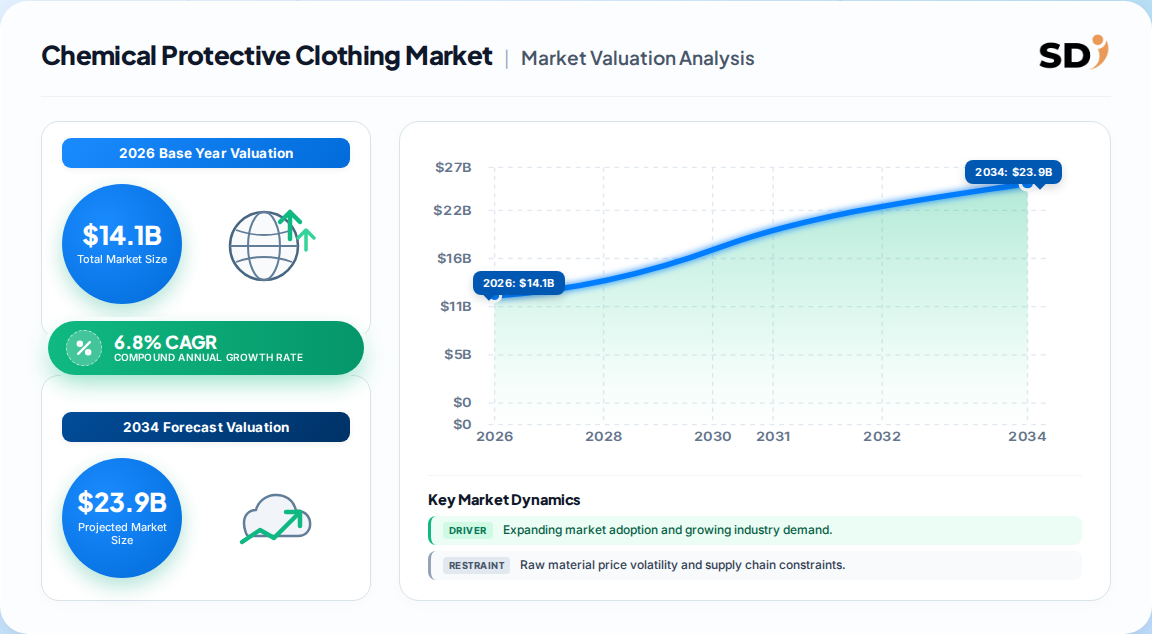
US$14.1 billion is the 2026 global chemical protective clothing market size, per a synthesis of published estimates covering certified industrial PPE.
Forecast growth runs at a 6.8% CAGR through 2033, reaching roughly US$22.3 billion as chemical, pharma and energy workforces expand.
Coveralls lead product demand with about 40% revenue share; Tyvek is the leading barrier material at over 30%.
North America holds the largest regional share (~35%), while Asia Pacific is the fastest-growing region at a 4.0–4.7% regional pace.
Leading vendors include DuPont, 3M, Honeywell, MSA Safety, Ansell, Lakeland Industries, Sioen and Kappler.
Restraint: heat stress and ergonomic limits in high-barrier ensembles suppress continuous-use adoption.
Why this matters for decision-makers: Vendors that pair certified chemical barriers with breathable, sensor-ready construction will capture replacement demand faster than single-hazard commodity suppliers.
Chemical Protective Clothing Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
12.35 B
2024
13.19 B
2025
14.10 B
2026
15.06 B
2027
16.08 B
2028
17.18 B
2029
18.35 B
2030
Chemical Protective Clothing Market Size (In Billion)
Year
Market Size
2024
12.35 B
2025
13.19 B
2026
14.10 B
2027
15.06 B
2028
16.08 B
2029
17.18 B
2030
18.35 B
What is the Chemical Protective Clothing Market?
The chemical protective clothing market covers garments and accessories engineered to shield workers from chemical splash, permeation, particulate and hazardous-waste exposure. Products include coveralls, gloves, aprons, boots and face shields, classified by performance Type 1–6 and material such as Tyvek, Nomex, polyolefin, rubber and laminated polyester.
Scope: what this report covers and excludes
This analysis covers global demand for certified chemical protective garments and accessories across industrial, healthcare, emergency-response, defense and mining end uses. Coverage spans disposables, reusables and encapsulating suits, segmented by material, performance level and user type. This analysis does not cover general industrial workwear, respiratory protection, firefighting turnout gear, cleanroom apparel or medical isolation gowns except where chemically rated.
How big is the market for Chemical Protective Clothing Market?
Published estimates diverge sharply in both base value and growth pace, largely reflecting differing definitions of what counts as certified chemical protective clothing. The table below reconciles the leading published figures.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
US$1.12 bn → US$1.83 bn
2021
2028
7.13%
Specialty material-centric CPG, narrower
One published estimate
US$12.35 bn → US$25.44 bn
2024
2035
6.79%
Broad industrial PPE incl. disposables
A competing analysis
US$14.1 bn → US$22.3 bn
2026
2033
6.8%
Broad certified CPG across all end uses
A competing analysis
US$1.07 bn → US$1.45 bn
2025
2034
3.47%
Narrow material-category tracking
A competing analysis
Our analysis suggests the broad US$14.1 billion 2026 figure is the most defensible anchor, because it aligns with recognized PPE market aggregates and captures disposable coverall volumes that narrower studies exclude. The 3.47% figure is credible only under a restricted material scope and likely understates total industrial demand.
How is the market segmented?
Segmentation below reflects non-geographic parents; regional splits are handled separately. Material and performance-level splits carry the most procurement weight.
Chemical Manufacturing, Oil & Gas, Healthcare/Medical, Construction & Manufacturing, Firefighting & Law Enforcement, Military/Defense, Mining, Hazardous Waste
By User Type
Industrial, Personal
Coveralls dominate at roughly 40% of revenue because full-body protection remains the default specification for chemical handling and waste operations. Tyvek's 30%+ material share reflects its balance of barrier performance, weight and cost in disposable formats.
Which region leads in Chemical Protective Clothing Market?
North America leads the chemical protective clothing market, holding roughly 35% of global revenue in 2026 on the back of stringent OSHA-aligned exposure controls and a dense chemical and pharmaceutical industrial base.
Chemical Protective Clothing Market Regional Market Share
Loading chart...
Chemical Protective Clothing Market Regional Market Share
Region
Market Share (%)
North America
0.35%
Europe
0.27%
Asia-Pacific
0.28%
South America
0.05%
Middle East & Africa
0.05%
North America — ~35% share; led by the United States (~79–83% of regional demand)
United States
Canada
Mexico
Europe — ~27% share
Germany
United Kingdom
France
Italy
Spain
Asia Pacific — ~28% share; fastest-growing region
China
Japan
India
South Korea
Australia
South America — ~5% share
Brazil
Argentina
Middle East & Africa — ~5% share
Saudi Arabia
UAE
South Africa
Asia Pacific's 4.0–4.7% regional growth outpaces mature markets, driven by manufacturing relocation and tightening occupational safety enforcement. Our analysis indicates APAC will close the gap with North America within the forecast horizon, but regulatory fragmentation across the region caps near-term certified-product penetration.
What is driving growth — and what is holding it back?
Growth is driven by regulatory stringency and industrial expansion, while heat stress and ergonomic burden are the principal brakes on continuous-use adoption.
More hazardous-handling workers require matched barrier garments
Hazard awareness and training programs
Driver
Medium
Employers shift from basic PPE to full protection systems
Lightweight multi-hazard fabrics
Driver
Medium
Breathable barriers improve comfort and compliance
Heat stress and ergonomic burden
Restraint
High
Impermeable ensembles limit ventilation, reducing wear time
Polymer and textile cost volatility
Restraint
Medium
Input swings pressure margins and pricing
Smart/sensor-enabled PPE convergence
Opportunity
Emerging
Real-time exposure and heat monitoring adds value layer
The balance of evidence favors demand expansion: regulation is a structural, non-cyclical driver that outpaces the comfort-driven restraint. However, the heat-stress constraint is commercially material — it is the single largest reason workers under-wear high-barrier garments, and it explains the industry's pivot toward breathable laminates.
Who are the leading vendors?
DuPont and 3M anchor the competitive field, with DuPont's Tyvek franchise and 3M's diversified PPE portfolio commanding the widest certified product breadth and specification inertia.
Company
Headquarters
Position / focus
DuPont
US
Tyvek and Tychem barrier leadership
3M
US
Diversified PPE and respiratory ensemble integration
Honeywell
US
Industrial safety and gas-detection synergy
MSA Safety
US
Industrial and emergency-response PPE
Ansell
Australia
Gloves and hand protection integration
Lakeland Industries
US
Chemical-resistant apparel specialization
Sioen Industries
Belgium
Coated and laminated protective textiles
Kappler
US
Emergency-response and hazardous-material suits
W. L. Gore & Associates
US
Breathable membrane barrier technology
Differentiation is shifting from fabric specification to system integration — permeation databases, seam-sealing engineering, certification breadth and digital selection tools. Our analysis suggests vendors with in-house chemical compatibility databases reduce specification time for buyers, creating meaningful switching costs.
What do buyers and operators need to know?
Procurement decisions should be anchored in permeation data, not price per garment. Buyers must match performance level (Type 1–6) to actual exposure — splash, permeation, particulate or confined-entry — because over-specification drives heat stress and under-specification creates liability.
Regulatory compliance is non-negotiable: CE Category III, OSHA and NFPA certifications differ by market, and an uncertified garment offers no defensible protection in an incident review. Switching costs are moderate but rising, since approved-product lists and compatibility testing lock buyers into validated suppliers.
Operators should scrutinize donning/doffing procedures, ensemble compatibility with respirators and gloves, and disposal pathways for contaminated disposables. Total cost of ownership matters more than unit price: durability, washing tolerance and replacement frequency often dominate. Our analysis suggests buyers that run structured field trials before specification reduce compliance failures significantly.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderate-growth, regulation-anchored outlook: a 6.8% CAGR is the most defensible consensus, and the wide divergence among published estimates reflects scope, not contradiction. The strongest counter-argument is that heat-stress limitations cap real-world protection effectiveness and could slow premium-segment adoption — a genuine risk that breathable-laminate innovation must address.
Our judgement is that the market's value is migrating from raw barrier materials toward engineered, multi-hazard systems with digital specification and monitoring layers. Vendors stuck in commodity disposables face margin compression from polymer cost volatility, while those with certification breadth and compatibility data hold pricing power. Asia Pacific is the structural growth engine, but regulatory harmonization remains the gating factor.
Actionable strategy:
Vendors should prioritize breathable, multi-hazard coverall platforms to convert heat-stress deterrence into replacement revenue.
Operators should embed permeation-based selection and field trials into procurement policy to reduce incident and compliance risk.
Investors should weight exposure toward vendors with certification breadth and smart-PPE pipelines over commodity disposable suppliers.
Evidence that would change this conclusion: a sustained decline in occupational exposure regulation enforcement in North America or Europe, or a step-change in reusable barrier durability that collapses disposable volumes, would force downward revision of the growth assumption.
Chemical Protective Clothing Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Chemical Protective Clothing Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.8% from 2020-2034
Segmentation
By Product Type
Coveralls
Gloves
Aprons
Boots
Face Shields
By Material Type
Polyethylene
Polyvinyl Chloride
Nomex
Tyvek
Rubber
Aramid & Blends
Polyolefin
UHMW Polyethylene
By Performance Level
Type 1
Type 2
Type 3
Type 4
Type 5
Type 6
By End-Use Industry
Chemical Manufacturing
Oil & Gas
Healthcare/Medical
Construction & Manufacturing
Firefighting & Law Enforcement
Military/Defense
Mining
Hazardous Waste
By User Type
Industrial
Personal
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
South America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Coveralls
5.1.2. Gloves
5.1.3. Aprons
5.1.4. Boots
5.1.5. Face Shields
5.2. Market Analysis, Insights and Forecast - by Material Type
5.2.1. Polyethylene
5.2.2. Polyvinyl Chloride
5.2.3. Nomex
5.2.4. Tyvek
5.2.5. Rubber
5.2.6. Aramid & Blends
5.2.7. Polyolefin
5.2.8. UHMW Polyethylene
5.3. Market Analysis, Insights and Forecast - by Performance Level
5.3.1. Type 1
5.3.2. Type 2
5.3.3. Type 3
5.3.4. Type 4
5.3.5. Type 5
5.3.6. Type 6
5.4. Market Analysis, Insights and Forecast - by End-Use Industry
5.4.1. Chemical Manufacturing
5.4.2. Oil & Gas
5.4.3. Healthcare/Medical
5.4.4. Construction & Manufacturing
5.4.5. Firefighting & Law Enforcement
5.4.6. Military/Defense
5.4.7. Mining
5.4.8. Hazardous Waste
5.5. Market Analysis, Insights and Forecast - by User Type
5.5.1. Industrial
5.5.2. Personal
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Coveralls
6.1.2. Gloves
6.1.3. Aprons
6.1.4. Boots
6.1.5. Face Shields
6.2. Market Analysis, Insights and Forecast - by Material Type
6.2.1. Polyethylene
6.2.2. Polyvinyl Chloride
6.2.3. Nomex
6.2.4. Tyvek
6.2.5. Rubber
6.2.6. Aramid & Blends
6.2.7. Polyolefin
6.2.8. UHMW Polyethylene
6.3. Market Analysis, Insights and Forecast - by Performance Level
6.3.1. Type 1
6.3.2. Type 2
6.3.3. Type 3
6.3.4. Type 4
6.3.5. Type 5
6.3.6. Type 6
6.4. Market Analysis, Insights and Forecast - by End-Use Industry
6.4.1. Chemical Manufacturing
6.4.2. Oil & Gas
6.4.3. Healthcare/Medical
6.4.4. Construction & Manufacturing
6.4.5. Firefighting & Law Enforcement
6.4.6. Military/Defense
6.4.7. Mining
6.4.8. Hazardous Waste
6.5. Market Analysis, Insights and Forecast - by User Type
6.5.1. Industrial
6.5.2. Personal
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Coveralls
7.1.2. Gloves
7.1.3. Aprons
7.1.4. Boots
7.1.5. Face Shields
7.2. Market Analysis, Insights and Forecast - by Material Type
7.2.1. Polyethylene
7.2.2. Polyvinyl Chloride
7.2.3. Nomex
7.2.4. Tyvek
7.2.5. Rubber
7.2.6. Aramid & Blends
7.2.7. Polyolefin
7.2.8. UHMW Polyethylene
7.3. Market Analysis, Insights and Forecast - by Performance Level
7.3.1. Type 1
7.3.2. Type 2
7.3.3. Type 3
7.3.4. Type 4
7.3.5. Type 5
7.3.6. Type 6
7.4. Market Analysis, Insights and Forecast - by End-Use Industry
7.4.1. Chemical Manufacturing
7.4.2. Oil & Gas
7.4.3. Healthcare/Medical
7.4.4. Construction & Manufacturing
7.4.5. Firefighting & Law Enforcement
7.4.6. Military/Defense
7.4.7. Mining
7.4.8. Hazardous Waste
7.5. Market Analysis, Insights and Forecast - by User Type
7.5.1. Industrial
7.5.2. Personal
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Coveralls
8.1.2. Gloves
8.1.3. Aprons
8.1.4. Boots
8.1.5. Face Shields
8.2. Market Analysis, Insights and Forecast - by Material Type
8.2.1. Polyethylene
8.2.2. Polyvinyl Chloride
8.2.3. Nomex
8.2.4. Tyvek
8.2.5. Rubber
8.2.6. Aramid & Blends
8.2.7. Polyolefin
8.2.8. UHMW Polyethylene
8.3. Market Analysis, Insights and Forecast - by Performance Level
8.3.1. Type 1
8.3.2. Type 2
8.3.3. Type 3
8.3.4. Type 4
8.3.5. Type 5
8.3.6. Type 6
8.4. Market Analysis, Insights and Forecast - by End-Use Industry
8.4.1. Chemical Manufacturing
8.4.2. Oil & Gas
8.4.3. Healthcare/Medical
8.4.4. Construction & Manufacturing
8.4.5. Firefighting & Law Enforcement
8.4.6. Military/Defense
8.4.7. Mining
8.4.8. Hazardous Waste
8.5. Market Analysis, Insights and Forecast - by User Type
8.5.1. Industrial
8.5.2. Personal
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Coveralls
9.1.2. Gloves
9.1.3. Aprons
9.1.4. Boots
9.1.5. Face Shields
9.2. Market Analysis, Insights and Forecast - by Material Type
9.2.1. Polyethylene
9.2.2. Polyvinyl Chloride
9.2.3. Nomex
9.2.4. Tyvek
9.2.5. Rubber
9.2.6. Aramid & Blends
9.2.7. Polyolefin
9.2.8. UHMW Polyethylene
9.3. Market Analysis, Insights and Forecast - by Performance Level
9.3.1. Type 1
9.3.2. Type 2
9.3.3. Type 3
9.3.4. Type 4
9.3.5. Type 5
9.3.6. Type 6
9.4. Market Analysis, Insights and Forecast - by End-Use Industry
9.4.1. Chemical Manufacturing
9.4.2. Oil & Gas
9.4.3. Healthcare/Medical
9.4.4. Construction & Manufacturing
9.4.5. Firefighting & Law Enforcement
9.4.6. Military/Defense
9.4.7. Mining
9.4.8. Hazardous Waste
9.5. Market Analysis, Insights and Forecast - by User Type
9.5.1. Industrial
9.5.2. Personal
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Coveralls
10.1.2. Gloves
10.1.3. Aprons
10.1.4. Boots
10.1.5. Face Shields
10.2. Market Analysis, Insights and Forecast - by Material Type
10.2.1. Polyethylene
10.2.2. Polyvinyl Chloride
10.2.3. Nomex
10.2.4. Tyvek
10.2.5. Rubber
10.2.6. Aramid & Blends
10.2.7. Polyolefin
10.2.8. UHMW Polyethylene
10.3. Market Analysis, Insights and Forecast - by Performance Level
10.3.1. Type 1
10.3.2. Type 2
10.3.3. Type 3
10.3.4. Type 4
10.3.5. Type 5
10.3.6. Type 6
10.4. Market Analysis, Insights and Forecast - by End-Use Industry
10.4.1. Chemical Manufacturing
10.4.2. Oil & Gas
10.4.3. Healthcare/Medical
10.4.4. Construction & Manufacturing
10.4.5. Firefighting & Law Enforcement
10.4.6. Military/Defense
10.4.7. Mining
10.4.8. Hazardous Waste
10.5. Market Analysis, Insights and Forecast - by User Type
10.5.1. Industrial
10.5.2. Personal
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Chemical Protective Clothing Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Chemical Protective Clothing Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Chemical Protective Clothing Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Chemical Protective Clothing Market Revenue (Billion), by Material Type 2026 & 2034
Figure 5: North America Chemical Protective Clothing Market Revenue Share (%), by Material Type 2026 & 2034
Figure 6: North America Chemical Protective Clothing Market Revenue (Billion), by Performance Level 2026 & 2034
Figure 7: North America Chemical Protective Clothing Market Revenue Share (%), by Performance Level 2026 & 2034
Figure 8: North America Chemical Protective Clothing Market Revenue (Billion), by End-Use Industry 2026 & 2034
Figure 9: North America Chemical Protective Clothing Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 10: North America Chemical Protective Clothing Market Revenue (Billion), by User Type 2026 & 2034
Figure 11: North America Chemical Protective Clothing Market Revenue Share (%), by User Type 2026 & 2034
Figure 12: North America Chemical Protective Clothing Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Chemical Protective Clothing Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Chemical Protective Clothing Market Revenue (Billion), by Product Type 2026 & 2034
Figure 15: Europe Chemical Protective Clothing Market Revenue Share (%), by Product Type 2026 & 2034
List of Tables
Table 1: Chemical Protective Clothing Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Chemical Protective Clothing Market Revenue Billion Forecast, by Material Type 2020 & 2034
Table 3: Chemical Protective Clothing Market Revenue Billion Forecast, by Performance Level 2020 & 2034
Table 4: Chemical Protective Clothing Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 5: Chemical Protective Clothing Market Revenue Billion Forecast, by User Type 2020 & 2034
Table 6: Chemical Protective Clothing Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Chemical Protective Clothing Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 8: North America Chemical Protective Clothing Market Revenue Billion Forecast, by Material Type 2020 & 2034
Table 9: North America Chemical Protective Clothing Market Revenue Billion Forecast, by Performance Level 2020 & 2034
Table 10: North America Chemical Protective Clothing Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 11: North America Chemical Protective Clothing Market Revenue Billion Forecast, by User Type 2020 & 2034
Table 12: North America Chemical Protective Clothing Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Chemical Protective Clothing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Chemical Protective Clothing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Chemical Protective Clothing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the chemical protective clothing market size in 2026?
The global chemical protective clothing market is estimated at roughly US$14.1 billion in 2026, based on a synthesis of published certified-PPE estimates and industrial safety spending benchmarks.
2. What is the growth rate of the chemical protective clothing market?
Consensus forecasts point to approximately 6.8% CAGR through 2033, lifting the market to about US$22.3 billion as chemical, pharmaceutical and energy workforces expand.
3. Which region leads chemical protective clothing demand?
North America leads with roughly 35% share, supported by stringent OSHA-aligned exposure controls, while Asia Pacific is the fastest-growing region at around 4.0–4.7% annually.
4. Which product type dominates the chemical protective clothing market?
Coveralls dominate with about 40% revenue share because full-body protection remains the default specification for chemical handling, pharmaceuticals and hazardous-waste operations.
5. Who are the leading vendors in the chemical protective clothing market?
DuPont, 3M, Honeywell, MSA Safety, Ansell, Lakeland Industries, Sioen Industries and Kappler lead, differentiated by barrier technology, certification breadth and ensemble integration.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
We apply a 70/30 primary-to-secondary research split. In-depth interviews are conducted across the value chain with specialty polymer and textile suppliers, protective-garment manufacturers, laminate and coating specialists, and global industrial distributors. Decision-makers interviewed include VP-level sourcing executives, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring both technical and commercial validation of demand assumptions.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
40%
Procurement & Sourcing Leads
35%
Regulatory & Compliance Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Polymer & Textile Producers
40%
Protective Garment Manufacturers
35%
Industrial Distributors & Traders
25%
Secondary Benchmarking & Public Trade Validation
Estimates are benchmarked against UN Comtrade and WTO trade flows, US ITC and Eurostat import/export data, corporate 10-K and SEC filings, investor presentations, patent databases, and recognized technical standards bodies and industry associations. No third-party market-research publisher data is treated as primary evidence.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic output and end-use industry allocation) and Bottom-Up (manufacturer capacity, product pricing and end-use consumption) models, reconciling the two into a single triangulated value.
 Chemical Protective Clothing Market