 Luxury Shuttle Bus Market
 Size, Share & Forecast to 2035
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 257

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Luxury Shuttle Bus Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 5.240 B |
| 2026 | 5.660 B |
| 2027 | 6.110 B |
| 2028 | 6.590 B |
| 2029 | 7.110 B |
| 2030 | 7.670 B |
| 2031 | 8.280 B |

The Luxury Shuttle Bus Market covers premium, high-amenity group-transport vehicles—typically 15 to 60 seats—engineered for scheduled or chartered passenger movement. Offerings bundle reclining leather seating, onboard Wi-Fi, climate control, and increasingly electric powertrains, sold to tour operators, corporate campuses, airports, hotels, and public-sector fleets.
This report covers global demand for luxury shuttle buses across seating-capacity classes (below 25, 25–40, and above 40 passengers), propulsion types, applications (tourist coach, corporate transport, airport shuttle, government, school, medical), and end-user categories, with regional breakdowns for 2021–2035. It analyzes OEM shipments, fleet procurement, pricing, and competitive positioning. This analysis does not cover mass-transit city buses, standard school buses, limousines, or ride-hailing platforms.
Published estimates diverge materially: one analysis values the 2025 market at USD 5.24 Billion with a 7.93% CAGR to 2035, while a competing assessment places 2025 at USD 4.91 Billion and projects USD 7.39 Billion by 2030 at 8.51%. A third benchmark cites USD 4.1 Billion in 2023 growing to USD 10 Billion by 2033. The spread reflects differing definitions—some include all coach-class vehicles, others restrict to premium-amenity configurations.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 5.24 Billion | 2025 | 2035 | 7.93% | Premium shuttle buses, all propulsion, global | One published estimate |
| USD 4.91 Billion | 2025 | 2030 | 8.51% | Luxury shuttle buses, narrower amenity definition | A competing analysis |
| USD 4.1 Billion | 2023 | 2033 | 9.3% | Broad coach-class inclusion | Another published benchmark |
Our analysis suggests the USD 5.24 Billion base is the most defensible for buyer planning: it aligns with 2024's ~1.4 billion international tourist arrivals and corporate Scope 3 reporting timelines, which disproportionately lift premium-amenity configurations. The lower 2030-horizon figure likely underweights the post-2030 electrification replacement cycle.
Segmentation follows four axes—seating capacity, propulsion, application, and end user—each with distinct growth velocities. Below-25-seat shuttles are the fastest-expanding capacity class at ~8.65% CAGR, while electric powertrains grow at 11.6% CAGR, more than triple the diesel segment's trajectory.
| Parent Segment | Children |
|---|---|
| Seating Capacity | Below 25 Passengers; 25–40 Passengers; Above 40 Passengers |
| Propulsion Type | Diesel/Gasoline; Electric; Hybrid; Alternate Fuels |
| Application | Tourist Coach; Corporate Transport; Airport Shuttle; Government Use; School; Medical; Others |
| End User | Private Operators; Hospitality & Tourism Providers; Government & Public Sector |
Asia-Pacific leads with roughly 38.5%–45% share in 2025, depending on definition, and is also the fastest-growing region at ~9.3% CAGR. China's new-energy vehicle supply chain and India's PM e-Bus Sewa program (10,000 e-buses) provide structural cost advantages that export into ASEAN and Middle Eastern premium fleets.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.39% |
| North America | 0.28% |
| Europe | 0.22% |
| Middle East & Africa | 0.06% |
| Latin America | 0.05% |
North America ranks second at ~27.6% global revenue, generating USD 1.36 Billion in 2025 and projected to reach USD 2.37 Billion by 2033 at 7.32% CAGR. The Middle East & Africa is the fastest-growing emerging region at ~8.6% CAGR, driven by Saudi and UAE tourism megaprojects.
Six drivers collectively add roughly 6.4 percentage points to CAGR, led by tourism recovery (+1.4%), ESG-linked corporate commuting (+1.2%), and zero-emission mandates (+1.1%). Restraints—chiefly high acquisition cost (−1.4%) and ride-hailing/rail competition (−1.1%)—are real but secondary.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Tourism rebound & premium group travel | Driver | High | 1.4B arrivals in 2024; higher per-trip spend on curated group itineraries |
| Corporate ESG commuter programs | Driver | High | EU CSRD Scope 3 disclosure makes shuttle replacement of car trips reportable |
| Zero-emission procurement mandates | Driver | High | EU 2024/1610 requires 90% zero-emission new city buses by 2030 |
| Asia-Pacific e-bus incentives | Driver | Medium-High | India PM e-Bus Sewa targets 10,000 e-buses; China supply-chain scale |
| Airport passenger growth | Driver | Medium | IATA expects ~5B passengers in 2025; terminal expansions embed premium concessions |
| Falling battery pack costs | Driver | Medium | Pack prices fell ~20% in 2024 to USD 115/kWh, improving TCO |
| High upfront acquisition & customization | Restraint | High | Premium electric coaches cost 30–50% more than diesel equivalents |
| Ride-hailing & premium rail competition | Restraint | Medium | Compresses intercity and on-demand business-travel demand |
| Driver shortages | Restraint | Medium | Wage inflation and licensing constraints in developed markets |
The balance favors growth: regulation and ESG reporting are structural and non-cyclical, whereas cost pressures ease as battery prices decline. Our analysis suggests the net driver impact (~+5.1 percentage points after restraints) is consistent with the 7.9% headline CAGR.
Daimler Truck (Mercedes-Benz Setra), Zhengzhou Yutong, AB Volvo, Traton (MAN), Xiamen King Long, and BYD anchor a medium-concentration market. Differentiation rests on electrification portfolios, connected-cabin software, and service-network depth rather than sticker price alone.
| Company | HQ | Strategic Strength |
|---|---|---|
| Daimler Truck AG (Mercedes-Benz Setra) | Germany | Premium brand equity; electric coach R&D |
| Zhengzhou Yutong Bus | China | Largest e-bus manufacturing scale; export cost advantage |
| AB Volvo | Sweden | Safety leadership; global service network |
| Traton SE (MAN Truck & Bus) | Germany | Fleet telematics; European tender access |
| Xiamen King Long | China | Volume competitiveness in Asia-Pacific and MEA |
| BYD Company | China | Integrated battery supply chain; TCO leadership |
Our analysis suggests the strongest moat belongs to OEMs that bundle vehicle, charging, and fleet-management software—shifting competition from unit price to lifetime cost-per-passenger-km and locking operators into multi-year service contracts.
Procurement decisions hinge on total cost of ownership rather than acquisition price. Electric coaches now reach five-year payback in subsidized jurisdictions, but corridor charging gaps on intercity routes remain a genuine constraint; buyers should model route-specific charging availability before committing. Regulatory compliance is non-negotiable—EU Regulation 2024/1610 and equivalent U.S. FTA tender specifications increasingly exclude diesel-only bids, so resale value and route eligibility both favor zero-emission platforms. Switching costs are highest for operators holding proprietary booking and dispatch software; interoperability should be a scored criterion. Finally, driver shortages mean ergonomic cab design and retention-friendly scheduling carry measurable operating value, not merely passenger comfort.
The balance of evidence favors a structural, regulation-anchored growth story rather than a cyclical tourism trade. The 7.9% consensus CAGR is credible because its largest drivers—EU CSRD Scope 3 reporting and 2024/1610 zero-emission mandates—are legislated, not discretionary. The strongest counter-argument is that high upfront cost and charging gaps could delay adoption in emerging markets; however, falling pack prices and Asian incentive programs partially neutralize this.
For operators, the winning posture is to secure electric platforms and software-enabled service contracts before diesel residual values compress. The corporate commuter segment, growing at 9.2% CAGR, offers higher contract durability than seasonal tourism and should anchor fleet financing.
Actionable strategy:
What would change our conclusion: sustained battery price reversal, delayed enforcement of EU 2024/1610, or a sharp tourism contraction exceeding two consecutive years would materially lower the growth trajectory.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
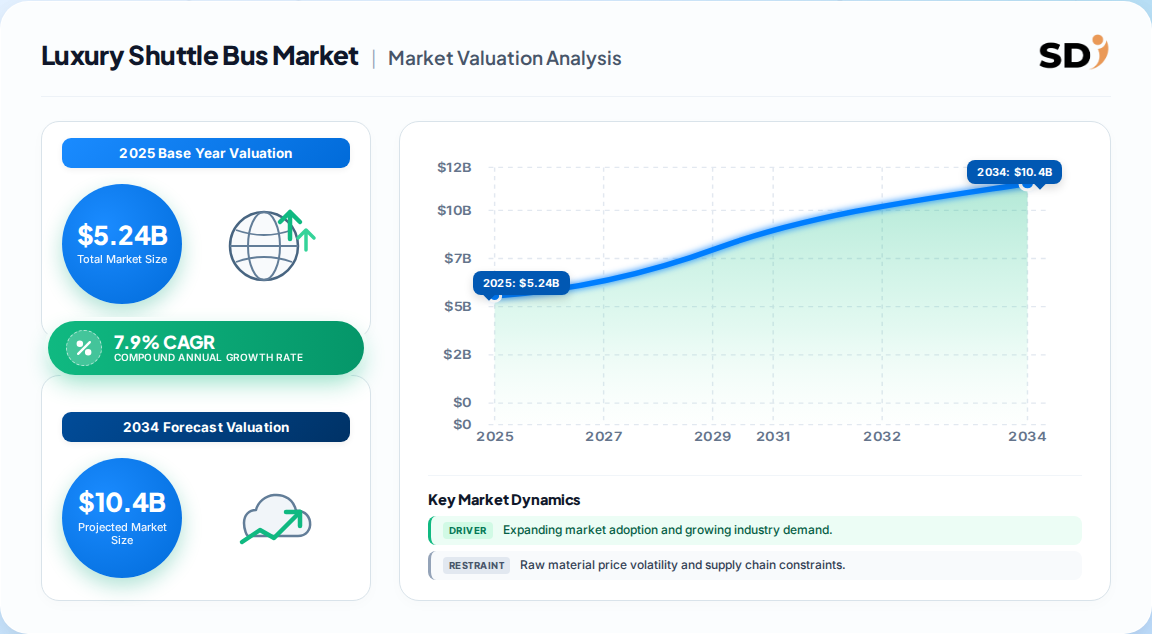
The global Luxury Shuttle Bus Market was valued at approximately USD 5.24 Billion in 2025, with forecasts reaching USD 11.25 Billion by 2035 at a 7.93% CAGR.
Asia-Pacific leads with roughly 39% share in 2025, supported by China's manufacturing scale and India's e-bus subsidy programs. North America ranks second at about 28%.
Battery-electric powertrains are the fastest-growing segment, advancing at approximately 11.6% CAGR through 2035 as battery costs decline and zero-emission mandates tighten.
Leading vendors include Daimler Truck (Mercedes-Benz Setra), Zhengzhou Yutong Bus, AB Volvo, Traton (MAN), Xiamen King Long, and BYD Company.
Tourism recovery, corporate ESG commuter programs, zero-emission procurement mandates, airport expansion, and falling battery costs are the principal drivers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain: chassis and battery suppliers, bus body manufacturers, luxury interior outfitters, fleet operators, and global distributors. We targeted decision-makers including VP of Fleet Procurement, Head of Product Development, Commercial Operations Leads, and Sustainability/Compliance Directors at operating companies and OEMs.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Fleet Procurement Leads | 35% |
| Product Development & Engineering Heads | 30% |
| Commercial Operations Leads | 20% |
| Sustainability & Compliance Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Chassis & Battery Suppliers | 30% |
| Bus Body Manufacturers & OEMs | 40% |
| Fleet Operators & Distributors | 30% |
Demand estimates are validated against official multilateral trade data (UN Comtrade, WITS/World Bank), corporate annual filings and investor presentations, patent databases, and recognized technical standards bodies. Regulatory benchmarks include EU Regulation 2024/1610 and U.S. Federal Transit Administration program records.
We triangulate top-down macroeconomic and segment allocation models against bottom-up manufacturer shipment data, average selling prices by seating class, and end-use consumption modeling, reconciling discrepancies at the segment level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |