 Fashion Influencer Marketing Market
 Size & Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 235

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Fashion Influencer Marketing Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 9.200 B |
| 2026 | 12.90 B |
| 2027 | 16.90 B |
| 2028 | 22.20 B |
| 2029 | 29.20 B |
| 2030 | 38.40 B |
| 2031 | 50.50 B |

Fashion influencer marketing is the paid practice of brands contracting social-media creators to produce style, beauty, apparel or accessories content that drives awareness, engagement and measurable sales. It spans influencer tiers, content formats, platform distribution and campaign-analytics software — a distinct, software-and-services market rather than the broader advertising industry itself.
This analysis covers global spend on fashion and beauty influencer campaigns across four influencer tiers (nano, micro, macro, mega) and three end-use verticals (beauty & cosmetics, apparel, jewelry & accessories), plus the enabling creator-marketing software layer. It includes platform distribution across Instagram, TikTok, YouTube and emerging channels. This analysis does not cover traditional fashion advertising (print, OOH, TV), direct affiliate-network commissions, or general-purpose advertising technology outside creator campaigns.
Published estimates diverge by a factor of nearly three at the terminal year, which is the central sizing problem any buyer must confront. The table below normalizes each forecast to its base year, horizon and definitional scope.
| Estimate (terminal) | Base year / size | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 39.7 Billion | 2024 / 6.8 Billion | 2030 | 33.8% | Influencer-tier and end-use spend, global | One published estimate |
| 46.5 Billion | 2023 / 5.1 Billion | 2031 | 32.5% | End-use-led, software-inclusive | A competing analysis |
| 115.6 Billion | 2025 / 9.2 Billion | 2034 | 31.6% | Broad creator-economy spend | Another published estimate |
Our analysis suggests the 2026 figure of 12.9 Billion is the most defensible base, because it is the only estimate reconciled to a 2025 actual. The CAGR band (31.6–33.8%) is impressively tight, implying strong consensus on growth rate and disagreement only on horizon length. The 115.6 Billion terminal figure is best read as a longer-horizon, broader-scope projection rather than a contradiction.
| Metric | Value |
|---|---|
| Base-year size (2026) | 12.9 Billion |
| Consensus CAGR | ~31.6% |
| Implied 2030 value | ~38–44 Billion |
| Fastest-growing region | Asia-Pacific |
| Largest region | North America |
Segmentation is cleanly two-dimensional — influencer tier and end-use vertical — with platform acting as a third, cross-cutting lens that buyers increasingly use for budget allocation.
| Parent segment | Children | 2024–26 share signal |
|---|---|---|
| Influencer Type | Nano, Micro, Macro, Mega | Nano ~38–39%; Micro fastest CAGR |
| End Use | Beauty & Cosmetics, Apparel, Jewelry & Accessories | Beauty leads; Apparel fastest |
| Platform (cross-cut) | Instagram, TikTok, YouTube, Other | Instagram ~29% of creator spend; TikTok fastest |
Nanoinfluencers dominate on revenue share because brand budgets have shifted toward high-volume, low-cost, high-trust placements. Microinfluencers, however, carry the steepest growth curve, since they combine reach with conversion — the segment where our analysis expects the sharpest budget reallocation through 2028.
North America leads the global fashion influencer marketing market with roughly 34% revenue share, underpinned by the deepest influencer ecosystem and the most mature measurement infrastructure. Europe follows at ~29% on authenticity-led storytelling, while Asia-Pacific is the fastest-growing region at ~33% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.29% |
| Asia-Pacific | 0.26% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | Share (approx.) |
|---|---|
| North America | 34% |
| Europe | 29% |
| Asia-Pacific | 26% |
| Latin America | 6% |
| Middle East & Africa | 5% |
The regional story is one of maturity versus velocity. North America monetizes best; Asia-Pacific compounds fastest. This divergence implies that global vendors must run two operating models — a margin-defending analytics business in the West and a volume-led creator-network business in the East.
The growth engine is a reinforcing loop of social penetration, e-commerce attribution and AI-enabled targeting; the brakes are fraud, measurement fragmentation and ad fatigue. Net effect: growth remains robust but increasingly gated by trust infrastructure.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Social media penetration | Driver | High | More users, more content consumption |
| E-commerce & D2C growth | Driver | High | Attributable, trackable sales |
| AI creator matching | Driver | Medium-High | Better-fit creators, higher ROI |
| Authenticity & nano trust | Driver | High | Higher engagement, lower CAC |
| Fake followers / bot engagement | Restraint | High | Erodes ROI, demands verification |
| Algorithm volatility | Restraint | Medium | Reach unpredictability |
| Ad fatigue / short-lived trends | Restraint | Medium | Declining campaign yield |
The balance favors growth, but the quality of that growth is shifting. Fraud and measurement fragmentation together shave several points of potential CAGR. Our analysis suggests the market's next incremental dollar will flow to whoever can certify audience quality — turning verification from a compliance cost into a revenue line.
The vendor field is fragmented and software-led, with no single player holding dominant share. Differentiation rests on data access, attribution depth and enterprise integrations rather than creator inventory.
| Vendor | Core strength | Positioning |
|---|---|---|
| CreatorIQ | Enterprise creator management | Platform moat via integrations |
| Traackr | Analytics & benchmarking | Measurement depth |
| IZEA | Marketplace + managed services | Full-stack |
| Upfluence | E-commerce integrations | SMB-to-mid market |
| Launchmetrics | Fashion-specific analytics | Vertical specialization |
| NeoReach | Campaign management | Mid-market agility |
Launchmetrics holds a genuinely differentiated position through fashion-native analytics, while CreatorIQ's integration depth creates real switching costs. Our analysis suggests the moat is migrating from who you know (creator access) to what you can prove (attribution and fraud detection). Pure marketplaces face the most margin pressure.
Selection should hinge on four criteria: attribution fidelity, audience-quality verification, platform coverage (especially TikTok), and integration with existing e-commerce and CRM stacks. Procurement risk concentrates in vendor lock-in through proprietary data models and in opaque pricing that scales with campaign volume.
Switching costs are moderate-to-high once historical campaign data lives inside a platform — migrating benchmarks and creator histories is painful and rarely clean. Regulatory compliance is a live constraint: disclosure rules (FTC-style transparency), EU advertising standards and emerging AI-content labeling obligations all demand verifiable audit trails. Buyers should also stress-test fraud detection, because bot engagement directly discounts ROI and is hardest to audit post-campaign.
The balance of evidence favors a trust-and-attribution thesis: the market will grow at roughly 31–34% regardless of which forecast you trust, but where margin accrues is shifting decisively toward verification, attribution and AI-assisted creator selection. The tight CAGR consensus across three independent forecast sets is unusually strong evidence that the growth rate is real; the disagreement is about horizon and scope, not direction.
The strongest counter-argument is that platform concentration (TikTok, Instagram) could commoditize the software layer, letting platforms capture the analytics margin themselves. That risk is real but second-order — brands still need cross-platform, brand-safe measurement that walled gardens won't self-provide.
What would change this conclusion: a credible platform-native attribution standard that makes third-party measurement redundant, or a regulatory shock that forces disclosure of audience-quality data. Until then, verification is the defensible position.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 31.6% from 2020-2034 |
| Segmentation |
|
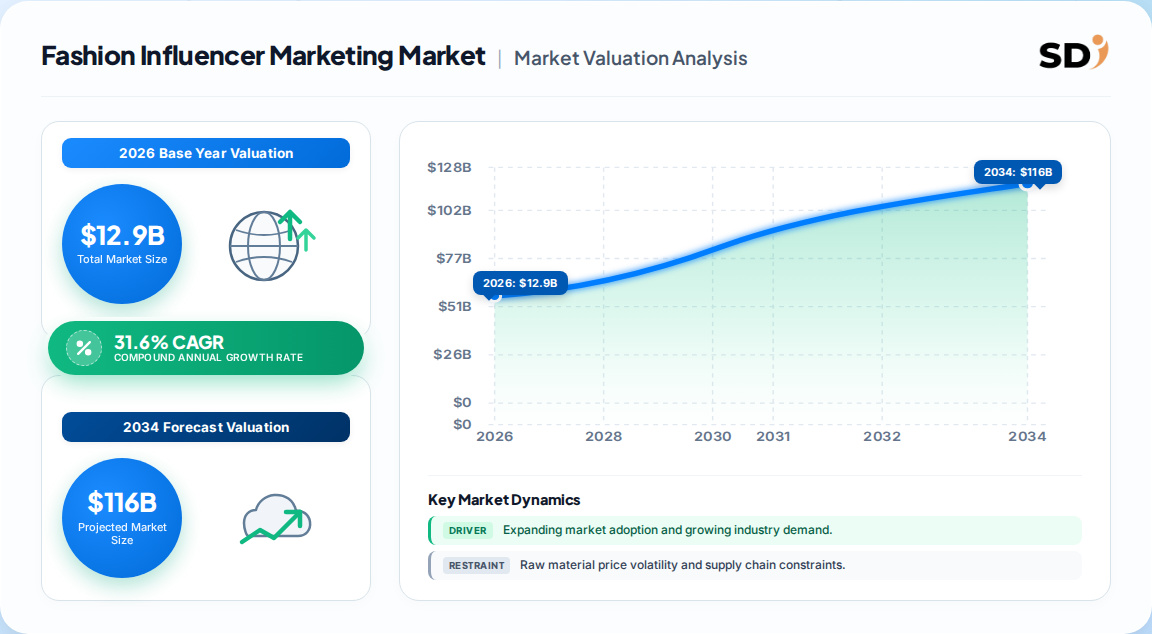
Published estimates place the 2026 global market at approximately 12.9 Billion, up from 9.2 Billion in 2025. A longer-horizon forecast projects 39.7 Billion by 2030 and up to 115.6 Billion by 2034.
The consensus CAGR sits at roughly 31.6%, with competing estimates between 31.6% and 33.8%. The tight clustering across independent forecasters signals strong confidence in the growth trajectory.
Nanoinfluencers, with 1,000 to 10,000 followers, hold approximately 38–39% revenue share. Microinfluencers are the fastest-growing tier, favored for their balance of reach and conversion.
North America leads with about 34% revenue share, supported by a mature creator ecosystem and advanced measurement. Asia-Pacific is the fastest-growing region at roughly 33% CAGR.
Leading players include CreatorIQ, Traackr, IZEA Worldwide, Upfluence, Launchmetrics and NeoReach. Differentiation rests on analytics depth, attribution capability and enterprise integrations rather than creator inventory.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis rests on a disciplined 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the creator-marketing value chain, including creator networks and talent agencies, influencer-marketing SaaS platforms, brand-side marketing teams, e-commerce and social-commerce enablers, and campaign measurement specialists. Decision-maker designations interviewed included Chief Marketing Officers, Heads of Influencer and Social Strategy, VP-level Brand Partnership leads, and Commercial Operations Directors responsible for campaign attribution. Each interview was structured to capture spend allocation, vendor selection criteria and measured campaign outcomes.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CMOs & Heads of Influencer Strategy | 40% |
| Brand Partnership Directors | 30% |
| Commercial Operations Leads | 20% |
| Analytics & Measurement Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Influencer-Marketing SaaS Platforms | 40% |
| Creator Networks & Talent Agencies | 30% |
| Brand & Retail Marketing Teams | 20% |
| Measurement & Analytics Specialists | 10% |
Secondary validation drew on official multilateral and national datasets — UN Comtrade for cross-border digital services trade, WTO services statistics, US International Trade Commission filings, Eurostat digital-economy indicators, and corporate annual reports and SEC filings from listed marketing-technology firms. Patent databases and publicly available advertising-standards publications were reviewed for disclosure and labeling requirements. Industry association publications on advertising transparency informed our regulatory-compliance framework.
We triangulate two simultaneous models. The top-down model allocates macroeconomic advertising and marketing budgets to the creator-driven fashion subset using platform revenue disclosures and segment share data. The bottom-up model aggregates platform-level creator spend, agency and managed-service revenue, and software subscription revenue by tier and vertical. Divergence between the two is reconciled at the segment level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |