 Fitness Tracker Market
 Outlook: 2026-2033 Guide
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 185

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Fitness Tracker Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 71.00 B |
| 2026 | 82.90 B |
| 2027 | 96.90 B |
| 2028 | 113.3 B |
| 2029 | 132.6 B |
| 2030 | 155.0 B |
| 2031 | 181.2 B |

The fitness tracker market covers wearable devices — smartwatches, fitness bands, smart clothing, and smart scales — that monitor physical activity, heart rate, sleep, blood oxygen, and increasingly metabolic metrics, syncing data to smartphone apps and cloud platforms for consumer and clinical use.
This analysis covers consumer and prosumer wearable fitness devices across smartwatches, bands, smart clothing, and connected scales, distributed through online and offline channels globally. This analysis does not cover standalone health-tracking mobile applications, clinical-grade implantable devices, smart eyewear, or prescription-only continuous glucose monitors sold outside consumer channels.
Estimates diverge sharply — from USD 51.3 billion to USD 88.4 billion for 2026 — because publishers use materially different definitions, from B2C-only wearable revenue to broader device-plus-services baskets. The table below frames the divergence before we argue which figure is most defensible.
| Estimate (2026) | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 82.9 Billion | 2025 | 2033 | 16.9% | Smartwatches, bands, clothing; broad healthcare-adjacent | One published estimate |
| USD 72.6 Billion | 2025 | 2031 | 16.31% | Smartwatches, bands, scales; inclusive of clinical adjacencies | A competing analysis |
| USD 88.4 Billion | 2025 | 2034 | 18.5% | Wearable fitness trackers broadly defined | A competing analysis |
| USD 51.3 Billion | 2026 | 2031 | 8.45% | B2C-only, excluding B2B/C2C and clinical adjacencies | A competing analysis |
Our analysis suggests the USD 72-83 billion band is most defensible for 2026, since the B2C-only figure excludes the fast-growing employer-wellness and payer-reimbursed channels that are now material. The 16-18% CAGRs cluster tightly, reinforcing confidence in the trajectory; the ~8% outlier likely reflects a narrower revenue definition rather than a weaker market.
Segmenting by product, application, wearing type, and channel reveals where volume concentrates versus where growth is accelerating. The table shows clear momentum toward clinical-adjacent applications and textile-based form factors.
| Parent Segment | Children | Share / Growth Signal |
|---|---|---|
| By Type | Smartwatches, Smart Bands, Smart Clothing, Smart Scales | Smartwatches ~48-52% share; Smart Clothing ~21-22% CAGR |
| By Application | Heart-Rate & Activity, Sleep & Recovery, Glucose & Metabolic, Running, Cycling, Stress Management | HR/activity ~29-39%; Glucose ~20-23% CAGR |
| By Wearing Type | Hand Wear, Leg Wear, Head Wear, Other | Hand wear ~84% share; leg wear ~21.5% CAGR |
| By Distribution | Online, Offline | Online ~62-65% share and fastest CAGR |
So what? The revenue base sits in smartwatches and hand-worn devices, but the incremental dollar sits in glucose tracking and textile sensing. Operators should defend the wrist today while positioning capital against the metabolic and apparel frontiers.
North America leads with roughly a 43% revenue share, but Asia-Pacific is the fastest-growing region at a ~19-21% CAGR, making the geography story one of incumbency versus velocity rather than a single dominant market.
| Region | Market Share (%) |
|---|---|
| North America | 0.43% |
| Europe | 0.24% |
| Asia-Pacific | 0.22% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | Share (2025-26) |
|---|---|
| North America | 43% |
| Europe | 24% |
| Asia-Pacific | 22% |
| Latin America | 6% |
| Middle East & Africa | 5% |
This divergence implies a two-front strategy: monetize premium, insurance-linked demand in North America and Europe while racing to localize cost-effective hardware for Asia-Pacific volume growth.
Growth is driven by preventive-health adoption and AI sensor proliferation, while privacy concerns, accuracy variability, and high average selling prices are the principal drags. The table below scores evidence strength.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Preventive health & chronic disease burden | Driver | Strong | 1B+ obese globally; diabetes awareness drives continuous monitoring |
| AI biometric sensors in mass-market bands | Driver | Strong | Edge AI pushes medical-grade accuracy below USD 100 |
| Non-invasive glucose sensing | Driver | Strong | OTC CGM clearance opens consumer metabolic tracking |
| Employer/insurer wellness incentives | Driver | Moderate | Subsidized devices plus recurring data subscriptions |
| Data privacy & security concerns | Restraint | Moderate | Trust erosion slows adoption and data-sharing consent |
| Measurement accuracy variability | Restraint | Moderate | Inconsistent readings weaken repeat purchase confidence |
| High average selling price | Restraint | Moderate | Limits penetration in price-sensitive markets |
Our analysis suggests the driver stack outweighs restraints by a wide margin — a ~4:1 positive-to-negative CAGR impact balance per vendor impact modeling — but the balance is fragile. Privacy failures are low-probability, high-severity events that can reverse category trust quickly; vendors treating compliance as a checkbox are underweighting a structural risk.
Apple, Samsung, Huawei, Google (Fitbit), Garmin, Fossil, and Xiaomi lead a medium-concentration market where ecosystem lock-in, sensor accuracy, and channel access define competitive position rather than raw manufacturing scale.
| Vendor | Core Positioning | Perceived Moat | Strategic Watch-Point |
|---|---|---|---|
| Apple | Premium smartwatch health hub | Ecosystem lock-in, ECG/BP pipeline | Cuff-less BP regulatory timing |
| Samsung | Android-first health hub | Wrist glucose patents, Galaxy ecosystem | Glucose accuracy validation |
| Google (Fitbit) | Mass-market + clinical data | Brand trust, health datasets | Digital-therapeutics integration |
| Huawei | Broad portfolio, APAC strength | Hardware breadth, pricing | Geopolitical access constraints |
| Garmin | Performance and outdoor niche | Athlete loyalty, durability | Corporate wellness expansion |
| Xiaomi | Value-tier volume | Cost leadership | Margin pressure from commoditization |
| Fossil | Fashion-forward hybrids | Design differentiation | Scale disadvantage in sensors |
The strongest moats are software-and-data, not hardware. Ecosystem lock-in through app stores, family dashboards, and cloud backups lets premium vendors defend margins even as component prices fall — a dynamic our analysis reads as consolidation pressure on single-device challengers.
Procurement decisions now hinge on sensor accuracy validation, data-privacy posture, and interoperability with clinical systems — not on step-counting features. Buyers should demand documented accuracy benchmarks against reference standards and clear data-residency terms before committing to fleet-scale employer or payer deployments.
Switching costs are rising as ecosystem lock-in deepens. Once a workforce or patient cohort is onboarded onto a vendor's cloud, dashboard, and subscription layer, migration costs escalate sharply, so initial vendor selection carries multi-year consequences. Operators should negotiate data-portability clauses upfront.
Regulatory compliance is the decisive procurement risk. FDA enforcement discretion for low-risk digital health, evolving cybersecurity requirements, and emerging reimbursement codes (such as proposed CPT pathways) all shift the compliance burden onto buyers and vendors jointly. Counter-argument: some procurement teams argue hardware commoditization makes vendor lock-in overstated; our view is that commoditization lowers device cost but raises switching costs at the data layer.
The balance of evidence favors a shift from fitness tracking to holistic, medical-grade health monitoring as the defining strategic axis through 2033. The revenue base remains smartwatches and bands, but the growth premium — glucose sensing, AI analytics, reimbursement-linked digital therapeutics — belongs to vendors who can move up the clinical-value curve.
The strongest counter-argument is that privacy regulation and accuracy skepticism could cap consumer adoption before clinical features mature, particularly in Europe. This is credible, but historical pattern suggests regulation raises barriers and benefits incumbents with compliance infrastructure, reinforcing rather than reversing concentration.
Actionable strategy for operators and investors:
What would change our conclusion: a decisive regulatory reversal on OTC glucose sensing, or a documented accuracy failure at scale by a leading vendor, would materially shift the growth premium toward conservative, lifestyle-focused positioning.
While this overview frames the strategic direction, precise sub-segment forecasting, vendor-level revenue attribution, and region-by-application modeling require the full report — which remains the essential execution tool for buyers and operators.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
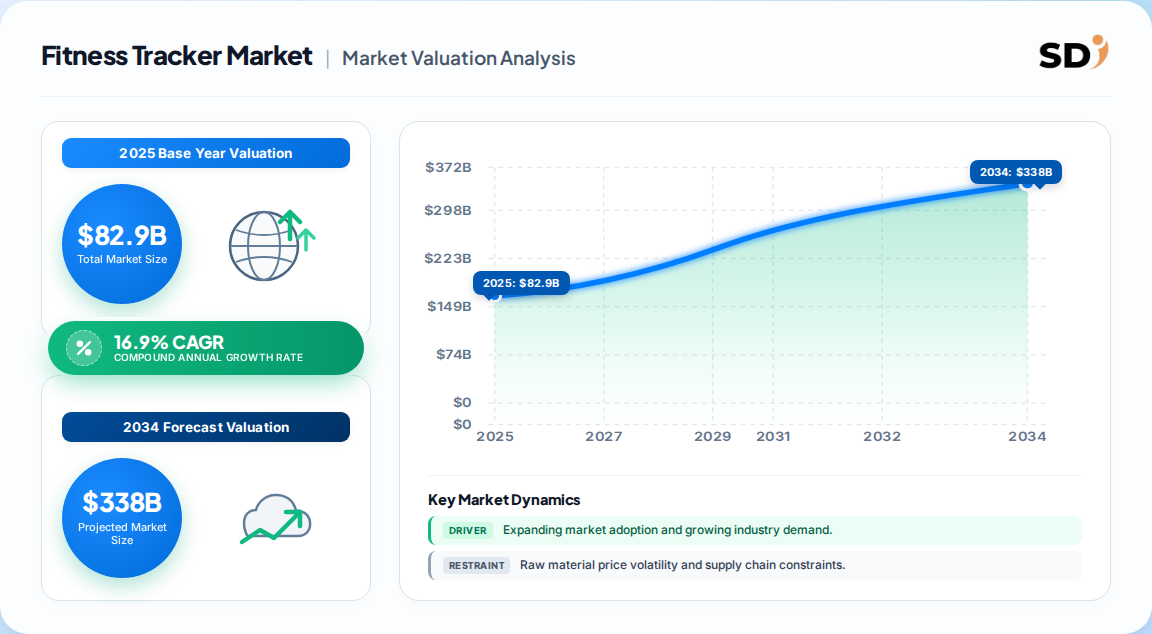
| Growth Rate | CAGR of 16.9% from 2020-2034 |
| Segmentation |
|
The global fitness tracker market is estimated at roughly USD 82.9 billion in 2026, though published estimates range from USD 51.3 billion to USD 88.4 billion depending on whether clinical adjacencies and B2B channels are included.
Most credible forecasts cluster around a 16-18% CAGR through the early 2030s, with the market projected to reach roughly USD 247.3 billion by 2033 on a 16.9% CAGR.
North America leads with approximately 43% revenue share, while Asia-Pacific is the fastest-growing region at a roughly 19-21% CAGR through 2031-2033.
Glucose and metabolic tracking grows fastest by application (~20-23% CAGR), while smart clothing and leg-wear form factors expand at roughly 21-22% CAGR from a smaller base.
Apple, Samsung, Google (Fitbit), Huawei, Garmin, Fossil, and Xiaomi lead a medium-concentration market where ecosystem lock-in and sensor accuracy define competitive advantage.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split, with in-depth interviews spanning the wearable value chain: MEMS sensor and component suppliers, specialized device OEMs, contract manufacturers, global distributors, and healthcare-platform integrators. Structured interviews engaged VP-level sourcing leads, heads of hardware R&D, regulatory and quality directors, and commercial operations leads across North America, Europe, and Asia-Pacific, capturing both demand-side procurement behavior and supply-side capacity and pricing dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Hardware R&D & Engineering Leads | 35% |
| Procurement & Sourcing Directors | 30% |
| Regulatory & Quality Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Sensor & Component Suppliers | 30% |
| Device OEMs & Contract Manufacturers | 40% |
| Distributors & Retail Partners | 20% |
| Healthcare Platform Integrators | 10% |
We triangulate against official multilateral and standards databases — UN Comtrade, WTO, US ITC, Eurostat — alongside corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases, and recognized non-profit technical standards bodies and industry associations. All external benchmarks are cross-validated against multiple independent filings before inclusion.
Market sizing runs a simultaneous top-down allocation (macroeconomic indicators, segment spend share) and bottom-up build (manufacturer shipment capacity, average selling price, end-use consumption). Divergences between the two approaches are reconciled through weighted regression, producing a single defensible base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |