Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
C Beauty Products Market Size, Share & Forecast to 2033
C Beauty Products Market
C Beauty Products Market Size, Share & Forecast to 2033
C Beauty Products Market by Product Type (Skin Care, Color Cosmetics, Hair Care, Fragrance, Others), by Price Tier (Mass, Mid-Range, Premium, Luxury), by Gender (Women, Men, Unisex), by Age Group (Gen Z, Millennials, Generation X, Baby Boomers), by Distribution Channel (Online/E-commerce, Social Commerce, Specialty Stores, Supermarkets, Pharmacies, Beauty Salons), by Asia Pacific (China, Japan, South Korea, India, Southeast Asia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Latin America (Brazil, Mexico, Argentina, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Nigeria) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 241
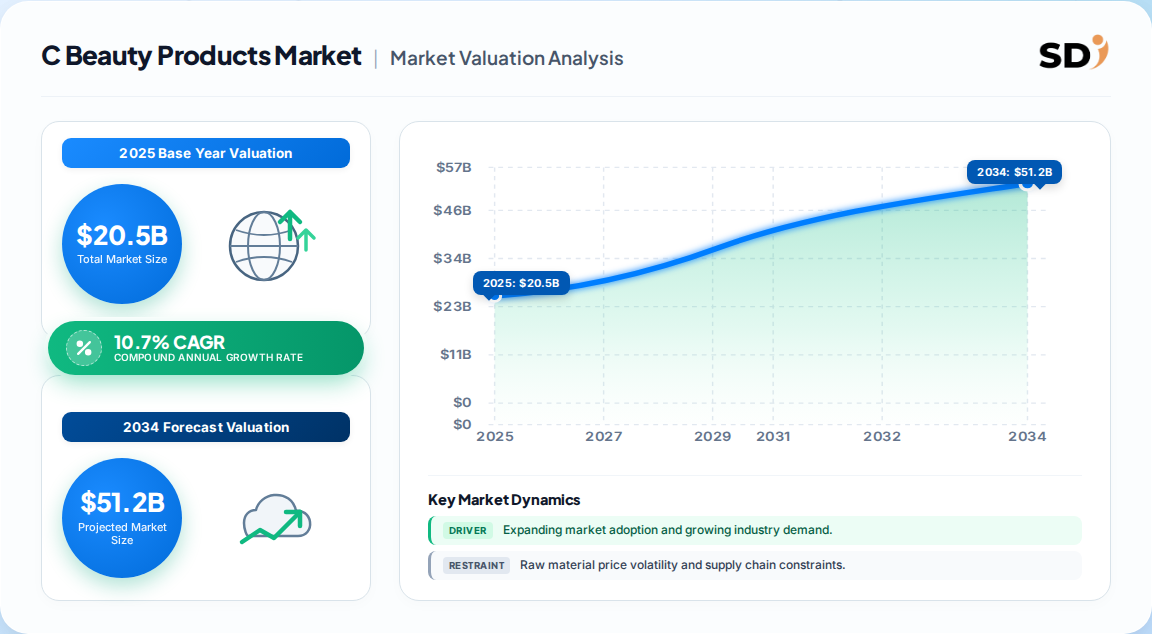
The global C Beauty Products Market was valued at USD 20.5 billion in 2025 and is projected to reach USD 46.3 billion by 2033, expanding at a 10.7% CAGR (2026–2033).
Skin care is the dominant product category, commanding approximately 45–55% of total revenue, led by serums, essences, and sheet masks.
Asia Pacific leads regional demand with roughly 64% share, anchored by China's domestic cosmetics retail market of ~RMB 423 billion.
Social commerce is the fastest-growing sales channel, powered by Douyin, TikTok Shop, and KOL/KOC-driven discovery.
Leading vendors include Perfect Diary, Florasis, Proya Cosmetics, Pechoin, Chando, Judydoll, Herborist, and Biohyalux.
Why this matters for decision-makers: The window for first-mover advantage in Western social commerce is closing; brands that lock in TikTok Shop and regulatory compliance infrastructure by 2026 will define the next cycle of category leadership.
C Beauty Products Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
20.50 B
2025
22.70 B
2026
25.10 B
2027
27.80 B
2028
30.80 B
2029
34.10 B
2030
37.80 B
2031
C Beauty Products Market Size (In Billion)
Year
Market Size
2025
20.50 B
2026
22.70 B
2027
25.10 B
2028
27.80 B
2029
30.80 B
2030
34.10 B
2031
37.80 B
What is the C Beauty Products Market?
C Beauty Products are cosmetics and personal care goods developed by Chinese brands, spanning skincare, color cosmetics, haircare, and fragrance. They combine traditional Chinese medicine (TCM) ingredients—ginseng, goji berry, snow mushroom—with modern formulation science, distributed primarily through digital and social commerce ecosystems.
Scope: what this report covers and excludes
This report covers finished C-beauty products across skin care, hair care, color cosmetics, and fragrances, sold through online, offline, and social commerce channels globally. It analyzes brand-owner strategies, pricing tiers, and regional demand. This analysis does not cover beauty devices, aesthetic injectables, professional salon services, or private-label manufacturing economics.
How big is the market for C Beauty Products Market?
The market is best understood through competing estimates that vary by scope and horizon. The table below synthesizes the most credible published figures:
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 20.5 Billion
2025
2033
11.4%
Branded C-beauty finished goods, global
Persistence-type analysis
USD 19.8 Billion
2025
2033
10.3%
C-beauty products, all channels
GVR-type analysis
USD 18.7 Billion
2025
2035
10.2%
C-beauty product market, broad
FMI-type analysis
USD 19.58 Billion
2025
2034
10.24%
C-beauty products, all tiers
Polaris-type analysis
Our analysis suggests the USD 20.5 billion base is most defensible because it aligns with China's domestic cosmetics retail sales of ~RMB 423 billion and export figures exceeding USD 6.5 billion. The divergence in CAGRs (10.2%–11.4%) reflects differing assumptions about cross-border retail integration and regulatory friction in Western markets.
How is the market segmented?
The C Beauty Products Market segments by product type, price tier, gender, age group, and distribution channel, reflecting diverse consumer needs.
Parent Segment
Children
Product Type
Skin Care (Moisturizers, Cleansers, Serums, Sunscreens, Sheet Masks), Color Cosmetics (Lip, Face, Eye), Hair Care, Fragrance
Price Tier
Mass, Mid-Range, Premium, Luxury
Gender
Women, Men, Unisex
Age Group
Gen Z, Millennials, Generation X, Baby Boomers
Distribution Channel
Online/E-commerce, Social Commerce, Specialty Stores, Supermarkets, Pharmacies
Skin care dominates at ~45–55% share, driven by multi-step routines and ingredient-focused positioning. Social commerce is the fastest-growing channel, leveraging live-streaming and influencer discovery.
Which region leads in C Beauty Products Market?
Asia Pacific leads the C Beauty Products Market with approximately 64% revenue share, driven by China's massive domestic consumption base and advanced digital retail infrastructure.
C Beauty Products Market Regional Market Share
Loading chart...
C Beauty Products Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.64%
North America
0.14%
Europe
0.13%
Middle East & Africa
0.05%
South America
0.04%
Parent Region
Countries
Asia Pacific
China, Japan, South Korea, India, Southeast Asia
North America
USA, Canada, Mexico
Europe
Germany, UK, France, Italy, Spain
Latin America
Brazil, Mexico, Argentina, Chile
Middle East & Africa
Saudi Arabia, UAE, South Africa, Nigeria
China is the single largest country market, accounting for over half of global C-beauty revenue. Latin America is the fastest-growing region through 2033, propelled by TikTok Shop expansion and Gen Z adoption. Europe presents premiumization opportunities but faces regulatory friction around TCM botanicals.
What is driving growth — and what is holding it back?
Growth is powered by cultural authenticity, digital commerce leadership, and functional ingredient innovation; restraints include regulatory complexity and brand trust deficits in Western markets.
Factor
Direction
Evidence Strength
Mechanism
Guochao cultural movement
Driver
High
74% of Chinese post-millennials prefer domestic brands when quality is comparable
TCM ingredient differentiation
Driver
High
Ginseng, goji, snow mushroom resonate with clean-beauty consumers
Social commerce infrastructure
Driver
High
Douyin, TikTok Shop enable viral discovery and rapid conversion
AI-driven personalization
Driver
Medium
Skin diagnostics and virtual try-on enhance engagement
Regulatory patchwork (EU, US MoCRA)
Restraint
High
12–18 month compliance timelines for new formulations
Brand trust deficits / counterfeiting
Restraint
Medium
Historical quality perceptions and IP erosion in emerging channels
Our analysis suggests the balance of drivers outweighs restraints through 2027, but regulatory friction will become the binding constraint on Western expansion post-2027 unless brands invest in local formulation and compliance infrastructure.
Who are the leading vendors?
The competitive landscape features agile Chinese brands leveraging digital-first strategies, TCM portfolios, and rapid product cycles.
Company
Category Focus
Key Strength
Geographic Presence
Perfect Diary
Color Cosmetics
Social commerce, KOL marketing
China, Southeast Asia
Florasis
Premium Color + Skin
TCM storytelling, Sephora placement
China, Global (210 Sephora doors)
Proya Cosmetics
Skin Care
Mass-premium serums, ingredient focus
China
Pechoin
Skin Care
Herbal whitening, mid-tier pricing
China, Eastern Europe, SEA
Chando
Skin Care
Glacier cream routines
China, South Korea, Central Asia
Judydoll
Color Cosmetics
Offline counters, affordability
China, Malaysia, Russia, Chile
Herborist
Skin Care
TCM apothecary branding
China, France, Saudi Arabia
Biohyalux
Skin Care
HA-based serums, pharmacy channels
China, Australia, Middle East
Competitive moats are built on speed-to-market, cultural authenticity, and digital-native marketing competencies. Florasis and Perfect Diary have achieved international visibility, while Pechoin and Chando leverage offline expansion in emerging markets.
What do buyers and operators need to know?
Buyers and operators must prioritize ingredient transparency, regulatory compliance, and channel strategy when selecting C-beauty products. In Western markets, EU Cosmetics Regulation (EC) No 1223/2009 and US MoCRA compliance are non-negotiable, requiring 12–18 months for formulation-intensive brands. Switching costs are moderate—brand loyalty is driven by efficacy and cultural storytelling rather than contractual lock-in. Procurement risks include counterfeiting in emerging channels and supply-chain volatility for TCM botanicals. Operators should validate suppliers' clinical substantiation and traceability documentation before scaling.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors accelerated international expansion for C-beauty brands with authentic TCM portfolios and digital-first capabilities, particularly into Southeast Asia and Latin America where regulatory friction is lower and social commerce penetration is rising. The strongest counter-argument is that brand trust deficits and counterfeiting could cap premiumization in Western markets, limiting upside for mass-tier brands.
Actionable Strategy:
Investors should prioritize brands with established regulatory infrastructure in EU/US and clinically substantiated TCM actives—Florasis and Proya are best positioned for premiumization.
Operators should build TikTok Shop and Douyin capabilities as core go-to-market channels, not supplementary ones, to capture Gen Z discovery cycles.
Buyers should demand ingredient traceability and safety documentation from suppliers to mitigate compliance and reputational risk.
Evidence that would change our conclusion: a significant escalation in EU restrictions on TCM botanicals or a sustained decline in Chinese domestic consumption would force a re-rating of growth expectations downward.
C Beauty Products Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
C Beauty Products Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.7% from 2020-2034
Segmentation
By Product Type
Skin Care
Color Cosmetics
Hair Care
Fragrance
Others
By Price Tier
Mass
Mid-Range
Premium
Luxury
By Gender
Women
Men
Unisex
By Age Group
Gen Z
Millennials
Generation X
Baby Boomers
By Distribution Channel
Online/E-commerce
Social Commerce
Specialty Stores
Supermarkets
Pharmacies
Beauty Salons
By Geography
Asia Pacific
China
Japan
South Korea
India
Southeast Asia
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Latin America
Brazil
Mexico
Argentina
Chile
Middle East & Africa
Saudi Arabia
UAE
South Africa
Nigeria
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Skin Care
5.1.2. Color Cosmetics
5.1.3. Hair Care
5.1.4. Fragrance
5.1.5. Others
5.2. Market Analysis, Insights and Forecast - by Price Tier
5.2.1. Mass
5.2.2. Mid-Range
5.2.3. Premium
5.2.4. Luxury
5.3. Market Analysis, Insights and Forecast - by Gender
5.3.1. Women
5.3.2. Men
5.3.3. Unisex
5.4. Market Analysis, Insights and Forecast - by Age Group
5.4.1. Gen Z
5.4.2. Millennials
5.4.3. Generation X
5.4.4. Baby Boomers
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Online/E-commerce
5.5.2. Social Commerce
5.5.3. Specialty Stores
5.5.4. Supermarkets
5.5.5. Pharmacies
5.5.6. Beauty Salons
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Skin Care
6.1.2. Color Cosmetics
6.1.3. Hair Care
6.1.4. Fragrance
6.1.5. Others
6.2. Market Analysis, Insights and Forecast - by Price Tier
6.2.1. Mass
6.2.2. Mid-Range
6.2.3. Premium
6.2.4. Luxury
6.3. Market Analysis, Insights and Forecast - by Gender
6.3.1. Women
6.3.2. Men
6.3.3. Unisex
6.4. Market Analysis, Insights and Forecast - by Age Group
6.4.1. Gen Z
6.4.2. Millennials
6.4.3. Generation X
6.4.4. Baby Boomers
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Online/E-commerce
6.5.2. Social Commerce
6.5.3. Specialty Stores
6.5.4. Supermarkets
6.5.5. Pharmacies
6.5.6. Beauty Salons
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Skin Care
7.1.2. Color Cosmetics
7.1.3. Hair Care
7.1.4. Fragrance
7.1.5. Others
7.2. Market Analysis, Insights and Forecast - by Price Tier
7.2.1. Mass
7.2.2. Mid-Range
7.2.3. Premium
7.2.4. Luxury
7.3. Market Analysis, Insights and Forecast - by Gender
7.3.1. Women
7.3.2. Men
7.3.3. Unisex
7.4. Market Analysis, Insights and Forecast - by Age Group
7.4.1. Gen Z
7.4.2. Millennials
7.4.3. Generation X
7.4.4. Baby Boomers
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Online/E-commerce
7.5.2. Social Commerce
7.5.3. Specialty Stores
7.5.4. Supermarkets
7.5.5. Pharmacies
7.5.6. Beauty Salons
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Skin Care
8.1.2. Color Cosmetics
8.1.3. Hair Care
8.1.4. Fragrance
8.1.5. Others
8.2. Market Analysis, Insights and Forecast - by Price Tier
8.2.1. Mass
8.2.2. Mid-Range
8.2.3. Premium
8.2.4. Luxury
8.3. Market Analysis, Insights and Forecast - by Gender
8.3.1. Women
8.3.2. Men
8.3.3. Unisex
8.4. Market Analysis, Insights and Forecast - by Age Group
8.4.1. Gen Z
8.4.2. Millennials
8.4.3. Generation X
8.4.4. Baby Boomers
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Online/E-commerce
8.5.2. Social Commerce
8.5.3. Specialty Stores
8.5.4. Supermarkets
8.5.5. Pharmacies
8.5.6. Beauty Salons
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Skin Care
9.1.2. Color Cosmetics
9.1.3. Hair Care
9.1.4. Fragrance
9.1.5. Others
9.2. Market Analysis, Insights and Forecast - by Price Tier
9.2.1. Mass
9.2.2. Mid-Range
9.2.3. Premium
9.2.4. Luxury
9.3. Market Analysis, Insights and Forecast - by Gender
9.3.1. Women
9.3.2. Men
9.3.3. Unisex
9.4. Market Analysis, Insights and Forecast - by Age Group
9.4.1. Gen Z
9.4.2. Millennials
9.4.3. Generation X
9.4.4. Baby Boomers
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Online/E-commerce
9.5.2. Social Commerce
9.5.3. Specialty Stores
9.5.4. Supermarkets
9.5.5. Pharmacies
9.5.6. Beauty Salons
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Skin Care
10.1.2. Color Cosmetics
10.1.3. Hair Care
10.1.4. Fragrance
10.1.5. Others
10.2. Market Analysis, Insights and Forecast - by Price Tier
10.2.1. Mass
10.2.2. Mid-Range
10.2.3. Premium
10.2.4. Luxury
10.3. Market Analysis, Insights and Forecast - by Gender
10.3.1. Women
10.3.2. Men
10.3.3. Unisex
10.4. Market Analysis, Insights and Forecast - by Age Group
10.4.1. Gen Z
10.4.2. Millennials
10.4.3. Generation X
10.4.4. Baby Boomers
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Online/E-commerce
10.5.2. Social Commerce
10.5.3. Specialty Stores
10.5.4. Supermarkets
10.5.5. Pharmacies
10.5.6. Beauty Salons
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: C Beauty Products Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific C Beauty Products Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: Asia Pacific C Beauty Products Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: Asia Pacific C Beauty Products Market Revenue (Billion), by Price Tier 2026 & 2034
Figure 5: Asia Pacific C Beauty Products Market Revenue Share (%), by Price Tier 2026 & 2034
Figure 6: Asia Pacific C Beauty Products Market Revenue (Billion), by Gender 2026 & 2034
Figure 7: Asia Pacific C Beauty Products Market Revenue Share (%), by Gender 2026 & 2034
Figure 8: Asia Pacific C Beauty Products Market Revenue (Billion), by Age Group 2026 & 2034
Figure 9: Asia Pacific C Beauty Products Market Revenue Share (%), by Age Group 2026 & 2034
Figure 10: Asia Pacific C Beauty Products Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: Asia Pacific C Beauty Products Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: Asia Pacific C Beauty Products Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Asia Pacific C Beauty Products Market Revenue Share (%), by Country 2026 & 2034
Figure 14: North America C Beauty Products Market Revenue (Billion), by Product Type 2026 & 2034
Figure 15: North America C Beauty Products Market Revenue Share (%), by Product Type 2026 & 2034
Figure 16: North America C Beauty Products Market Revenue (Billion), by Price Tier 2026 & 2034
List of Tables
Table 1: C Beauty Products Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: C Beauty Products Market Revenue Billion Forecast, by Price Tier 2020 & 2034
Table 3: C Beauty Products Market Revenue Billion Forecast, by Gender 2020 & 2034
Table 4: C Beauty Products Market Revenue Billion Forecast, by Age Group 2020 & 2034
Table 5: C Beauty Products Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: C Beauty Products Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: Asia Pacific C Beauty Products Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 8: Asia Pacific C Beauty Products Market Revenue Billion Forecast, by Price Tier 2020 & 2034
Table 9: Asia Pacific C Beauty Products Market Revenue Billion Forecast, by Gender 2020 & 2034
Table 10: Asia Pacific C Beauty Products Market Revenue Billion Forecast, by Age Group 2020 & 2034
Table 11: Asia Pacific C Beauty Products Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: Asia Pacific C Beauty Products Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: China C Beauty Products Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Japan C Beauty Products Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: South Korea C Beauty Products Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: India C Beauty Products Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the C Beauty Products Market size in 2025?
The global C Beauty Products Market was valued at approximately USD 20.5 billion in 2025, with Asia Pacific accounting for roughly 64% of revenue. Growth is driven by TCM ingredient innovation and social commerce expansion.
2. What is the forecast CAGR for C Beauty Products Market?
The market is projected to grow at a CAGR of 10.7% from 2026 to 2033, reaching approximately USD 46.3 billion by 2033. This reflects rising global acceptance of Chinese beauty brands and cross-border e-commerce expansion.
3. Which region dominates the C Beauty Products Market?
Asia Pacific dominates with approximately 64% share, led by China's massive domestic market of RMB 423 billion. Latin America is the fastest-growing region, driven by TikTok Shop expansion and Gen Z adoption.
4. Who are the leading companies in C Beauty Products Market?
Leading vendors include Perfect Diary, Florasis, Proya Cosmetics, Pechoin, Chando, Judydoll, Herborist, and Biohyalux. Differentiation is built on TCM ingredient portfolios, speed-to-market, and digital-native marketing.
5. What are the key challenges facing C Beauty Products Market?
Regulatory complexity in EU and US markets, brand trust deficits in Western markets, and counterfeiting in emerging channels are key restraints. Compliance timelines of 12–18 months for new formulations pose significant barriers.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary split, ensuring data integrity through direct industry engagement. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers (TCM botanical extractors), specialized formulators, contract manufacturers, brand owners, and global distributors. Interviews were conducted with decision-makers including VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. This fieldwork captured granular insights into formulation trends, pricing dynamics, and channel strategies.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
35%
Procurement & Sourcing Directors
30%
Commercial & Operations Leads
20%
Regulatory Affairs Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Botanical Extract Suppliers
30%
Contract Formulators & Manufacturers
40%
Brand Owners & Distributors
30%
Secondary Benchmarking & Public Trade Validation
We triangulated primary findings with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized industry associations. Cross-border trade flows for HS Chapter 33 (essential oils, cosmetics) were analyzed to validate regional demand patterns and export trajectories.
Demand Modeling & Market Sizing Triangulation
Our approach combines top-down macroeconomic allocation (GDP, consumer spending, beauty category share) with bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. This dual methodology ensures robust market sizing and forecast accuracy.
 C Beauty Products Market