 Uae Organic Personal Care Market
UAE Organic Personal Care Market Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 181

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Uae Organic Personal Care Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 112.0 M |
| 2026 | 120.0 M |
| 2027 | 129.0 M |
| 2028 | 138.0 M |
| 2029 | 148.0 M |
| 2030 | 159.0 M |
| 2031 | 171.0 M |

The UAE organic personal care market encompasses skincare, hair care, oral care, and cosmetic products formulated with certified organic or natural ingredients, sold through offline and online channels across the seven emirates. It serves consumers seeking chemical-free, sustainable alternatives to conventional beauty products, driven by ingredient transparency and wellness lifestyles.
This analysis covers organic and natural personal care products across five product categories—skin care, hair care, oral care, cosmetics, and others—distributed through offline (specialty stores, pharmacies, supermarkets) and online channels across Dubai, Abu Dhabi, Sharjah, Ras Al Khaimah, and Fujairah. Revenue figures represent B2C retail sales.
This analysis does not cover conventional personal care products, professional salon services, beauty tech devices, or fragrances as a standalone category. It also excludes industrial or bulk ingredient supply to manufacturers, which constitutes a separate upstream market.
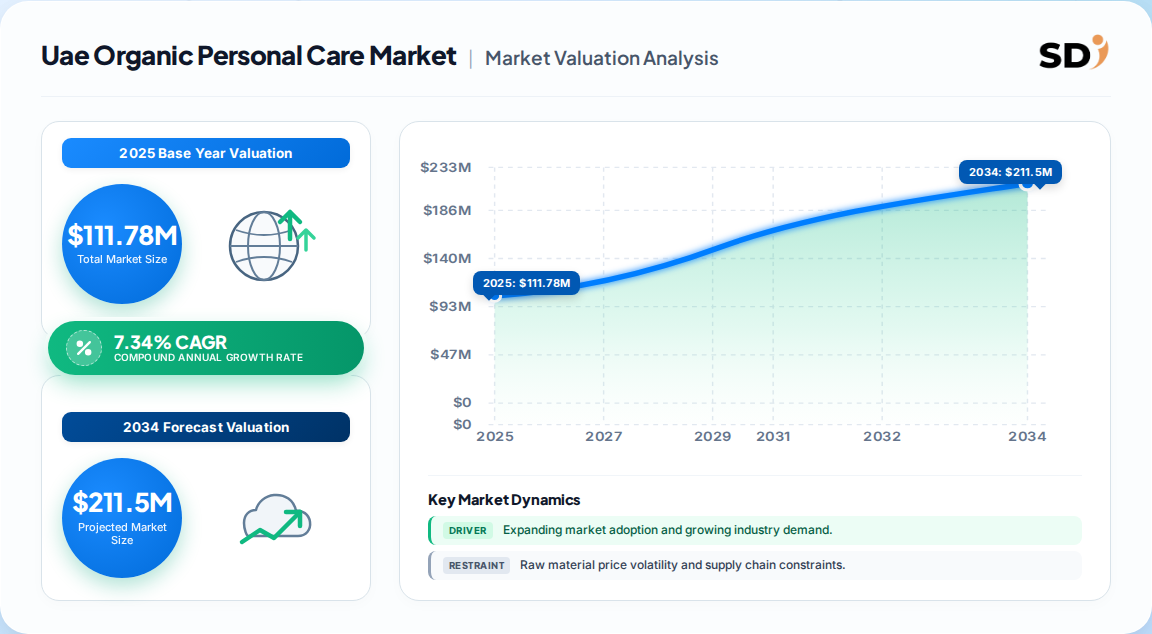
One published estimate values the UAE organic personal care market at USD 111.78 Million in 2025, with a 7.34% CAGR projecting USD 211.46 Million by 2034. This national figure represents roughly 4% of the broader USD 2.69 Billion UAE beauty and personal care market in 2025—a penetration rate that signals substantial headroom as organic adoption deepens.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 111.78 Million | 2025 | 2034 | 7.34% | Organic personal care, offline + online, five product categories | One UAE-focused industry analysis |
| USD 2,694.7 Million (total beauty & personal care) | 2025 | 2034 | 5.25% | Conventional + organic, all product types including fragrances | A separate IMARC Group estimate |
| Global organic personal care at USD 158.03 Billion (2026) | 2026 | 2031 | 6.24% | Global organic personal care, broad product scope | A global market intelligence estimate |
Our analysis suggests the USD 111.78 Million figure is the most defensible baseline for UAE-specific organic personal care. It aligns with the ~4% organic share implied by comparing the organic figure to the broader UAE beauty market. The global estimate (USD 158 Billion) uses a significantly broader product scope including oral care and deodorants, making direct comparison unreliable without normalization.
Segmentation follows product category and distribution channel. Skin care accounts for approximately 41% of revenue, hair care 26%, cosmetics 18%, oral care 9%, and others 6%. Offline channels dominate at 63%, with online at 37% and growing faster as e-commerce penetration deepens.
| Parent Segment | Children | Revenue Share |
|---|---|---|
| By Product | Skin Care, Hair Care, Oral Care, Cosmetic, Others | Skin Care 41%, Hair Care 26%, Cosmetic 18%, Oral Care 9%, Others 6% |
| By Distribution Channel | Offline, Online | Offline 63%, Online 37% |
So what? The concentration in skin care (41%) and offline retail (63%) creates a defensible moat for incumbents with established retail relationships. New entrants must either disrupt through digital-first skin care or secure scarce shelf space in premium retail—both capital-intensive paths.
Dubai leads the UAE organic personal care market with approximately 44% of total demand, driven by luxury retail infrastructure, international brand presence, and high expatriate purchasing power. Abu Dhabi follows at 27%, Sharjah at 15%, Ras Al Khaimah at 8%, and Fujairah at 6%.
| Region | Market Share (%) |
|---|---|
| Dubai | 0.44% |
| Abu Dhabi | 0.27% |
| Sharjah | 0.15% |
| Ras Al Khaimah | 0.08% |
| Fujairah | 0.06% |
| Emirate | Share |
|---|---|
| Dubai | 44% |
| Abu Dhabi | 27% |
| Sharjah | 15% |
| Ras Al Khaimah | 8% |
| Fujairah | 6% |
Our analysis suggests the Dubai-Abu Dhabi duopoly (71% combined) means distribution strategies must anchor in these two emirates before expanding to the northern emirates. Brands entering Sharjah or Ras Al Khaimah first will likely face higher per-unit customer acquisition costs.
Growth is powered by rising consumer awareness of chemical-free ingredients, premium organic product launches by multinationals, and social-media-driven beauty trends. Constraints include high certification costs, premium ingredient sourcing challenges, and price sensitivity in mass-market segments.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Growing demand for natural beauty products | Driver | High | >45% of UAE beauty consumers prefer organic/natural/cruelty-free labels (2025) |
| Social media influence on purchasing | Driver | High | TikTok/Instagram beauty content accelerates product discovery and adoption |
| Rising disposable income and expatriate spending | Driver | High | High beauty spending among urban and expatriate consumers |
| Sustainable packaging and clean beauty innovation | Driver | Medium | Brands introducing recyclable packaging; consumer interest in vegan/cruelty-free |
| High product costs and certification standards | Restraint | High | Premium ingredients and international certification inflate production costs |
| Limited organic raw material availability | Restraint | Medium | Supply chain constraints for certain certified organic inputs |
| Price sensitivity in mass segments | Restraint | Medium | Premium pricing restricts adoption among budget-conscious consumers |
The balance of evidence favors the drivers. The 45% consumer preference for organic labels creates a structural demand floor, while certification costs—though significant—are a barrier that incumbent multinationals can absorb more easily than new entrants. This creates a competitive moat for established players.
The UAE organic personal care market is moderately concentrated. The top five companies—Unilever Gulf FZE, P&G Gulf FZE, L'Oréal Middle East, Estée Lauder Middle East, and Kao UAE—collectively hold approximately 59% of the market. These multinationals leverage global supply chains, established retail relationships, and brand trust to maintain dominance.
| Company | Positioning | Key Strength |
|---|---|---|
| Unilever Gulf FZE | Broad organic portfolio across skin and hair care | Global supply chain; retail shelf space; sustainability commitments |
| Procter & Gamble Gulf FZE | Mass and premium organic offerings | Brand equity; distribution scale; R&D capabilities |
| L'Oréal Middle East | Premium eco-certified cosmetics | Luxury brand portfolio; retail partnerships; marketing spend |
| Estée Lauder Middle East | Clean beauty and plant-based skincare | Prestige positioning; department store presence |
| Kao UAE | Specialized skin and hair care | Ingredient innovation; Asian beauty expertise |
Our analysis suggests the 59% concentration among top five players creates a barrier for independent organic brands, but also an opportunity: niche brands with strong certification credentials and digital-native marketing can capture share in underpenetrated segments like oral care (9% share) and men's grooming.
Mission-critical selection criteria include certification authenticity (COSMOS, USDA Organic, or equivalent), ingredient traceability, and supply chain reliability. Buyers should prioritize vendors with transparent certification documentation and verified sourcing audits. The cost of switching suppliers mid-cycle is high due to certification validation timelines and reformulation risks.
Procurement risks include limited availability of certified organic raw materials, which can create supply gaps and price volatility. Operators should secure dual-source agreements for key inputs and build buffer inventory for high-demand ingredients. Regulatory compliance with UAE.S.MoIAT and ESMA labeling standards is mandatory; non-compliant products face import delays or rejection.
Key decision criteria for buyers:
The balance of evidence favors a bullish outlook for the UAE organic personal care market. The 7.34% CAGR through 2034 is supported by structural drivers: high disposable income, 45% consumer preference for organic labels, and a government-led wellness agenda. The most credible counter-argument is that premium pricing limits mass-market adoption, capping growth at the current ~4% organic penetration of total beauty spending. However, our analysis suggests certification costs will decline as regional supply chains mature, gradually expanding the addressable market.
Actionable Strategy for Operators and Investors:
What evidence would change our conclusion: A sustained decline in expatriate disposable income, stricter UAE import regulations on organic certification, or a significant price war among top five players that compresses margins below sustainable levels. Absent these, the market trajectory remains robust through 2034.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.34% from 2020-2034 |
| Segmentation |
|
The market was valued at USD 111.78 Million in 2025 and is projected to reach USD 211.46 Million by 2034, growing at a 7.34% CAGR. Skin care is the largest product segment at 41% of revenue.
Dubai leads with approximately 44% of total market demand, driven by luxury retail infrastructure and high expatriate purchasing power. Abu Dhabi follows at 27%, with Sharjah at 15%.
Key drivers include rising consumer awareness of chemical-free ingredients, premium product launches by multinationals, social media beauty trends, and high disposable income among urban and expatriate consumers.
Unilever Gulf FZE, Procter & Gamble Gulf FZE, L'Oréal Middle East, Estée Lauder Middle East, and Kao UAE are the leading players, collectively holding approximately 59% of the market.
High product costs from premium ingredients and certification compliance, limited availability of certified organic raw materials, and price sensitivity in mass-market segments are the primary restraints on growth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary data split, ensuring that market sizing and forecasts are grounded in verified industry intelligence. In-depth interviews were conducted with stakeholders across the value chain, including organic raw material suppliers, specialized formulators, contract manufacturers, and regional distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, providing granular insights into procurement patterns, formulation trends, and channel dynamics specific to the UAE organic personal care sector.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 40% |
| R&D & Formulation Leads | 35% |
| Regulatory & Quality Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Organic Ingredient Suppliers | 40% |
| Contract Manufacturers & Formulators | 35% |
| Regional Distributors & Retailers | 25% |
Secondary research draws on official multilateral trade databases including UN Comtrade, WTO tariff schedules, and UAE Federal Competitiveness and Statistics Centre (FCSC) import-export records. Corporate annual filings, investor presentations, and UAE Ministry of Economy registration data were analyzed to map competitive positioning. Patent databases and technical standards from ISO and ESMA were reviewed to validate certification and labeling compliance frameworks governing organic personal care products in the UAE.
We employ simultaneous Top-Down and Bottom-Up modeling. The Top-Down approach allocates macroeconomic beauty and personal care spending to the organic segment using penetration rates derived from consumer surveys and retail scan data. The Bottom-Up approach models manufacturer production volumes, pricing tiers, and end-use consumption across emirates, cross-validated against import statistics and distributor shipment data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2034 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Emirate-level share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |