 Professional Beauty Services Market
 Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 240

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Professional Beauty Services Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 239.4 B |
| 2026 | 254.9 B |
| 2027 | 271.2 B |
| 2028 | 288.5 B |
| 2029 | 307.0 B |
| 2030 | 326.6 B |

The Professional Beauty Services Market covers licensed, professional-delivered treatments—hair care, skin and facial care, nail care, massage and spa, and makeup—performed in salons, spas, barbershops, and franchise or enterprise chains, sold to consumers through offline and increasingly online booking channels.
This analysis covers professional service delivery—not the retail sale of beauty products, which is tracked separately as an adjacent category. It includes salon, spa, barbershop, and franchise-chain service revenue across women, men, and children end-users, booked offline or through digital platforms.
This analysis does not cover at-home device markets, cosmetic surgery, injectables, pharmaceutical dermatology, or professional beauty product manufacturing. Those adjacent segments have distinct regulatory pathways, margin structures, and buyer personas, and conflating them is a primary driver of the wide forecast divergence documented below.
One published estimate values the market at 299.6 Billion in 2026, growing to 495.5 Billion by 2033 at 7.5% CAGR—but competing houses report a 2026 base as low as 178.93 Billion and a 2031 horizon of 230.56 Billion at 5.2% CAGR. The spread is definitional, not just methodological.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 299.6 Billion | 2026 | 2033 (495.5 Billion) | 7.5% | Broad service scope incl. spa and advanced treatments | One published estimate |
| 178.93 Billion | 2026 | 2031 (230.56 Billion) | 5.20% | Salon-core service scope, narrower treatment taxonomy | A competing analysis |
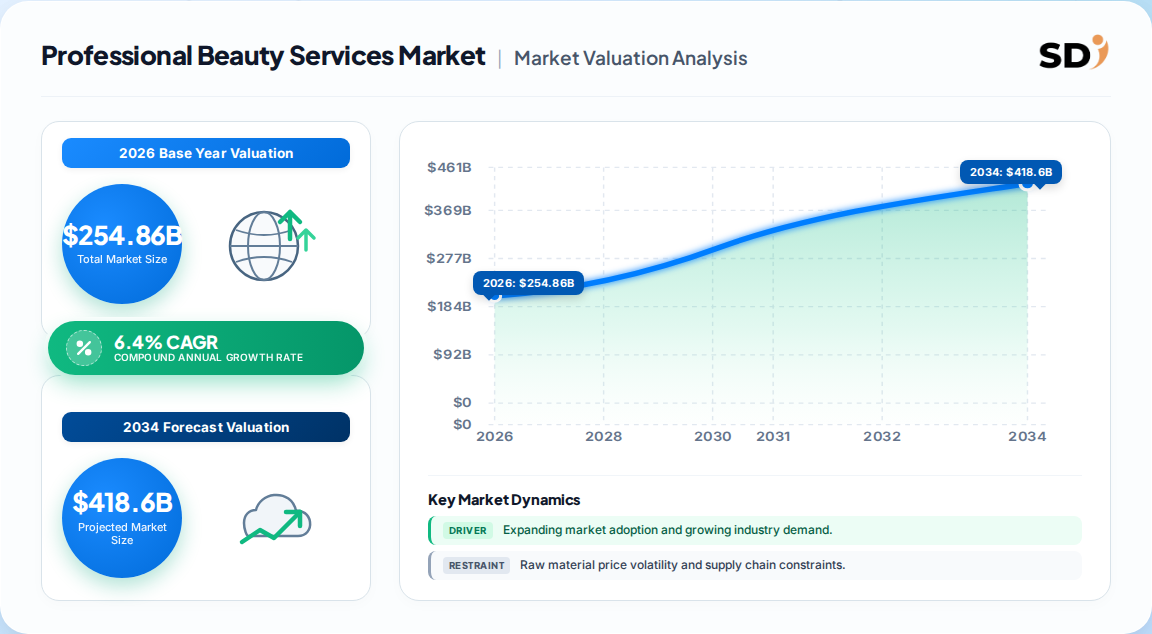
| 254.86 Billion | 2026 | 2030 (334.41 Billion) | 6.4% | Mid-scope, wellness-integrated services emphasized | A third trade benchmark |
Our analysis suggests the mid-scope 6.4% trajectory is the most defensible planning base. The high-end 7.5% estimate implicitly assumes aggressive premiumization and spa-inclusive scope; the low-end 5.2% estimate under-weights the male-grooming and online-booking expansion now visible in transaction data. Buyers should anchor capital models to the mid-scope band and treat the low-end figure as a downside case.
Segmentation follows four non-geographic axes: service type, end-user, booking channel, and business structure. The critical insight is that the fastest-growing children are not the largest today—skin care and male grooming are compounding faster than hair care and women's services.
| Parent segment | Children | 2025 share / growth signal |
|---|---|---|
| By Service Type | Hair Care; Skin Care & Facial; Nail Care; Massage & Spa; Makeup | Hair care 34.4% (one estimate: 58.7% on broad scope); skin care CAGR 6.34% |
| By End User | Women; Men; Children | Women 68.7%–78.2%; men's CAGR 6.86% |
| By Booking Channel | Offline; Online Booking Platforms | Offline 71.8%; online CAGR 7.46% |
| By Business Structure | Independent Salons; Franchise & Enterprise Chains | Independent 62.7%; franchise CAGR 6.23% |
The booking-channel and business-structure splits carry the most strategic weight for operators. Online booking at a 7.46% CAGR is roughly double the pace of offline, and franchise chains at 6.23% are outpacing the overall market in organization—both point to a structural shift in how demand is captured rather than simply how much demand exists.
Asia-Pacific leads both on size and velocity, accounting for roughly 36%–39% of global revenue in 2025 and posting the fastest regional CAGR at approximately 6.12%. North America and Europe remain high-value but slower-growth theaters, with North America holding the largest single-country share via the U.S.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.38% |
| North America | 0.27% |
| Europe | 0.23% |
| South America | 0.06% |
| Middle East & Africa | 0.06% |
The regional hierarchy is not stable. Asia-Pacific's lead is built on rising urban incomes and organized-salon penetration, while North America's position reflects premium pricing and legacy density. Our analysis suggests Asia-Pacific will widen the gap through the forecast window because its addressable base is expanding, whereas North America's growth is mix-driven and therefore more sensitive to employment and wage cycles in the salon workforce.
Growth is driven by rising disposable income and premium grooming spend, social-media trend acceleration, organized chain expansion, male-grooming normalization, and digital booking integration. Restraints are high service cost, skilled-professional shortages, and safety concerns over hazardous chemicals—particularly in North America and the EU.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising disposable income / premium grooming spend | Driver (+1.5% CAGR) | High | Higher visit frequency and richer service mix |
| Social media and trend discovery | Driver (+0.8% CAGR) | High | Compresses trend-to-booking lag; shortens service refresh cycles |
| Organized chains and franchise models | Driver (+0.7% CAGR) | Medium-High | Standardization, training, common technology platforms |
| Male grooming normalization | Driver (+0.6% CAGR) | Medium | New revenue pocket; menu and layout redesign |
| Digital technology integration | Driver (+0.5% CAGR) | Medium | Booking efficiency, retention, client data |
| Beauty-wellness convergence | Driver (+0.7% CAGR) | Medium | Higher-ticket holistic treatment bundles |
| High service costs and wage inflation | Restraint (−0.4% CAGR) | High | Margin compression, price sensitivity at entry tiers |
| Skilled-professional shortage and training costs | Restraint (−0.3% CAGR) | High | Capacity ceilings, inconsistent service quality |
| Chemical safety concerns | Restraint (−0.3% CAGR) | Medium | Regulatory scrutiny and reformulation cost |
The balance of evidence favors drivers, but the margin structure is shifting. Our analysis suggests the restraint side is under-priced in most forecasts: labor scarcity and training cost are structural, not cyclical, and they cap how fast organized chains can convert demand into revenue. Operators that solve the talent pipeline—through academy models or in-house certification—will capture disproportionate share.
The vendor landscape is fragmented with low concentration. Leading names are Regis Corporation, Great Clips, Sport Clips, Ulta Beauty, and WellBiz Brands—but no single player holds a dominant share, and independent salons still command roughly 63% of revenue.
| Company | Primary positioning | Structural moat |
|---|---|---|
| Regis Corporation | Large multi-brand salon portfolio | Scale, brand breadth, real-estate network |
| Great Clips | Franchise value-hair model | Franchise standardization, high-throughput operations |
| Sport Clips | Male-focused franchise chain | Niche brand equity in male grooming |
| Ulta Beauty | Retail-plus-salon hybrid | Cross-sell between services and product retail |
| WellBiz Brands | Multi-brand franchise platform | Portfolio diversification, franchisee support systems |
The competitive moat in this sector is not product—it is operational consistency and talent throughput. Franchise systems win because they codify training and service standards, but they trade flexibility for scale. Our analysis suggests platform-led operators with booking data will erode some of the franchise advantage in urban markets, because demand generation is migrating to digital discovery faster than franchise menus can refresh.
Selection and procurement criteria differ sharply between service buyers (consumers, corporate wellness programs) and institutional buyers (franchisors, investors). For institutional buyers, the mission-critical criteria are unit-level economics, workforce retention rates, and technology stack portability—not brand recall.
Key risks include wage inflation pass-through, regulatory variation on chemical treatments across the EU and North America, and switching costs tied to booking-platform lock-in. Franchise agreements often constrain menu experimentation, which is a hidden cost in a market where trend cycles are compressing.
Regulatory compliance is a live procurement gate in the EU and North America, where chemical safety scrutiny is rising. Buyers should require documented training credentials, patch-test protocols, and ingredient transparency before signing multi-year service or supply contracts. In emerging markets, licensing enforcement is uneven—verify rather than assume.
The balance of evidence favors a mid-single-digit growth reality, not the headline 7.5% figure. We anchor at 6.4%, which reconciles the broad-scope optimism with the salon-core caution. The strongest counter-argument is that spa and wellness convergence could legitimately expand the definitional boundary, pulling actual growth toward the higher estimate—but that requires category migration that most operators have not yet operationalized.
Our judgment is that the market's center of gravity is shifting from footfall to frequency, and from independents to organized systems. The companies winning share are those that convert social discovery into repeat bookings and solve labor throughput. Investors should treat regional share stability as a lagging indicator; booking-channel mix is the leading one.
What would change our conclusion: a sustained acceleration in online-booking share above 35% of transactions, or evidence that organized chains cross 45% of revenue, would justify migrating to the higher growth band. Until then, we hold at 6.4%.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
Published estimates for 2026 range from 178.93 Billion to 299.6 Billion, depending on scope. Our triangulated planning base sits near the mid-scope 254.86 Billion figure, with a 6.4% working CAGR through the forecast horizon.
Online booking platforms are growing at roughly 7.46% CAGR, outpacing offline, while skin care and facial services lead service-type growth at about 6.34%. Male grooming is the fastest-compounding end-user pocket at 6.86%.
Asia-Pacific leads on both size and growth, holding roughly 36%–39% of global revenue and posting the fastest regional CAGR. North America follows, anchored by the U.S. as the largest single-country market.
Regis Corporation, Great Clips, Sport Clips, Ulta Beauty, and WellBiz Brands lead the fragmented vendor field. Independent salons still hold about 63% of revenue, so concentration remains low despite franchise expansion.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain with salon and spa operators, franchise system headquarters, beauty technology and booking-platform providers, professional product suppliers, and training-academy institutions. Decision-maker designations interviewed include VP of Franchise Operations, Head of Service Innovation, Technical Director of Training, and Commercial Operations Leads. Structured interview guides captured unit economics, workforce retention, service menu refresh cycles, and digital adoption patterns, ensuring demand-side and supply-side signals are validated against operator reality rather than survey abstraction.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Franchise & Commercial Operations Leads | 40% |
| Service Innovation & Training Directors | 30% |
| Procurement & Supply Chain Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| Salon & Spa Operators | 35% |
| Franchise & Enterprise Chains | 25% |
| Booking & Beauty Technology Platforms | 22% |
| Professional Product & Training Suppliers | 18% |
We triangulate against official multilateral and national datasets, including UN Comtrade for professional beauty product and equipment flows, WTO services trade statistics, US ITC and Eurostat consumer services data, and corporate annual filings (10-K, SEC disclosures, investor presentations). Patent databases and recognized non-profit technical standards and industry associations inform the regulatory and formulation-risk layers. No competitor market-research publications are used as validation sources.
We run simultaneous Top-Down and Bottom-Up models. Top-Down allocates macroeconomic consumer spending and industry segment share; Bottom-Up models operator capacity, average ticket value, visit frequency, and end-use consumption. Divergence between the two is reconciled at the segment level before any forecast is published.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |