 Baby Personal Care Market
 Outlook 2026: Size & Trends
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 201

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Baby Personal Care Market
Vijayashree Ugale
Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 6.530 B |
| 2026 | 6.770 B |
| 2027 | 7.020 B |
| 2028 | 7.280 B |
| 2029 | 7.540 B |
| 2030 | 7.820 B |
| 2031 | 8.110 B |

The baby personal care market covers products formulated for the hygiene, cleansing and skin protection of infants and toddlers, including baby washes, lotions, oils, powders, shampoos, wipes and barrier creams. It is a sub-segment of beauty and personal care, sold through retail and online channels to parents and caregivers.
This report covers baby skin care, toiletries, hair care and related personal care products across all sales channels and geographies. The scope includes organic/natural and synthetic formulations for age groups from 0–6 months to 25 months and above. This analysis does not cover baby food and beverages, diapers, wipes as a standalone category, prams, strollers, car seats or infant safety equipment.
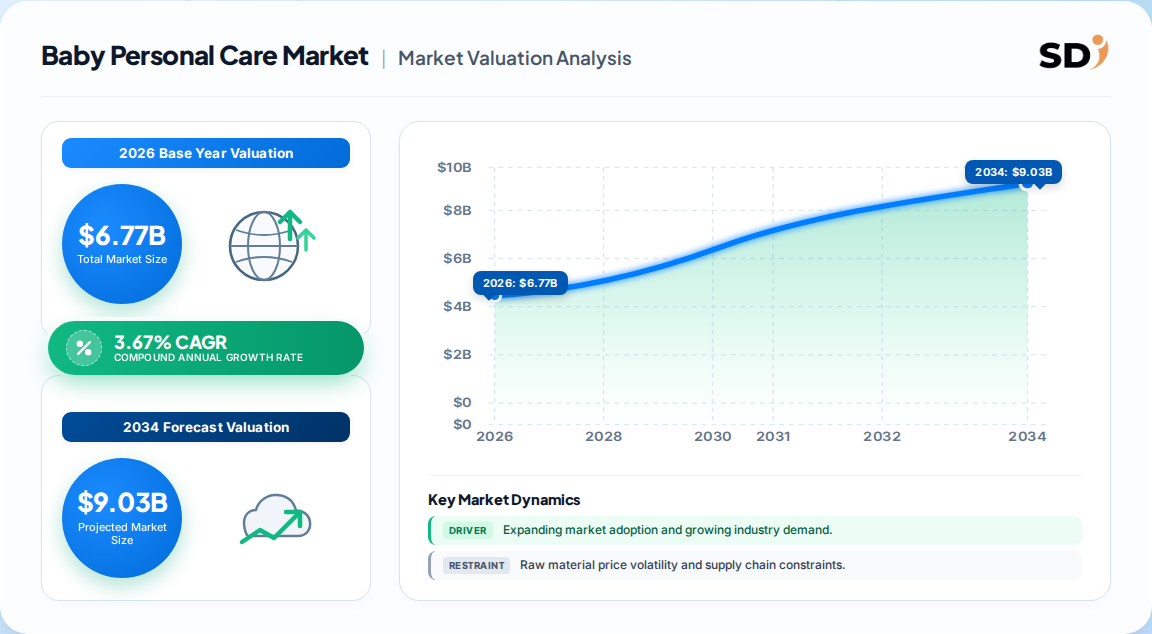
Published estimates converge on a mid-single-digit growth trajectory, with the most defensible global figure at USD 6.77 billion for 2026, rising to USD 9.71 billion by 2036. The table below compares available benchmarks.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 6.77 billion | 2026 | 2036 | 3.67% | Global baby personal care (skin care, toiletries, hair care) | One published estimate |
| USD 5.57 billion (India only) | 2026 | 2032 | 11.42% | India baby care products, including food and diapers | A competing analysis |
| USD 5.2 billion (UK only) | 2026 | 2031 | 4.2% | UK baby care products, including food, diapers, safety | Another published forecast |
The global figure is the most defensible for strategic planning because it isolates personal care from food and durables. Our analysis suggests the 3.67% CAGR is a value-led story: unit volume is flat or declining in mature markets, while premium skin care and ingredient transparency lift average spend per baby.
Segmentation follows four shopper axes—product type, nature, age group and sales channel—plus region. Skin care dominates product value, while supermarkets and hypermarkets remain the largest channel.
| Parent segment | Children | 2026 share / note |
|---|---|---|
| Product type | Skin care, toiletries, hair care, others | Skin care 41.8%; toiletries 27.4%; hair care 19.6%; others 11.2% |
| Nature | Organic/natural, synthetic | Synthetic 61.3%; organic/natural 38.7% |
| Age group | 0–6 months, 6–12 months, 12–24 months, 25 months & above | 0–6 months 31.4% |
| Sales channel | Wholesalers/distributors, specialty stores, supermarkets/hypermarkets, pharmacies/drug stores, online stores, others | Supermarkets/hypermarkets 29.6% |
Asia Pacific leads the global baby personal care market in growth terms, anchored by India (7.1% CAGR) and China (6.7% CAGR), while North America and Europe remain the largest value pools on a per-baby spend basis.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.36% |
| North America | 0.24% |
| Europe | 0.22% |
| Middle East & Africa | 0.08% |
| Latin America | 0.1% |
Our analysis suggests India and China will add both volume and value through 2036, but mature markets will contribute disproportionate revenue per birth. Germany recorded 654,241 births in 2025, the lowest post-war level, while England and Wales recorded 585,396 live births, down 1.6%, confirming the demographic split.
Growth is driven by ingredient transparency, premium skin care and rising spend per baby, while shrinking birth cohorts and price sensitivity constrain unit volume. The balance favors value growth over volume growth across all mature markets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Ingredient transparency and clean-label demand | Driver | High | Parents trade up to fragrance-free, dermatologist-tested products |
| Premiumization of skin care | Driver | High | Eczema and allergy prevalence lifts demand for therapeutic creams |
| Rising spend per baby | Driver | Medium | Older, higher-income parents favor premium brands |
| E-commerce and subscription models | Driver | Medium | Convenience and predictable repeat purchase |
| Falling birth counts | Restraint | High | Germany, UK and USA cohorts shrink, capping unit volume |
| Price sensitivity and private label | Restraint | Medium | Inflation pushes parents toward store brands |
| Complex regulatory approvals | Restraint | Medium | BIS and cosmetic compliance raise barriers to entry |
Our analysis suggests the net effect is a 3.67% CAGR that underperforms the parent beauty and personal care market (8.2%) and diapers (6.2%). Vendors that fail to premiumize will lose shelf space to nappies and adult lines.
Kenvue, Procter & Gamble, Kimberly-Clark, Danone, Unilever and Nestlé lead the global field, with regional champions such as FirstCry in India shaping local price tiers. Differentiation rests on pediatrician trust, formulation credibility and channel reach.
| Company | Portfolio focus | Geographic strength | Strategic note |
|---|---|---|---|
| Kenvue (Johnson's, Aveeno) | Skin care, toiletries | Global | Baby Care named a growth driver in Q2 2026 |
| Procter & Gamble | Toiletries, wipes | Global | Broad retail penetration |
| Kimberly-Clark | Hygiene-adjacent care | North America, Europe | Acquisition of Kenvue expected Q4 2026 |
| Danone | Specialized nutrition and care | Europe, Asia | Premium infant health positioning |
| Unilever | Toiletries, skin care | Asia, Africa | Mass and mid-tier reach |
| FirstCry | Home brands, wipes, powders | India | Pressing basic tiers as unit growth slows |
Our analysis suggests Kenvue's pediatrician-backed equity is the strongest moat in skin care, but the Kimberly-Clark acquisition introduces portfolio overlap risk that could dilute focus on baby personal care.
Buyers should prioritize formulation credibility, regulatory compliance and channel fit over brand legacy. In India, the Medical Textiles (Quality Control) Order, 2024 requires disposable diapers to meet IS 17509:2021 and bear the BIS Standard Mark, and similar certification logic is spreading to baby cosmetics. Switching costs are low for commodity toiletries but high for dermatologist-recommended skin care, where brand trust and clinical evidence lock in repeat purchase.
Procurement risk concentrates in ingredient traceability and counterfeit exposure, particularly in price-sensitive markets. Operators should secure dual sourcing for plant-derived actives and verify BIS or equivalent certification at intake. The gap between mass and premium tiers is widening, so assortment decisions must be made per cohort rather than per country.
The balance of evidence favors a value-over-volume strategy: the global baby personal care market will grow at a modest 3.67% CAGR to 2036, but the revenue pool will shift decisively toward premium skin care in Asia Pacific and dermatologist-backed formulations everywhere. The strongest counter-argument is that falling births could accelerate faster than expected, compressing even premium demand—but current spend-per-baby data from Kenvue and UK premiumization trends suggest otherwise.
Our analysis suggests three actionable priorities. First, vendors should prioritize pediatrician and pharmacy trust-building in India and China, where 7.1% and 6.7% CAGRs offer the only meaningful volume growth. Second, operators should rationalize basic toiletries and reinvest in eczema and barrier-care lines, where price realization is strongest. Third, investors should watch the Kimberly-Clark–Kenvue consolidation for portfolio pruning signals that could open mid-tier shelf space.
Evidence that would change this conclusion: a sustained rebound in European or US birth rates, or a regulatory shift that lowers certification barriers for natural baby cosmetics, which would accelerate organic segment growth beyond the current 38.7% share.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.67% from 2020-2034 |
| Segmentation |
|
The global baby personal care market is estimated at USD 6.77 billion in 2026, based on one published forecast, and is projected to reach USD 9.71 billion by 2036 at a 3.67% CAGR.
Asia Pacific is the fastest-growing region, led by India at a 7.1% CAGR and China at 6.7% CAGR through 2036, driven by large newborn cohorts and rising premium demand.
Skin care is the largest product segment, accounting for an estimated 41.8% of 2026 sales, ahead of toiletries at 27.4% and hair care at 19.6%.
Falling birth counts in Germany, the UK and the USA cap unit volume, limiting growth to a 3.67% CAGR despite rising spend per baby on premium skin care.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the baby personal care value chain, including raw material and ingredient suppliers, specialized formulators, contract manufacturers, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews validated formulation trends, pricing tiers, and channel dynamics across mature and emerging markets.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement Leads | 35% |
| Heads of R&D & Technical Directors | 40% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Ingredient Suppliers | 40% |
| Specialized Formulators & Contract Manufacturers | 35% |
| Global Distributors & Retailers | 25% |
We triangulate primary findings against official multilateral trade and standards databases, including UN Comtrade, WTO, US ITC, and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. No third-party market research firm data is used as a validation source.
We apply simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption) modeling. Birth-count data from national statistical offices, spend-per-baby indicators, and channel-level retail audits are cross-referenced to produce a reconciled market size.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
