 Mobile Sensing Fitness Market
: 2026 Global Outlook & Forecasts
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 234

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Mobile Sensing Fitness Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 5.300 B |
| 2026 | 6.140 B |
| 2027 | 7.110 B |
| 2028 | 8.230 B |
| 2029 | 9.530 B |
| 2030 | 11.03 B |
| 2031 | 12.78 B |

The Mobile Sensing Fitness Market covers body-worn and smartphone-embedded sensor systems (accelerometers, PPG, GPS, ECG, bioimpedance) plus the software, analytics and cloud infrastructure that convert raw signals into activity tracking, health monitoring, performance analytics and corporate wellness outputs.
This analysis covers sensor hardware, software and analytics platforms, and cloud data infrastructure across smartphones, smartwatches, fitness bands and sensor-integrated wearables, spanning activity tracking, health monitoring, sports performance analytics and corporate wellness. This analysis does not cover clinical-grade diagnostic devices, telehealth consultation platforms, or the broader digital fitness content and streaming market.
Published estimates for the Mobile Sensing Fitness Market diverge materially: base-year values cluster around USD 5.0–5.7 Billion, but 2032–2035 forecasts range from USD 14.2 Billion to USD 15.8 Billion, implying CAGRs from 9.6% to 15.8%. The spread reflects differing scope definitions rather than genuine demand disagreement.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 5.30B → 14.90B | 2025 | 2032 | 15.8% | Full stack: hardware + software + cloud | One published estimate (strategic research firm) |
| USD 5.05B → 15.84B | 2025 | 2034 | 13.5% | Wearables + apps, AI analytics included | A competing analysis |
| USD 5.69B → 14.20B | 2025 | 2035 | 9.57% | Product-centric: bands, watches, rings, clothing | A competing analysis |
| USD 5.4B → 14.4B | 2025 | 2034 | 11.13% | Sensor components only (narrower) | A competing analysis |
Our analysis suggests the 13.5–15.8% band is most defensible for a full-stack definition, because hardware-only or product-only scopes systematically exclude the software and cloud revenue layer that is growing fastest. The 9.57% figure likely understates growth by anchoring to hardware replacement cycles. For buyers, the practical implication is that budget models should assume mid-teens CAGR for software-attached revenue and high-single-digit growth for pure device sales.
Segmentation follows three axes—component, device type and application—with component economics increasingly favoring software and cloud over hardware. The table below isolates the non-geographic parents and their sub-segments.
| Parent Segment | Children | 2025 Share | Growth Signal |
|---|---|---|---|
| By Component | Sensors Hardware; Software & Analytics Platforms; Cloud Data Infrastructure | Hardware 44% | Software/cloud fastest at 18.6% |
| By Device Type | Smartphones; Smartwatches; Fitness Bands; Sensor-Integrated Wearables | Smartphones 32%, Smartwatches 31% | Sensor-integrated wearables fastest at 20.1% |
| By Application | Activity Tracking; Health Monitoring; Sports Performance Analytics; Corporate Wellness | Activity tracking 35%, Health monitoring 33% | Health monitoring 18.6%, performance 16.9% |
The critical structural read: hardware at 44% of revenue is the largest component but the slowest-growing, while software and cloud—though smaller in absolute terms—carry the highest CAGR. This divergence implies that component-level revenue mix will shift toward software by 2030, compressing margins for hardware-only suppliers.
North America leads the Mobile Sensing Fitness Market with 37% of 2025 revenue (USD 1.96 Billion), supported by premium wearable spending, subscription adoption and employer-sponsored wellness programs, but Asia-Pacific is the fastest-growing region at 18.8% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.27% |
| Asia-Pacific | 0.25% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | 2025 Share | 2025 Revenue (USD) | CAGR |
|---|---|---|---|
| North America | 37% | 1.96 Billion | 14.6% |
| Europe | 27% | 1.43 Billion | 14.9% |
| Asia-Pacific | 25% | 1.33 Billion | 18.8% |
| Latin America | 6% | 0.32 Billion | 16.3% |
| Middle East & Africa | 5% | 0.27 Billion | 15.4% |
The regional divergence carries a specific operational implication: North America's lead is a monetization lead (higher ARPU, subscription depth), not a volume lead. Asia-Pacific's 18.8% growth is volume-driven and smartphone-first, meaning vendors betting on premium hardware pricing in APAC will likely underperform those offering tiered device-plus-service bundles.
Growth is driven by the measurable gap between recommended and actual physical activity—the WHO reported roughly 1.8 billion adults (31% of the global adult population) were insufficiently active in 2024—combined with AI-enabled interpretation of multi-sensor data and expanding regulatory acceptance of wearable-derived endpoints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Physical inactivity gap | Driver | High (WHO 2024) | Creates demand for measurement, reminders, progress tracking |
| AI health interpretation | Driver | High | Converts raw signals into coaching, readiness, preventive alerts |
| Regulatory acceptance (FDA DHT guidance) | Driver | Medium-High | Opens clinical research and digital-endpoint revenue |
| Corporate wellness sponsorship | Driver | Medium | Employer/insurer pays, employee uses daily |
| Sensor accuracy vs. user expectation gap | Restraint | High | Undermines trust at medical-grade use cases |
| Battery and form-factor constraints | Restraint | Medium | Limits continuous monitoring and premium feature depth |
| Data privacy and fragmented standards | Restraint | Medium-High | Raises compliance cost; slows multi-region launches |
The balance of evidence favors the drivers through 2029: the inactivity gap is structural and policy-reinforced, while the restraints are engineering and compliance problems with identifiable solutions. However, the accuracy restraint is the single largest threat to the fastest-growing application (health monitoring), because health-adjacent claims invite regulatory scrutiny that activity tracking never faced.
Competition has separated into three strategic groups—platform ecosystem players, performance specialists, and emerging form-factor suppliers—each defending a different moat.
| Vendor | Strategic Group | Primary Moat | Notable Positioning |
|---|---|---|---|
| Apple | Platform ecosystem | OS + phone + HealthKit distribution | Sleep apnea and breathing-disturbance sensing |
| Samsung | Platform ecosystem | BioActive Sensor + Galaxy ecosystem | Clinical research partnerships (Alcedis) |
| Google (Fitbit) | Platform ecosystem | Android + AI coaching | Fitbit Premium AI health coaching |
| Garmin | Performance specialist | Training depth + athlete community | Connect+ at USD 6.99/month |
| WHOOP | Performance specialist | Membership-only service model | Annual subscription tiers |
| Oura | Emerging form factor | Continuous-wear ring + membership | 18-path PPG + temperature sensing |
| Huawei | Platform ecosystem | Integrated hardware + Health app scale | TruSense unified sensing architecture |
The differentiation read: platform players monetize reach and distribution, performance specialists monetize depth and community loyalty, and form-factor specialists monetize continuous-wear comfort. Our analysis suggests the strongest defensible position combines a hardware form factor with a paid interpretation layer—because historical data, personalized baselines and coaching plans raise switching costs far more than incremental sensor specifications.
Buyers should prioritize four selection criteria above all others: (1) proven measurement accuracy against independent validation, not vendor spec sheets; (2) interoperability with HealthKit, Health Connect and FHIR-based records, which determines whether data can move into clinical or enterprise workflows; (3) clarity of the subscription value proposition, since recurring revenue is what sustains post-purchase engagement; and (4) regulatory posture, particularly FDA digital health technology guidance alignment for any health-adjacent claims.
Procurement risk concentrates in two areas. First, sensor accuracy variability under motion artifact, skin-tone variation and wrist-size differences remains a documented challenge—Huawei's TruSense architecture and Samsung's BioActive redesign are direct responses to this. Second, data governance is fragmented: the European Health Data Space imposes authorization, minimization and opt-out requirements on wearable data, raising implementation cost for European deployments.
Switching costs are rising but unevenly. Consumers rarely switch hardware mid-cycle, but migrating longitudinal health history across ecosystems remains painful, which favors incumbents with mature platforms. For enterprise and corporate wellness buyers, the risk is vendor lock-in through device-plus-dashboard bundles; contracts should specify data portability and export formats.
The balance of evidence favors a software-and-services-led growth thesis over a hardware-volume thesis. Hardware remains necessary and large (44% of revenue), but it is the slowest-growing component and faces price compression; the sustainable margin sits in interpretation, coaching, research data services and enterprise dashboards. The strongest counter-argument is that hardware lock-in still gates access to the data layer—platform players like Apple and Samsung can bundle services for free to defend share, potentially commoditizing independent software vendors. We judge this risk real but bounded, because performance specialists (Garmin, WHOOP) and form-factor specialists (Oura) demonstrate that focused interpretation layers can sustain premium pricing outside the platform duopoly.
Our second judgment is that health monitoring, not activity tracking, should anchor go-to-market strategy through 2032. Health monitoring grows at 18.6% versus 13.7% for activity tracking, and it commands higher price points, subscription attach and clinical-research revenue. The counter-argument—that regulatory scrutiny and accuracy requirements make health monitoring expensive to enter—is valid, which is why we recommend partnership-led entry (device maker plus clinical research organization) rather than organic regulatory buildout.
Actionable strategy:
What would change our conclusion: independent, peer-reviewed validation showing consumer wearable accuracy converging with clinical-grade devices would accelerate health-monitoring monetization faster than our base case; conversely, sustained price declines in smartwatches (already down roughly 20% from 2021 to 2024 in the US) without offsetting subscription growth would push the market toward the low end of the forecast band.
Precise sub-segment forecasting, vendor-level revenue attribution and country-level demand elasticity require the full report's modeled datasets.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 15.8% from 2020-2034 |
| Segmentation |
|
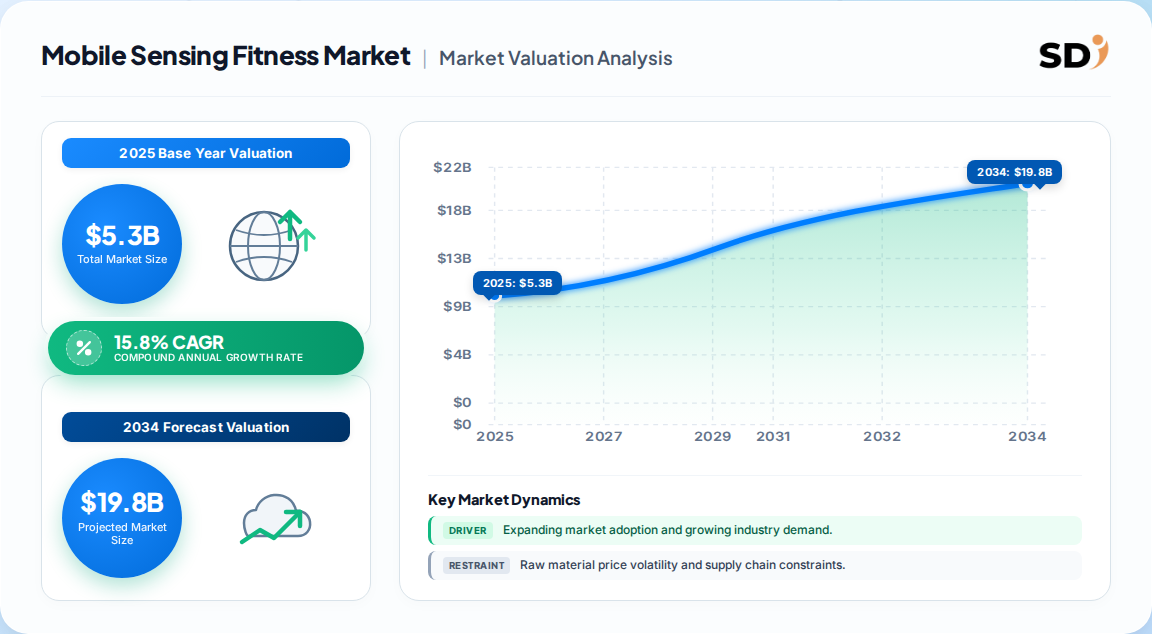
The Mobile Sensing Fitness Market was valued at USD 5.30 Billion in 2025 and is projected to reach USD 14.90 Billion by 2032, growing at a 15.8% CAGR. Competing estimates range from USD 5.05 Billion to USD 5.69 Billion for the base year depending on scope definition.
North America leads with 37% of 2025 revenue (USD 1.96 Billion), supported by premium wearable spending and subscription adoption. Asia-Pacific is the fastest-growing region at 18.8% CAGR, driven by smartphone-first adoption and local manufacturing scale.
Sensor-integrated wearables (smart rings, screen-free straps, chest sensors) are the fastest-growing device class at 20.1% CAGR. By application, health monitoring grows fastest at 18.6% CAGR, outpacing activity tracking at 13.7%.
Leading vendors include Apple, Samsung, Google (Fitbit), Garmin, Huawei, Oura and WHOOP. Platform players compete on ecosystem reach, performance specialists on training depth, and form-factor specialists on continuous-wear comfort and paid membership models.
The main constraint is the gap between user expectations and proven sensor accuracy for real health data, compounded by battery limitations and fragmented data-privacy regulation. These are engineering and compliance problems rather than demand problems, so they slow but do not cap growth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with sensor component suppliers, wearable device manufacturers, software and analytics platform developers, cloud infrastructure providers and enterprise wellness distributors. Decision-maker designations interviewed include VP-level Sourcing Leads, Heads of Product and R&D, Regulatory Affairs Directors and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & R&D Directors | 35% |
| Sourcing & Procurement Leads | 30% |
| Regulatory & Compliance Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Sensor Component & Hardware Suppliers | 40% |
| Wearable Device Manufacturers | 30% |
| Software & Analytics Platform Providers | 20% |
| Enterprise Wellness Distributors | 10% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and recognized technical standards bodies and industry associations. No third-party market-research publisher data is cited as a primary source.
Market sizing applies simultaneous top-down allocation (macroeconomic and industry segment spend) and bottom-up modeling (manufacturer shipment capacity, device ASP, subscription attach and end-use consumption). Divergent published estimates are reconciled through scope-normalization rather than simple averaging.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up shipment & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |