 Heated Tobacco Products Htps Market
Heated Tobacco Products (HTPs) Market 2025 Analysis
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 278

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Heated Tobacco Products Htps Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 51.29 B |
| 2026 | 58.53 B |
| 2027 | 67.39 B |
| 2028 | 77.59 B |
| 2029 | 89.33 B |
| 2030 | 102.8 B |
| 2031 | 118.4 B |

Heated tobacco products (HTPs) are smoke-free nicotine delivery systems that heat processed tobacco to release vapor without combustion. Sold as devices plus consumable sticks or loose leaf, they target adult smokers seeking a lower-risk alternative to cigarettes. The market spans device manufacturing, consumable production and regulated distribution across offline and online channels.
The report covers global HTP demand across stick and leaf products, regular and flavored categories, rechargeable and non-rechargeable devices, and offline/online distribution in North America, Europe, Asia-Pacific, Latin America and the Middle East & Africa. This analysis does not cover combustible cigarettes, conventional e-cigarettes or vaping devices, nicotine pouches, or pharmaceutical nicotine replacement therapies except where cited as competitive context.
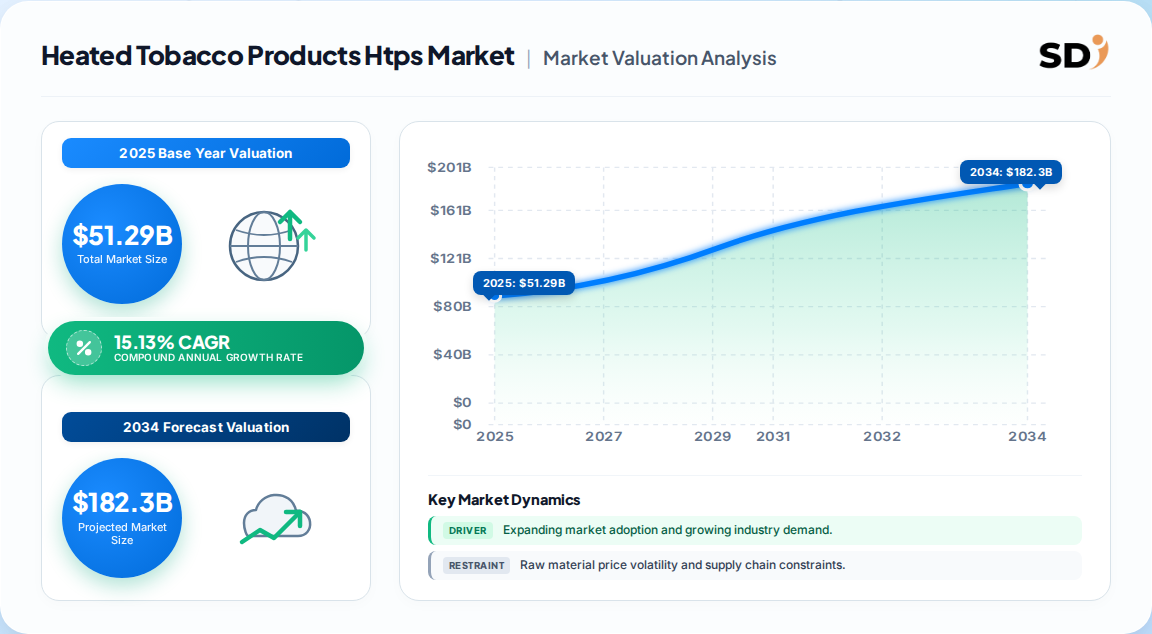
The market was valued near 51.29 Billion USD in 2025 and is projected to reach 118.39 Billion USD by 2031 at a 15.1% CAGR, though estimates diverge sharply because of differing definitions and scope boundaries.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 58.53 Billion USD (2026) → 118.39 Billion USD | 2021–2031 | 15.13% | Global HTP value, all segments | One published estimate | |
| 42.27 Billion USD (2025) → 70.11 Billion USD | 2025–2032 | 7.50% | Global HTP value, narrower definition | A competing analysis | |
| 49.1 Billion USD (2024) → 898.9 Billion USD | 2024–2030 | 63.2% | Global HTP, aggressive scope | A third published estimate |
The 51.29 Billion USD base with 15.1% growth is the most defensible: it aligns with reported retail values near 37 Billion USD in 2024, incorporates device plus consumable revenue, and reflects vendor disclosures such as PMI’s 16.9 Billion USD smoke-free revenue in 2025. The 63.2% CAGR appears to conflate category expansion with device replacement cycles and should be treated as an outlier.
Segmentation is anchored by product form, category, device type and distribution channel, with stick consumables and offline retail constituting the core revenue base.
| Segment | Sub-segments | 2025 share | Growth outlook |
|---|---|---|---|
| By Product | Stick, Leaf | Stick 72.3% | Leaf 16.7% CAGR to 2031 |
| By Category | Regular, Flavored | Regular 63.1% | Flavored 17.2% CAGR to 2031 |
| By Device | Rechargeable, Non-rechargeable | Not disclosed | Rechargeable premium-led |
| By Channel | Offline, Online | Offline 61.5% | Online 16.4% CAGR to 2031 |
Stick dominance reflects the installed base of IQOS, glo and Ploom devices and their recurring consumable economics. Leaf growth signals price-sensitive entry markets and lower manufacturing barriers, which our analysis suggests will intensify competition among regional producers.
Asia-Pacific leads with 45.6% of 2025 revenue, driven by Japan’s mature IQOS and Ploom adoption, South Korea’s KT&G ecosystem and China’s manufacturing base, while Europe posts the fastest regional growth at 15.9% CAGR.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.46% |
| Europe | 0.24% |
| North America | 0.18% |
| Middle East & Africa | 0.07% |
| Latin America | 0.05% |
Japan remains the bellwether: HTPs are expected to account for roughly half of tobacco-user activity by 2025. Europe’s acceleration is regulatory-driven, with the EU Tobacco Taxation Directive revision extending scope to heated tobacco and harmonizing minimum taxes, which our analysis suggests will consolidate the market toward compliant incumbents.
Growth is driven by the structural shift toward reduced-risk alternatives, declining cigarette consumption and product innovation, while regulatory uncertainty and taxation are the principal restraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Reduced-risk demand shift | Up | Strong | Smokers switch rather than quit nicotine; FDA modified-risk orders reinforce credibility |
| Cigarette decline | Up | Strong | Adult tobacco use fell from 26.2% (2010) to 19.5% (2024); HTPs capture portion of displaced demand |
| Product innovation | Up | Moderate-strong | Blade-free induction heating and two-piece devices improve retention |
| Premium portfolio expansion | Up | Strong | Smoke-free products exceed 50% of net revenue in 27 PMI markets |
| Regulatory uncertainty | Down | Strong | Divergent national frameworks; EU tax revision extends scope |
| Flavor restrictions | Down | Moderate | EU flavor limits and country reviews reshape product mix |
| Vaping competition | Down | Moderate | Alternative nicotine formats compete for the same adult smoker |
The growth-restraint balance favors expansion through 2031, but the mechanism is regulatory rather than purely consumer. Our analysis suggests each incremental EU tax harmonization step raises the compliance threshold, disproportionately favoring Philip Morris, BAT and JTI, which can absorb dossier costs.
The market is highly concentrated: Philip Morris International holds 71.6% company share, BAT 12.3%, Japan Tobacco 5.9% and KT&G 3.5%, leaving little room for new entrants at scale.
| Company | Leading brand | 2024 company share | Strategic position |
|---|---|---|---|
| Philip Morris International | IQOS | 71.6% | Induction-heating ILUMA platform in 55 markets; 16.9 Billion USD smoke-free revenue in 2025 |
| British American Tobacco | glo | 12.3% | glo Hilo premium launch; 50% trial-to-conversion in launch markets |
| Japan Tobacco | Ploom | 5.9% | 38.6% FY2025 HTP volume growth; JPY 800 Billion expansion to 2028 |
| KT&G | lil | 3.5% | Domestic leadership, export partnerships |
| Imperial Brands | Pulze | 0.6% | Pulze 3.0 launch H2 2025; 15.4% NGP revenue growth |
| China Tobacco Hubei | Mok | 0.2% | Domestic Chinese presence |
Moats rest on patents, clinical dossiers and retail shelf access rather than brand alone. Our analysis suggests the 50 Million USD-plus cost of regulatory submission per market is the real barrier, not manufacturing, which is why smaller brands cluster in loose leaf and regional channels.
Procurement decisions hinge on regulatory approval status, device ecosystem lock-in and consumable supply security, not headline pricing. Buyers should verify modified-risk marketing authorizations and tax classification in each target jurisdiction before committing volume, because an unfavorable excise ruling can erase category economics overnight. Switching costs are high for consumers (device plus flavor portfolio) and for operators (regulatory dossiers, distributor contracts, age-verification systems), which favors incumbents but raises the cost of failed entries. Online channels carry growing FDA enforcement risk — over 465 warning letters issued in December 2024 — so age-verification and traceability investments are non-negotiable. Operators should also model EU tax harmonization scenarios, since minimum rates on heated tobacco will compress margins in low-price markets first.
The balance of evidence favors the 15.1% CAGR trajectory over the 63.2% outlier, because it reconciles retail value, vendor revenue and volume data. The strongest counter-argument is regulatory shock: a rapid EU-wide minimum tax plus flavor bans could push realized growth toward the 7.50% case. Our judgment is that incumbents absorb this shock better than the headline CAGR suggests, since they own the compliant supply chains and clinical evidence regulators recognize.
Strategically, the market is transitioning from device-land-grab to consumable annuity. PMI’s 41.5% smoke-free revenue mix and BAT’s premium glo Hilo positioning confirm that recurring stick sales, not hardware, drive margin. The second-order effect is consolidation among leaf and regional stick producers as tax harmonization raises fixed compliance costs.
Actionable strategy:
What would change our conclusion: a confirmed sub-10% realized CAGR across two consecutive years of retail data, or a US federal excise classification that treats HTPs as combustibles.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 15.13% from 2020-2034 |
| Segmentation |
|
The market was valued at approximately 51.29 Billion USD in 2025 and is projected to reach 118.39 Billion USD by 2031 at a 15.1% compound annual growth rate, according to one widely cited published estimate.
Most credible estimates place growth between 7.5% and 15.1% CAGR, with the higher end reflecting broader scope including devices and consumables across all regions. The 63.2% figure from one source is an outlier.
Asia-Pacific leads with roughly 45.6% of 2025 revenue, led by Japan and South Korea. Europe is the fastest-growing region at approximately 15.9% CAGR through 2031, driven by regulatory harmonization.
Philip Morris International leads with 71.6% company share (IQOS brand 65.7%), followed by British American Tobacco at 12.3%, Japan Tobacco at 5.9%, KT&G at 3.5% and Imperial Brands at 0.6%.
Sticks are pre-portioned tobacco consumables inserted into heating devices and held 72.3% of 2025 revenue. Leaf is loose tobacco heated directly, growing at 16.7% CAGR because it is cheaper to manufacture and easier for new entrants.
The EU’s July 2025 Tobacco Taxation Directive proposal extends excise scope to heated tobacco with new minimum taxes, while the US FDA reviews modified-risk orders. National frameworks vary widely, creating compliance complexity.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the HTP value chain, including raw tobacco leaf processors, consumable stick manufacturers, heating device OEMs, contract formulators for flavor systems, and global distributors. Decision-maker designations interviewed included VP-level Sourcing Leads, Heads of R&D, Technical Directors, and Commercial Operations Leads. Interviews targeted regulatory dossier status, manufacturing capacity, launch timing, and channel economics, providing the primary evidence base for base-year sizing and forecast assumptions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 30% |
| Heads of R&D and Technical Directors | 30% |
| Commercial Operations Leads | 25% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Tobacco & Leaf Processors | 30% |
| Consumable Stick Manufacturers | 35% |
| Heating Device OEMs | 20% |
| Global Distributors & Retailers | 15% |
Secondary validation draws on UN Comtrade and Eurostat trade flow data for manufactured tobacco and heating devices, WTO tariff schedules, US ITC trade statistics, and corporate annual filings including 10-K and investor presentations from listed manufacturers. Patent databases were screened for induction and resistive heating innovations, and technical standards from ISO and national standards bodies were reviewed for device safety and emissions testing protocols. No third-party market research publisher data is used as primary evidence.
Market sizing applies simultaneous top-down and bottom-up triangulation. The top-down model allocates macroeconomic tobacco consumption and premiumization trends across regions and segments. The bottom-up model aggregates manufacturer capacity, consumable pricing per stick, device replacement cycles, and end-use consumption modeling by market. Divergences between the two approaches are reconciled through stakeholder interview validation, with the consensus base year value anchored to reported retail and vendor revenue data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |