 Consumer Telematics Market
 Outlook, Size & Growth 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 204

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Consumer Telematics Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 31.37 B |
| 2026 | 39.45 B |
| 2027 | 49.55 B |
| 2028 | 62.23 B |
| 2029 | 78.16 B |
| 2030 | 98.26 B |

Consumer telematics is the integration of telecommunications, GPS and onboard sensors into passenger vehicles to deliver services directly to drivers and owners — connected-car features, usage-based insurance, diagnostics, infotainment, safety and security, and driver assistance — delivered through embedded, tethered or smartphone-based hardware, software and subscription services.
This analysis covers global consumer-facing automotive telematics across hardware, software and services, spanning cellular, satellite, Wi-Fi and Bluetooth connectivity, and the application layers of fleet management, UBI, connected-car services, diagnostics, infotainment, safety and driver assistance. End users include OEMs, insurers, government agencies, telcos and retailers. This analysis does not cover commercial-only heavy-fleet telematics as a standalone market, industrial asset tracking, or OEM infotainment semiconductor supply.
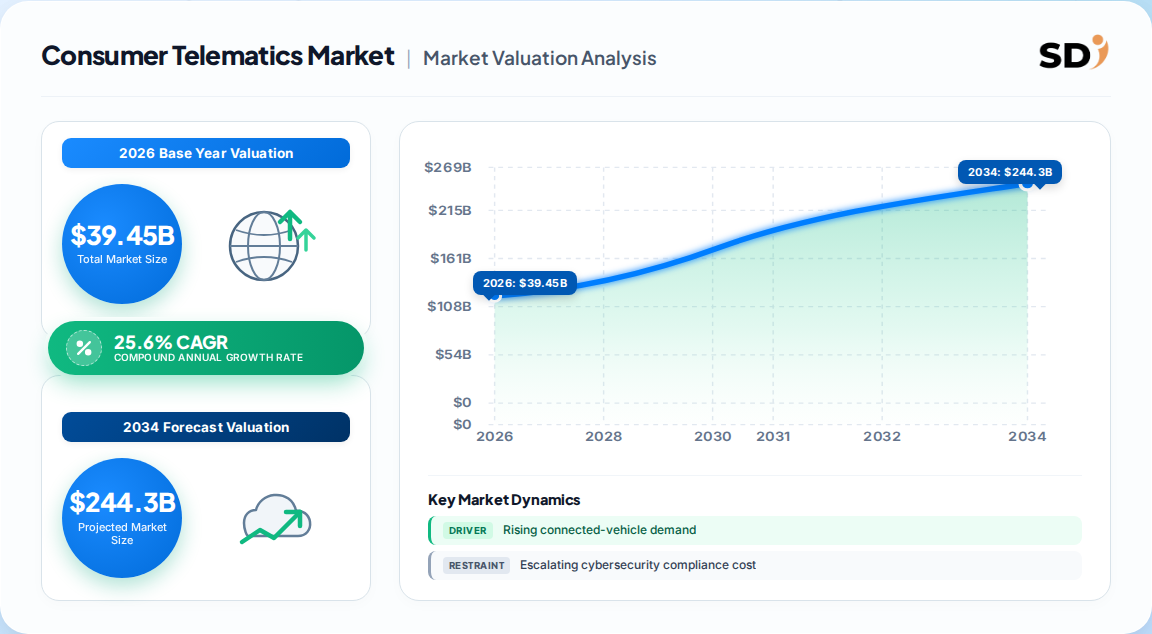
The consumer-facing telematics segment was worth roughly USD 39.45 billion in 2026, with published forecasts converging on a mid-20s CAGR through 2030. The divergence in absolute estimates below is driven almost entirely by definitional boundaries, not by demand disagreement.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 39.45 Billion | 2026 | 2030 | 25.6% | Consumer telematics only (hardware, software, services) | One published consumer-focused estimate |
| USD 58.14 Billion | 2026 | 2031 | 9.86% | All telematics incl. commercial fleet and OEM channel | A competing broad-market analysis |
| USD 26.72 Billion | 2025 | 2035 | 18.22% | Automotive telematics systems (vehicle-level) | A third published forecast |
Our analysis suggests the 25.6% CAGR figure is the most defensible for consumer scope: it isolates the connected-car, UBI and subscription-service revenue pools that are compounding fastest. The 9.86% figure is credible but diluted by mature commercial fleet hardware. Implication: buyers benchmarking entry timing should use the consumer-only curve, not the blended telematics curve, or they will underprice the growth window.
| Year | Market value |
|---|---|
| 2025 | USD 31.37 Billion |
| 2026 | USD 39.45 Billion |
| 2027 | USD 49.55 Billion |
| 2028 | USD 62.23 Billion |
| 2029 | USD 78.16 Billion |
| 2030 | USD 98.26 Billion |
Series derived from the stated base value and 25.6% CAGR.
Segmentation follows product type, connectivity, application and end user — with application and end-user splits mattering most commercially because they determine who pays the recurring subscription.
| Parent | Children |
|---|---|
| Product Type | Hardware (TCUs, GPS devices, OBD devices, in-vehicle monitors, sensors); Software (fleet, navigation, driver behavior, diagnostics, analytics); Services (roadside, emergency, tracking, insurance telematics, navigation) |
| Connectivity | Cellular, Satellite, Wi-Fi, Bluetooth |
| Application | Fleet management, usage-based insurance, connected car services, vehicle diagnostics, infotainment, safety & security, driver assistance |
| End User | Automotive OEM, insurance companies, government agencies, telecom companies, retailers |
North America led the consumer telematics market in 2025 on the back of mature UBI adoption and high connected-vehicle penetration, while Asia-Pacific is the fastest-growing region as regulatory mandates and EV scale compress unit costs.
| Region | Market Share (%) |
|---|---|
| North America | 0.31% |
| Europe | 0.28% |
| Asia-Pacific | 0.3% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | Estimated share |
|---|---|
| North America | 31% |
| Asia-Pacific | 30% |
| Europe | 28% |
| Latin America | 6% |
| Middle East & Africa | 5% |
This divergence implies a two-speed market: North America monetizes services today, while Asia-Pacific builds the installed base that will monetize tomorrow. Vendors with North American UBI relationships should be locking APAC OEM channel partnerships now, before factory-fit connectivity standardizes.
Rising connected-vehicle demand is the primary driver, reinforced by regulation and insurer economics; the main brake is compliance cost and hardware price volatility, not consumer appetite.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Connected-vehicle demand | Driver | Strong | OEM factory-fit connectivity expands addressable base |
| Regulatory mandates (eCall, AIS 140) | Driver | Strong | Mandated units create universal connectivity baseline |
| Usage-based insurance adoption | Driver | Strong | Behavioural pricing creates recurring data demand |
| 5G / edge / OTA analytics | Driver | Moderate | Enables predictive maintenance and V2X services |
| Cybersecurity compliance cost (UNECE WP.29, ISO/SAE 21434) | Restraint | Moderate | Raises fixed cost, pressures smaller vendors |
| TCU hardware price volatility | Restraint | Moderate | Compresses hardware margins and OEM BOM |
| Data-sovereignty fragmentation | Restraint | Moderate | Multi-jurisdiction compliance delays rollout |
| Legacy fleet inertia | Restraint | Weak | Slows aftermarket replacement cycles |
Verizon Connect, Continental and Trimble anchor the field, with TomTom, Agero, Geotab and AT&T competing on channel access, data depth and service breadth rather than raw hardware.
| Company | Primary strength | Strategic position |
|---|---|---|
| Verizon Connect | Fleet + consumer connectivity, network ownership | Integration-led moat |
| Continental AG | OEM TCU hardware and embedded systems | Factory-fit incumbent |
| Trimble Inc. | Analytics and fleet software | Data/software margin leader |
| TomTom | Mapping, navigation, location data | Content and licensing moat |
| Agero Inc. | Roadside and emergency services | Service-network moat |
| Geotab | OEM integrations and open platform | Ecosystem/API moat |
| AT&T Inc. | Connectivity and SIM provisioning | Network-scale moat |
Differentiation is shifting from hardware specification to data rights, integration breadth and insurer relationships. Our analysis suggests the durable moats are OEM factory-fit contracts and insurer data pipelines — both are slow to displace, which explains the medium concentration rather than fragmentation.
Selection criteria should weight data ownership, integration breadth and regulatory readiness above hardware unit price. Procurement risk concentrates in three areas: TCU supply-chain volatility, multi-jurisdiction data-sovereignty compliance, and vendor lock-in through proprietary data formats. Buyers should insist on contractual data portability and standards-based APIs (ISO/SAE 21434 alignment, UNECE WP.29 compliance evidence) before signing multi-year service contracts. Switching costs rise sharply once telematics data is embedded in underwriting models or maintenance workflows, so renegotiation leverage decays after year two. Operators should also model total cost including connectivity subscriptions, not just device cost, because recurring connectivity is where budgets drift. Precise sub-segment forecasting by application and geography requires the full dataset.
The balance of evidence favors aggressive positioning in consumer telematics services, not hardware. The 25.6% CAGR consumer-only curve, insurer behavioural pricing momentum and mandated connectivity together create a rare combination: a regulatory floor under unit volumes and a commercial ceiling set by subscription monetization. The strongest counter-argument is that OEM factory-fit consolidation will commoditize third-party hardware and squeeze aftermarket vendors — a real risk, but one that shifts value to software and data rather than destroying it.
Our judgment is that the winners will be defined by data rights and insurer/OEM contracts, not device margins. The 9.86% blended telematics figure understates consumer opportunity precisely because it averages in mature commercial hardware; decision-makers should treat the consumer curve as the planning baseline and stress-test against hardware price deflation.
What would change this conclusion: a sharp fall in OEM embedded-unit pricing combined with stalled UBI adoption would compress the services premium and favor pure hardware scale players instead.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 25.6% from 2020-2034 |
| Segmentation |
|
It is growing at roughly 25.6% CAGR from 2026 to 2030, expanding from USD 39.45 billion to USD 98.26 billion — materially faster than the broader telematics market's blended ~10% growth.
North America led in 2025 on mature usage-based insurance and connected-vehicle penetration. Asia-Pacific is the fastest-growing region, driven by regulatory mandates and rapid EV scale.
Fleet management and usage-based insurance dominate revenue today, while connected car services and real-time diagnostics carry the strongest subscription growth and margin potential.
Verizon Connect, Continental AG, Trimble Inc., TomTom, Agero Inc., Geotab and AT&T are among the leading players, competing on connectivity, OEM integration, data analytics and service networks.
Cybersecurity compliance costs under UNECE WP.29 and ISO/SAE 21434, TCU hardware price volatility, and fragmented data-sovereignty rules raise fixed costs and pressure smaller vendors.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Fieldwork comprised in-depth interviews with stakeholders across the consumer telematics value chain: telematics control unit and OBD hardware suppliers, embedded software and analytics providers, connectivity/MNO partners, OEM connectivity programme owners, and insurance underwriting and distribution leads. Interviews were conducted with decision-maker designations including VP of Product & Connectivity, Heads of Telematics Engineering, Commercial Operations Leads for insurance partnerships, and Director-level procurement owners for OEM factory-fit programmes.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & Connectivity Leads | 35% |
| Telematics Engineering Heads | 28% |
| Commercial Operations Leads | 22% |
| Procurement Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Hardware & TCU Suppliers | 40% |
| Software & Analytics Providers | 32% |
| Connectivity & MNO Partners | 18% |
| Insurers & OEM Programmes | 10% |
Secondary validation drew on official multilateral and standards sources — UN Comtrade and Eurostat trade flows for automotive electronics, US ITC filings, corporate annual reports and investor presentations (10-K and equivalent filings), patent databases for telematics and UBI analytics, and recognized technical standards bodies including UNECE WP.29, ISO/SAE 21434 and regional eCall/AIS 140 regulatory frameworks.
Sizing combined simultaneous Top-Down allocation (macroeconomic connected-vehicle penetration, OEM fitment rates, insurer programme volumes) and Bottom-Up modelling (manufacturer unit capacity, device and subscription pricing, end-user service consumption). Divergent published estimates were reconciled against explicit scope definitions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |