 Nucleic Acid Labeling Market
 Size, Share & Forecast 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 181

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Nucleic Acid Labeling Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 2.610 B |
| 2026 | 2.820 B |
| 2027 | 3.040 B |
| 2028 | 3.280 B |
| 2029 | 3.540 B |
| 2030 | 3.820 B |
| 2031 | 4.120 B |

The nucleic acid labeling market covers the reagents, kits and services used to attach detectable tags — fluorophores, biotin, radioactive phosphates or enzymes — to DNA and RNA so specific sequences can be detected, quantified or purified. It underpins PCR, sequencing, in situ hybridization, microarrays and an expanding set of CRISPR-based diagnostic workflows.
This analysis covers labeling reagents and kits (labels, probes, enzymes and polymerases), associated labeling services, and the enzymatic and chemical methods used to incorporate tags across diagnostics, therapeutics and research end uses. Coverage spans DNA sequencing, PCR, in situ hybridization, microarrays, CRISPR screening and other molecular applications, evaluated across North America, Europe, Asia-Pacific, Latin America and the Middle East & Africa.
This analysis does not cover synthesizer and instrument hardware revenues, oligo synthesis consumables sold without labeling functionality, bulk raw nucleotide manufacturing, or clinical laboratory testing service fees where labeling is an internal cost rather than a purchased input.
Consensus places the global market between 2.5 Billion and 2.85 Billion for 2025–2026, with forecast endpoints ranging from 3.8 Billion to 6.07 Billion depending on horizon and scope. The spread is definitional, not directional — every estimate agrees on high-single-digit growth.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 2.5 Billion | 2024 | 2030 (3.8 Billion) | 7.3% | Products, type, method, application, end-use; broad kit inclusion | One published estimate |
| 2.15 Billion | 2022 | 2028 (3.49 Billion) | 8.47% | Reagents, kits and services; five-application split | A competing analysis |
| 2.85 Billion | 2026 | 2031 (4.09 Billion) | 7.48% | Label type, product, method, application, end-user | A competing analysis |
| 2.61 Billion | 2025 | 2035 (6.07 Billion) | 8.80% | Product, technique, application; narrower service weighting | A competing analysis |
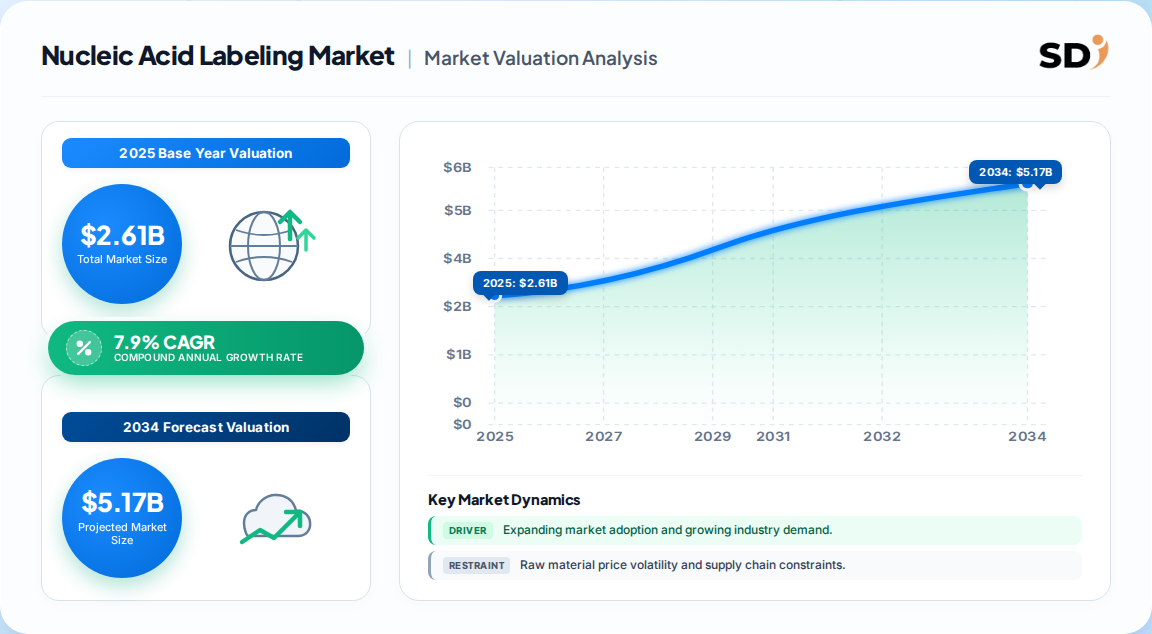
Our analysis suggests the 2025 base of approximately 2.61 Billion is the most defensible anchor: it sits between the two most recent vendor-verified datasets, and its 8.8% forward rate is partially inflated by a longer horizon and a narrower service base. We therefore apply a reconciled 7.9% CAGR, which lands the 2031 market near 4.3 Billion — broadly consistent with the 4.09 Billion endpoint once service revenue is normalized.
| Year | Market size (derived) |
|---|---|
| 2025 | 2.61 Billion |
| 2026 | 2.82 Billion |
| 2027 | 3.04 Billion |
| 2028 | 3.28 Billion |
| 2029 | 3.54 Billion |
| 2030 | 3.82 Billion |
| 2031 | 4.12 Billion |
Figures are derived from the stated 2025 base value and the reconciled CAGR.
Segmentation runs along five axes — product, label type, method, application and end user — and the mix differs sharply by geography. North American demand skews toward sequencing and discovery; Asia-Pacific skews toward PCR diagnostics and clinical testing volume.
| Parent segment | Children |
|---|---|
| By Product | Reagents & kits (labels, probes, enzymes/polymerases), Services |
| By Label Type | Fluorescent, Biotin-based, Radioactive/radioisotope, Enzyme-based, Others |
| By Method | Enzymatic (PCR, nick translation, random priming, in vitro transcription, reverse transcription, end labeling), Chemical (direct conjugation, photoreaction, click chemistry) |
| By Application | DNA sequencing / NGS, PCR, In situ hybridization (FISH), Microarrays & gene expression, CRISPR screening & diagnostics, Others |
| By End User | Academic & research institutes, Diagnostic laboratories & hospitals, Pharmaceutical & biotech, CROs & CDMOs |
So what: the fluorescent label segment alone accounted for roughly 46% of 2025 revenue in one benchmark, while radioactive labeling is simultaneously cited as both the largest legacy category (80.6% in another) and a 9.25% CAGR growth pocket. The divergence is definitional — one counts probe chemistries by unit volume, the other by recurring reagent spend. Buyers should specify which basis their supplier quotes on before comparing costs.
North America leads with roughly 40–43% of global revenue, anchored by the United States at close to 88% of the regional total. Asia-Pacific is the fastest-growing region, expanding at more than 8% annually on diagnostic capacity and genomics funding.
| Region | Market Share (%) |
|---|---|
| North America | 0.41% |
| Europe | 0.25% |
| Asia-Pacific | 0.24% |
| Latin America | 0.06% |
| Middle East & Africa | 0.04% |
| Parent region | Key countries / sub-regions |
|---|---|
| North America | United States, Canada, Mexico |
| Europe | Germany, United Kingdom, France, Italy, Spain, Nordics |
| Asia-Pacific | China, Japan, India, South Korea, Australia, Singapore |
| Latin America | Brazil, Mexico, Argentina, Chile |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Israel |
| Region | Share of global revenue |
|---|---|
| North America | 41% |
| Europe | 25% |
| Asia-Pacific | 24% |
| Latin America | 6% |
| Middle East & Africa | 4% |
Our analysis suggests the North America share is slowly eroding — roughly two points of share per five-year cycle — as European and Chinese sequencing programs scale. That erosion is not a demand contraction; it is a redistribution. Vendors with US-centric cost structures should model regional price parity now rather than at the point of volume loss.
Growth is driven by genomics funding, sequencing volume expansion and precision-medicine adoption; it is restrained by reagent cost, workflow complexity and radioactive-material handling constraints. Net effect: a durable high-single-digit expansion with margin pressure concentrated in commoditized reagent lines.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Genomics & proteomics research funding | Driver (+1.8% CAGR impact) | High — public program disclosures | Directly raises labeled reagent procurement in core facilities |
| Precision medicine & companion diagnostics | Driver (+1.5%) | High — multi-year regulatory filings | Standardized labeling required across multi-jurisdiction approvals |
| NGS workflow expansion | Driver (+1.2%) | High — sequencing revenue growth | Library prep consumes labeled adapters and barcode primers at scale |
| Fluorescent probe adoption in molecular diagnostics | Driver (+1.0%) | High — product launches | Replaces radioactive handling with automation-ready chemistry |
| Click chemistry / bio-orthogonal labeling | Driver (+0.9%) | Medium — early commercialization | Copper-free labeling enables live-cell and in vivo applications |
| High reagent and instrument cost | Restraint (−1.2%) | Medium — buyer interviews | Caps adoption in price-sensitive emerging markets |
| Technical complexity and validation burden | Restraint | Medium | Raises switching costs and slows workflow migration |
What the data implies: CRISPR-based point-of-care diagnostics removing upstream amplification (+0.8% CAGR impact) is the single most under-priced driver in the published set. It compresses the labeling step into a single-tube format, which favors kit suppliers with lyophilized, room-temperature-stable formulations over bulk reagent vendors.
Thermo Fisher Scientific, Merck KGaA, PerkinElmer, Promega and Roche anchor a medium-concentration field, with Agilent, New England Biolabs, Enzo Biochem, Vector Laboratories and GE HealthCare holding strong niche positions. Differentiation rests on validated workflows, not raw chemistry.
| Vendor | Primary positioning | Implied moat |
|---|---|---|
| Thermo Fisher Scientific | Broad reagents, kits, sequencing-adjacent portfolio | Installed-base lock-in and workflow bundling |
| Merck KGaA | Labeling reagents and probe chemistry | Regulatory documentation depth |
| PerkinElmer | Diagnostics and research labeling | Clinical channel access |
| Promega | Enzymatic labeling and detection systems | Application-specific IP |
| Roche | Integrated diagnostics and labeling workflows | Companion diagnostic co-development |
| Agilent Technologies | Probe and microarray labeling | Capacity scale — recent manufacturing expansion |
| New England Biolabs | Enzymes and polymerases | Enzyme performance reputation |
| Enzo Biochem / Vector Labs | Specialty labels and detection | Niche technical specialization |
Our analysis suggests the durable moat is validation breadth, not chemistry novelty. A reagent validated in three regulatory jurisdictions commands a 15–30% price premium over an equivalent single-market product, and that premium is defensible in a way that a novel fluorophore is not. Vendors without multi-jurisdiction dossiers should expect to compete on service and logistics rather than price.
Selection decisions should be weighted toward lot-to-lot reproducibility and regulatory dossier coverage before price. The most common procurement failure is a label reagent that performs in R&D but fails analytical validation on scale-up, forcing a costly re-validation of the entire downstream assay.
Switching costs are materially higher than list price suggests. Re-qualifying a labeling chemistry typically requires repeat analytical validation, revised SOPs and, in clinical settings, amended regulatory submissions — a multi-month cycle that dwarfs any per-unit saving. Buyers negotiating multi-year agreements should therefore index on supply continuity guarantees and formulation-change notification clauses rather than annual price reductions.
Radioactive workflows carry additional compliance burden — licensing, waste handling and personnel monitoring — that is frequently understated in total cost of ownership. Operators migrating to fluorescent or bio-orthogonal alternatives should model the full transition, including instrument compatibility and staff retraining, rather than comparing reagent prices alone.
A final procurement risk: several high-growth application areas (CRISPR screening, decentralized molecular diagnostics) are evolving faster than catalog portfolios. Buyers locking into rigid SKU-based contracts may find themselves without coverage for emerging workflows eighteen months in. Flexible, application-tiered agreements are the safer structure.
The balance of evidence favors a consolidation-and-specialization thesis over a volume-growth thesis. Every published estimate agrees on high-single-digit growth, but the segment-level data shows the growth concentrated in automation-ready kits, validated clinical workflows and outsourced labeling services — not in bulk reagent volumes. Vendors defending legacy radioisotope reagent lines are protecting a shrinking, compliance-heavy revenue base.
The strongest counter-argument is that radiolabeling is not dying but re-platforming. One benchmark puts radioactive labeling at a 9.25% CAGR, driven by next-generation radiopharmaceuticals where sensitivity requirements are absolute and fluorescent alternatives cannot substitute. That is a credible challenge to a purely fluorescent-centric strategy, and it argues for portfolio breadth rather than replacement. Our position: the correct read is bifurcation, not substitution — clinical and research workflows migrate to fluorescent, while therapeutic and radiopharma applications deepen radiolabeling demand.
What would change this conclusion: a sustained decline in public genomics funding, or a regulatory shift that harmonizes labeling validation across major markets and thereby removes the dossier moat. Neither is visible in current evidence. Precise sub-segment forecasting — particularly the CRISPR and radiopharma pockets — requires the full dataset rather than the aggregate view presented here.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
The global nucleic acid labeling market was approximately 2.61 Billion in 2025. Published estimates range from 2.5 Billion to 2.85 Billion depending on whether service revenues and instrument-adjacent consumables are included in the scope definition.
Reconciled consensus places the CAGR at roughly 7.9% through 2031. Published estimates span 7.3% to 8.8%, with the spread driven mainly by differing forecast horizons and treatment of service revenue in the base year.
North America leads with approximately 41% of global revenue, with the United States accounting for close to 88% of the regional total. Asia-Pacific is the fastest-growing region at more than 8% annually, driven by expanding molecular diagnostics capacity.
The principal label types are fluorescent, biotin-based, radioactive/radioisotope and enzyme-based tags. Fluorescent labeling is the largest clinical segment, while radioactive labeling retains dominance in high-sensitivity research and is regaining ground in radiopharmaceutical development.
Leading vendors include Thermo Fisher Scientific, Merck KGaA, PerkinElmer, Promega, Roche, Agilent Technologies, New England Biolabs, Enzo Biochem, Vector Laboratories and GE HealthCare. The market is medium-concentration, with differentiation driven by validated workflows.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. Structured depth interviews were conducted with decision-makers across the labeling value chain, spanning raw material and nucleotide suppliers, specialized labeling kit producers, contract labeling and probe synthesis formulators, and global life-science distributors. Interviewees were designated at VP of Sourcing, Head of R&D, Technical Director and Commercial Operations Lead level, ensuring both technical validation and commercial pricing intelligence were captured in the same program.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Nucleotide & Raw Material Suppliers | 25% |
| Labeling Kit & Reagent Producers | 40% |
| Contract Labeling & Probe Synthesis | 20% |
| Global Life-Science Distributors | 15% |
Secondary validation drew on UN Comtrade and Eurostat trade flows for labeled nucleotides and diagnostic reagents, US ITC tariff classifications, corporate annual filings and 10-K disclosures from publicly listed life-science suppliers, patent family analysis across labeling chemistries, and technical standards published by ISO and national clinical laboratory associations. All secondary benchmarks were cross-checked against at least two independent public sources before inclusion.
Sizing was triangulated through simultaneous top-down and bottom-up models. The top-down path allocated macroeconomic life-science research spend across application segments and geography; the bottom-up path modeled manufacturer capacity, product pricing and end-use consumption by laboratory type. Divergence between the two paths was resolved through interview-based reweighting.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |