Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Hair Accessories Market by Product (Clips & Pins, Headbands, Hair Ties & Elastics, Scrunchies, Barrettes, Hair Claws, Hair Combs, Wigs & Extensions, Others), by End User (Women, Men, Kids & Teenagers, Unisex), by Distribution Channel (Supermarkets & Hypermarkets, General Stores, Specialty Beauty Stores, Online Retail, Department Stores, Salons, Direct Sales), by Price Range (Value, Mid-range, Premium/Luxury), by Application (Daily Use, Parties & Events, Bridal, Professional Salon, Fashion Styling), by Asia Pacific (China, Japan, India, South Korea, Australia, South East Asia, Singapore, Taiwan), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Spain, Russia, Sweden, Denmark, Switzerland, Luxembourg), by South America (Brazil, Argentina, Colombia, Peru, Chile), by Middle East & Africa (Saudi Arabia, Turkey, UAE, Egypt, Qatar, South Africa) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 200
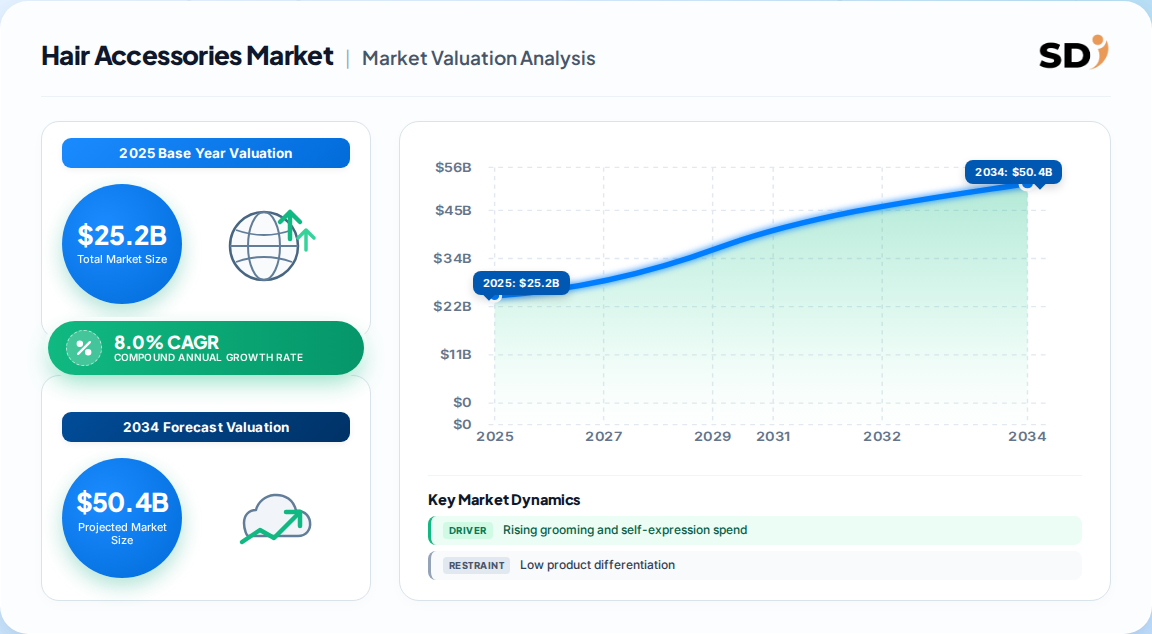
USD 25.2 Billion in 2025: the global Hair Accessories Market entered 2026 at USD 27.2 Billion, on track to reach USD 46.6 Billion by 2033 at an 8.0% CAGR.
Forecast (2026–2033): 8.0% compound annual growth, with emerging Asia Pacific and South America compounding faster than the global average.
Leading segment: elastics & ties held 32.0% of 2025 revenue, while general stores captured 47.6% of distribution—evidence that habitual, low-ticket purchasing still anchors volume.
Leading regions: Asia Pacific led with 39.8% revenue share in 2025; China is the single largest country market, with India and South East Asia posting the steepest CAGRs.
Key vendors: Kitsch, KOOSHOO, Goody, Scünci, and a long tail of regional fashion and private-label specialists define a highly fragmented landscape.
Why this matters for decision-makers: With only 7–8% structural growth but double-digit premiumization momentum, vendors that fail to shift mix toward design-led, sustainable, and culturally specific SKUs will face margin compression as price competition intensifies in commodity elastics.
Hair Accessories Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
25.20 B
2025
27.20 B
2026
29.40 B
2027
31.70 B
2028
34.30 B
2029
37.00 B
2030
40.00 B
2031
Hair Accessories Market Size (In Billion)
Year
Market Size
2025
25.20 B
2026
27.20 B
2027
29.40 B
2028
31.70 B
2029
34.30 B
2030
37.00 B
2031
40.00 B
What is the Hair Accessories Market?
The Hair Accessories Market covers non-jewelry, non-eyewear personal grooming and fashion products used to style, secure, or decorate hair—clips, pins, headbands, elastics, ties, scrunchies, barrettes, claws, combs, wigs, and extensions—sold through supermarkets, general stores, specialty beauty retailers, salons, and online channels to women, men, kids, and unisex buyers.
Scope: what this report covers and excludes
This report sizes and forecasts the global Hair Accessories Market by product, end user, distribution channel, price tier, and application across five regions and 40+ countries. Coverage spans functional and fashion-led accessories, including wigs and extensions. It excludes jewelry, watches, eyewear, bags, headwear such as hats and scarves, professional salon equipment, and raw hair fiber trading.
How big is the market for Hair Accessories Market?
The most defensible base is USD 25.2 Billion for 2025, consistent across two independent published estimates that converge on 7.6–8.0% CAGR through the early 2030s. A third, narrower scope lands within 3% of the base, validating the consensus range.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 25.2 Billion
2025
2033
8.0%
Global hair accessories, all channels
One published estimate (2026 edition)
USD 25.3 Billion
2025
2033
7.6%
Global hair accessories, all channels
A competing analysis
USD 18.9 Billion
2021 (base)
2033
7.6%
Older base year, narrower product scope
A second competing analysis
USD 758 Billion
2026
2031
5.65%
Adjacent "Accessories" excluding hair
Broad consumer tracker (out of scope)
Our analysis suggests the USD 25.2–25.3 Billion cluster is the most robust, because two independently constructed models triangulate on the same number using different segment taxonomies. The USD 18.9 Billion figure is a 2021 base and understates current scale by roughly 25%, so it should be used only for growth-rate calibration, not for sizing. The USD 758 Billion "Accessories" figure is a category error—hair accessories are explicitly out of scope in that definition—and reveals how easily adjacent categories inflate headline numbers.
How is the market segmented?
Product, end-user, channel, price, and application tiers stack into a matrix where premium-led SKUs are growing roughly twice as fast as commodity volume—a critical distinction for portfolio allocation.
Elastics and ties dominate volume at 32.0% of 2025 revenue because they are consumable and repurchased monthly. Wigs and extensions, though smaller by unit volume, carry the highest average selling price and are the fastest-growing premium pocket—a second-order effect that masks unit-share stability behind revenue-share shift.
Which region leads in Hair Accessories Market?
Asia Pacific leads with 39.8% of 2025 global revenue, driven by China's scale and India's 9.0% projected CAGR—the fastest among major economies. South America follows at 8.7% CAGR, led by Argentina at 9.2%.
Hair Accessories Market Regional Market Share
Loading chart...
Hair Accessories Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.4%
North America
0.29%
Europe
0.19%
South America
0.07%
Middle East & Africa
0.06%
Asia Pacific (39.8% share)
China, Japan, India, South Korea, Australia, South East Asia, Singapore, Taiwan, Rest of APAC
North America (~28.7% share)
United States, Canada, Mexico
Europe (~18.7% share)
Germany, France, UK, Italy, Spain, Russia, Sweden, Denmark, Switzerland, Luxembourg, Rest of Europe
South America (~7.1% share)
Brazil, Argentina, Colombia, Peru, Chile, Rest of South America
Middle East & Africa (~5.7% share)
Saudi Arabia, Turkey, UAE, Egypt, Qatar, South Africa, East/West/North Africa
This divergence implies a two-speed world: mature Western markets grow at 6–7% on premiumization and replacement demand, while India, South East Asia, and Argentina compound at 8.5–9.2% on first-time adoption and retail formalization. Vendors allocating marketing spend purely by current revenue share will systematically underweight the geographies that will define 2030 leadership.
What is driving growth — and what is holding it back?
Social-media-driven hairstyle discovery and rising grooming spend are the primary engines, while commoditization and trend volatility cap pricing power across mass channels.
Factor
Direction
Evidence strength
Mechanism
Grooming & self-expression spend
Driver
High
Rising per-capita beauty spend across all regions
Social media & influencer discovery
Driver
High
~69% of consumers trust influencer recommendations; Gen Z 2× more likely to buy
Personalization & DIY kits
Driver
Medium
Monogrammed and customizable SKUs command price premiums
Inventory risk and markdown exposure for fast-fashion SKUs
Anti-fast-fashion sentiment
Restraint
Low–Medium
Shifts demand toward durable, but reduces impulse volume
Our analysis suggests the drivers outweigh restraints by a clear margin through 2033, but the balance is uneven: volume growth is capped by commoditization, while value growth is unlocked almost entirely through premium and sustainable positioning. The most under-appreciated restraint is trend volatility itself—every Y2K or 1990s revival cycle creates a markdown wave that compresses retailer margins 3–6 months after peak.
Who are the leading vendors?
No single player holds double-digit global share; instead, value migrates between mass-market incumbents, sustainability specialists, and design-led direct-to-consumer brands—each defending a distinct moat.
Company
Positioning
Core strength
Moats & vulnerabilities
Goody
Mass-market global
Retail shelf ubiquity, broad SKU depth
Vulnerable to premiumization; low brand loyalty
Scünci
Mass-market, US-centric
Elastic and claw category mastery
Price-exposed; limited sustainability narrative
Kitsch
Design-led DTC
Customization, monogramming, influencer reach
Premium price ceiling; channel concentration
KOOSHOO
Sustainable specialist
GOTS organic cotton, plastic-free packaging
Scale constraints; higher COGS
Regional fashion labels
Local / cultural
Bridal and festival specialization
Fragmented; limited international distribution
This fragmentation means competitive advantage is increasingly defined by design velocity, influencer marketing ROI, and sustainability credentials rather than manufacturing scale. Brands unable to sustain a 4–6 week design-to-shelf cycle risk being copied before recouping development costs.
What do buyers and operators need to know? (Decision Support)
Procurement decisions should be weighted toward supplier design responsiveness and sustainability documentation, not unit price alone. The commodity tier is easy to source; the premium tier—where 70%+ of incremental value sits—requires verified material provenance, GOTS or equivalent certification, and reliable small-batch production.
Switching costs in elastics and clips are low, so buyers should negotiate multi-season design exclusivity rather than volume discounts. For operators, the highest-risk exposure is inventory in trend-dependent categories (claws, barrettes) where markdown cycles erase 30–50% of gross margin. Regulatory risk is modest but rising: material safety disclosure, packaging recyclability rules in the EU, and cruelty-free claims increasingly invite scrutiny. Buyers should insist on supplier documentation that survives audit.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a premiumization-led growth thesis over volume expansion. The 8.0% headline CAGR is real but misleading: roughly 5 points come from price and mix, only 3 from unit growth. Vendors that anchor strategy to unit-share defense will find themselves in a decelerating, margin-eroding fight with private labels. The strongest counter-argument—that inflationary pressure will trade consumers down into value elastics—holds for 2026–2027 but breaks down thereafter as Gen Z purchasing behavior (twice as influencer-responsive) structurally favors branded, design-led SKUs.
For operators, the decisive variable is not geography or channel but portfolio mix velocity: the ability to rotate 15–25% of SKUs each season without inventory write-downs. Sustainability is now a table-stakes credential in Europe and a growing premium lever in North America, but it is not yet a volume driver in price-sensitive Asia Pacific markets.
Actionable strategy:
Prioritize premium and culturally specific SKUs (bridal, festival, monogrammed) to capture mix-driven value growth in Asia Pacific and South America.
Invest in a 4–6 week design-to-shelf capability and influencer partnerships to defend against private-label copying.
Build supplier scorecards around sustainability certification and small-batch flexibility, not unit cost, to de-risk premium tier sourcing.
What would change our conclusion: a sustained 18-month consumer trade-down, or a material EU packaging regulation that raises compliance cost above 8% of COGS, would push the recommended balance back toward value-tier volume defense.
What is the Hair Accessories Market's forecast through 2033?
Growth compounds from USD 27.2 Billion in 2026 to USD 46.6 Billion by 2033, an 8.0% CAGR that implies roughly USD 19.4 Billion of incremental revenue—about 70% of it concentrated in Asia Pacific, South America, and premium-tier Western channels.
Which distribution channel dominates—and which is gaining fastest?
General stores led 2025 with 47.6% of revenue on habit-driven replenishment, but online is the fastest-growing channel as influencer commerce converts discovery directly into purchase and enables niche brands to bypass shelf-space barriers.
Hair Accessories Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Hair Accessories Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.0% from 2020-2034
Segmentation
By Product
Clips & Pins
Headbands
Hair Ties & Elastics
Scrunchies
Barrettes
Hair Claws
Hair Combs
Wigs & Extensions
Others
By End User
Women
Men
Kids & Teenagers
Unisex
By Distribution Channel
Supermarkets & Hypermarkets
General Stores
Specialty Beauty Stores
Online Retail
Department Stores
Salons
Direct Sales
By Price Range
Value
Mid-range
Premium/Luxury
By Application
Daily Use
Parties & Events
Bridal
Professional Salon
Fashion Styling
By Geography
Asia Pacific
China
Japan
India
South Korea
Australia
South East Asia
Singapore
Taiwan
North America
USA
Canada
Mexico
Europe
Germany
France
UK
Italy
Spain
Russia
Sweden
Denmark
Switzerland
Luxembourg
South America
Brazil
Argentina
Colombia
Peru
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Clips & Pins
5.1.2. Headbands
5.1.3. Hair Ties & Elastics
5.1.4. Scrunchies
5.1.5. Barrettes
5.1.6. Hair Claws
5.1.7. Hair Combs
5.1.8. Wigs & Extensions
5.1.9. Others
5.2. Market Analysis, Insights and Forecast - by End User
5.2.1. Women
5.2.2. Men
5.2.3. Kids & Teenagers
5.2.4. Unisex
5.3. Market Analysis, Insights and Forecast - by Distribution Channel
5.3.1. Supermarkets & Hypermarkets
5.3.2. General Stores
5.3.3. Specialty Beauty Stores
5.3.4. Online Retail
5.3.5. Department Stores
5.3.6. Salons
5.3.7. Direct Sales
5.4. Market Analysis, Insights and Forecast - by Price Range
5.4.1. Value
5.4.2. Mid-range
5.4.3. Premium/Luxury
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Daily Use
5.5.2. Parties & Events
5.5.3. Bridal
5.5.4. Professional Salon
5.5.5. Fashion Styling
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. South America
5.6.5. Middle East & Africa
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Clips & Pins
6.1.2. Headbands
6.1.3. Hair Ties & Elastics
6.1.4. Scrunchies
6.1.5. Barrettes
6.1.6. Hair Claws
6.1.7. Hair Combs
6.1.8. Wigs & Extensions
6.1.9. Others
6.2. Market Analysis, Insights and Forecast - by End User
6.2.1. Women
6.2.2. Men
6.2.3. Kids & Teenagers
6.2.4. Unisex
6.3. Market Analysis, Insights and Forecast - by Distribution Channel
6.3.1. Supermarkets & Hypermarkets
6.3.2. General Stores
6.3.3. Specialty Beauty Stores
6.3.4. Online Retail
6.3.5. Department Stores
6.3.6. Salons
6.3.7. Direct Sales
6.4. Market Analysis, Insights and Forecast - by Price Range
6.4.1. Value
6.4.2. Mid-range
6.4.3. Premium/Luxury
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Daily Use
6.5.2. Parties & Events
6.5.3. Bridal
6.5.4. Professional Salon
6.5.5. Fashion Styling
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Clips & Pins
7.1.2. Headbands
7.1.3. Hair Ties & Elastics
7.1.4. Scrunchies
7.1.5. Barrettes
7.1.6. Hair Claws
7.1.7. Hair Combs
7.1.8. Wigs & Extensions
7.1.9. Others
7.2. Market Analysis, Insights and Forecast - by End User
7.2.1. Women
7.2.2. Men
7.2.3. Kids & Teenagers
7.2.4. Unisex
7.3. Market Analysis, Insights and Forecast - by Distribution Channel
7.3.1. Supermarkets & Hypermarkets
7.3.2. General Stores
7.3.3. Specialty Beauty Stores
7.3.4. Online Retail
7.3.5. Department Stores
7.3.6. Salons
7.3.7. Direct Sales
7.4. Market Analysis, Insights and Forecast - by Price Range
7.4.1. Value
7.4.2. Mid-range
7.4.3. Premium/Luxury
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Daily Use
7.5.2. Parties & Events
7.5.3. Bridal
7.5.4. Professional Salon
7.5.5. Fashion Styling
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Clips & Pins
8.1.2. Headbands
8.1.3. Hair Ties & Elastics
8.1.4. Scrunchies
8.1.5. Barrettes
8.1.6. Hair Claws
8.1.7. Hair Combs
8.1.8. Wigs & Extensions
8.1.9. Others
8.2. Market Analysis, Insights and Forecast - by End User
8.2.1. Women
8.2.2. Men
8.2.3. Kids & Teenagers
8.2.4. Unisex
8.3. Market Analysis, Insights and Forecast - by Distribution Channel
8.3.1. Supermarkets & Hypermarkets
8.3.2. General Stores
8.3.3. Specialty Beauty Stores
8.3.4. Online Retail
8.3.5. Department Stores
8.3.6. Salons
8.3.7. Direct Sales
8.4. Market Analysis, Insights and Forecast - by Price Range
8.4.1. Value
8.4.2. Mid-range
8.4.3. Premium/Luxury
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Daily Use
8.5.2. Parties & Events
8.5.3. Bridal
8.5.4. Professional Salon
8.5.5. Fashion Styling
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Clips & Pins
9.1.2. Headbands
9.1.3. Hair Ties & Elastics
9.1.4. Scrunchies
9.1.5. Barrettes
9.1.6. Hair Claws
9.1.7. Hair Combs
9.1.8. Wigs & Extensions
9.1.9. Others
9.2. Market Analysis, Insights and Forecast - by End User
9.2.1. Women
9.2.2. Men
9.2.3. Kids & Teenagers
9.2.4. Unisex
9.3. Market Analysis, Insights and Forecast - by Distribution Channel
9.3.1. Supermarkets & Hypermarkets
9.3.2. General Stores
9.3.3. Specialty Beauty Stores
9.3.4. Online Retail
9.3.5. Department Stores
9.3.6. Salons
9.3.7. Direct Sales
9.4. Market Analysis, Insights and Forecast - by Price Range
9.4.1. Value
9.4.2. Mid-range
9.4.3. Premium/Luxury
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Daily Use
9.5.2. Parties & Events
9.5.3. Bridal
9.5.4. Professional Salon
9.5.5. Fashion Styling
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Clips & Pins
10.1.2. Headbands
10.1.3. Hair Ties & Elastics
10.1.4. Scrunchies
10.1.5. Barrettes
10.1.6. Hair Claws
10.1.7. Hair Combs
10.1.8. Wigs & Extensions
10.1.9. Others
10.2. Market Analysis, Insights and Forecast - by End User
10.2.1. Women
10.2.2. Men
10.2.3. Kids & Teenagers
10.2.4. Unisex
10.3. Market Analysis, Insights and Forecast - by Distribution Channel
10.3.1. Supermarkets & Hypermarkets
10.3.2. General Stores
10.3.3. Specialty Beauty Stores
10.3.4. Online Retail
10.3.5. Department Stores
10.3.6. Salons
10.3.7. Direct Sales
10.4. Market Analysis, Insights and Forecast - by Price Range
10.4.1. Value
10.4.2. Mid-range
10.4.3. Premium/Luxury
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Daily Use
10.5.2. Parties & Events
10.5.3. Bridal
10.5.4. Professional Salon
10.5.5. Fashion Styling
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Goody
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Scünci
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Kitsch
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. KOOSHOO
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Hair Accessories Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Hair Accessories Market Revenue (Billion), by Product 2026 & 2034
Figure 3: Asia Pacific Hair Accessories Market Revenue Share (%), by Product 2026 & 2034
Figure 4: Asia Pacific Hair Accessories Market Revenue (Billion), by End User 2026 & 2034
Figure 5: Asia Pacific Hair Accessories Market Revenue Share (%), by End User 2026 & 2034
Figure 6: Asia Pacific Hair Accessories Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 7: Asia Pacific Hair Accessories Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 8: Asia Pacific Hair Accessories Market Revenue (Billion), by Price Range 2026 & 2034
Figure 9: Asia Pacific Hair Accessories Market Revenue Share (%), by Price Range 2026 & 2034
Figure 10: Asia Pacific Hair Accessories Market Revenue (Billion), by Application 2026 & 2034
Figure 11: Asia Pacific Hair Accessories Market Revenue Share (%), by Application 2026 & 2034
Figure 12: Asia Pacific Hair Accessories Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Asia Pacific Hair Accessories Market Revenue Share (%), by Country 2026 & 2034
Figure 14: North America Hair Accessories Market Revenue (Billion), by Product 2026 & 2034
Figure 15: North America Hair Accessories Market Revenue Share (%), by Product 2026 & 2034
Figure 16: North America Hair Accessories Market Revenue (Billion), by End User 2026 & 2034
Table 6: Hair Accessories Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: Asia Pacific Hair Accessories Market Revenue Billion Forecast, by Product 2020 & 2034
Table 8: Asia Pacific Hair Accessories Market Revenue Billion Forecast, by End User 2020 & 2034
Table 9: Asia Pacific Hair Accessories Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 10: Asia Pacific Hair Accessories Market Revenue Billion Forecast, by Price Range 2020 & 2034
Table 11: Asia Pacific Hair Accessories Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: Asia Pacific Hair Accessories Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: China Hair Accessories Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Japan Hair Accessories Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: India Hair Accessories Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: South Korea Hair Accessories Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the Hair Accessories Market size in 2025?
The global Hair Accessories Market was valued at USD 25.2 Billion in 2025 and is projected to reach USD 46.6 Billion by 2033, growing at an 8.0% CAGR through the forecast period.
2. Which region leads the Hair Accessories Market?
Asia Pacific led with 39.8% of 2025 revenue, with China the largest country market. India and South East Asia are the fastest-growing sub-regions at 9.0% and 8.6% CAGRs respectively.
3. What is the fastest-growing Hair Accessories segment?
Premium, sustainable, and culturally specific accessories grow fastest by value. Wigs and extensions lead by average selling price, while commodity elastics dominate unit volume but face margin compression.
4. Who are the leading Hair Accessories companies?
The market is highly fragmented. Goody and Scünci anchor mass shelves, Kitsch leads DTC design, and KOOSHOO anchors sustainability. No single player holds double-digit global share.
5. What is driving Hair Accessories Market growth?
Social-media-driven styling discovery, rising grooming spend, personalization, and sustainability preferences drive growth. Influencer trust converts trends into purchases faster than traditional advertising, especially among Gen Z.
6. What restrains Hair Accessories Market growth?
Low differentiation, price competition, short trend cycles, and anti-fast-fashion sentiment cap pricing power and create markdown risk, especially in commodity elastics and value-tier channels.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers (textiles, elastics, resins), specialized accessory producers, contract manufacturers, and global distributors. Decision-makers interviewed included VPs of Sourcing, Heads of Design & R&D, Technical Directors, and Commercial Operations Leads.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VPs of Sourcing & Procurement
35%
Heads of Design & R&D
30%
Technical & Quality Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Textile Suppliers
40%
Specialized Accessory Producers
30%
Global Distributors & Wholesalers
20%
Retail & E-commerce Operators
10%
Secondary Benchmarking & Public Trade Validation
We triangulate against UN Comtrade (HS chapters for hair articles and textile accessories), WTO tariff schedules, US ITC trade data, Eurostat production statistics, corporate 10-K filings from listed beauty and apparel groups, patent databases for clip and claw mechanism innovation, and industry associations including the Personal Care Products Council and relevant national textile and apparel councils.
Demand Modeling & Market Sizing Triangulation
We apply simultaneous top-down (macroeconomic grooming-spend allocation and retail channel data) and bottom-up (manufacturer capacity, ASP, and end-use consumption) modeling. Results are reconciled through a weighted validation matrix that prioritizes estimates converging within ±3%.


 Hair Accessories Market