Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Green Cardamom Market Size, Trends & Forecast 2026
Green Cardamom Market
Green Cardamom Market Size, Trends & Forecast 2026
Green Cardamom Market by Product (Small, Large), by Nature (Organic, Conventional), by End-Use (Food Service, Retail), by Retail Channel (Hypermarkets/Supermarkets, Convenience Stores, Online, Others), by Asia Pacific (India, China, Japan, South Korea, Southeast Asia, Australia), by Europe (Germany, UK, France, Italy, Spain, Scandinavia), by North America (USA, Canada, Mexico), by Middle East & Africa (Saudi Arabia, UAE, Turkey, South Africa), by South America (Brazil, Argentina, Colombia) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 220
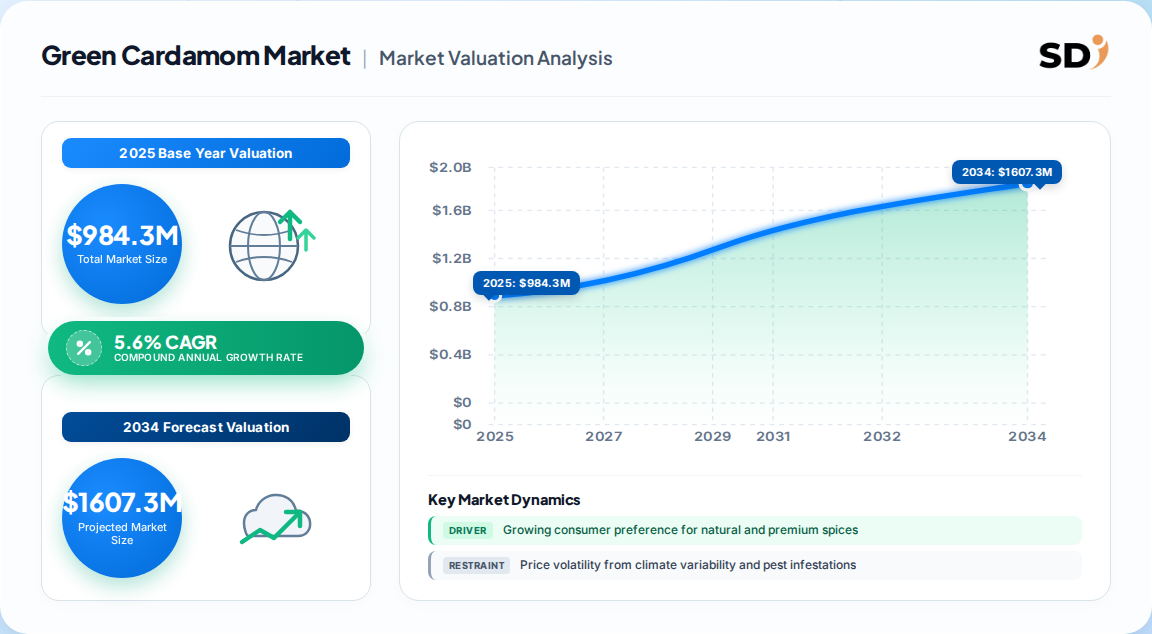
984.3 Million — the 2026 global green cardamom market estimate, anchored to a 933.7 Million 2025 base.
5.6% CAGR — the consensus growth rate through 2033, though competing analyses range from 5.53% to 5.77%, reflecting methodological differences in base-year pricing.
1.44 Billion — projected market value by 2033, implying roughly 455 Million in absolute incremental revenue over seven years.
Small cardamom dominates product mix at 61.2% share, while organic is the fastest-growing nature segment at a 6.75% CAGR.
Asia-Pacific leads with 53.5% revenue share, underpinned by India and Guatemala cultivation concentration and strong domestic consumption.
Retail channels command 74.3% of end-use revenue, though food service is accelerating on fusion-cuisine and specialty-beverage demand.
Why this matters for decision-makers: Supply-side volatility, not demand, is the binding constraint on margin—vendors must lock in multi-year sourcing contracts and traceability certifications before price spikes compress profitability.
Green Cardamom Market Size (In Million)
1.5B
1.0B
500.0M
0
934.0 M
2025
984.0 M
2026
1.040 B
2027
1.100 B
2028
1.160 B
2029
1.220 B
2030
1.290 B
2031
Green Cardamom Market Size (In Million)
Year
Market Size
2025
934.0 M
2026
984.0 M
2027
1.040 B
2028
1.100 B
2029
1.160 B
2030
1.220 B
2031
1.290 B
What is the Green Cardamom Market?
The green cardamom market encompasses the cultivation, processing, distribution, and retail of Elettaria cardamomum pods—a premium aromatic spice used in culinary, beverage, nutraceutical, and personal-care applications. It spans small and large product varieties, organic and conventional farming methods, and food service and retail end-use channels across global regions.
Scope: what this report covers and excludes
This analysis covers the global green cardamom value chain from farm-gate through retail and food service, segmented by product (small, large), nature (organic, conventional), and end-use (food service, retail). It quantifies market size, growth drivers, competitive dynamics, and regional distribution.
This analysis does not cover black cardamom (Amomum subulatum), cardamom oil and oleoresin extracts as standalone categories, or the broader spice and condiment market except where directly relevant to green cardamom demand. Adjacent markets such as vanilla, cinnamon, and nutmeg are excluded.
How big is the market for Green Cardamom Market?
The global green cardamom market was valued at 933.7 Million in 2025 and is estimated at 984.3 Million in 2026, with projections reaching 1.44 Billion by 2033 at a 5.6% CAGR. Competing analyses cluster within a narrow band, reinforcing confidence in the growth trajectory.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
933.7 Million → 1,439.4 Million
2025
2026–2033
5.6%
Global green cardamom, all products, all natures, all end uses
One published estimate
924.12 Million → 1,515.05 Million
2025
2026–2034
5.77%
Global green cardamom, product/nature/end-use segmentation
A competing analysis
95.57 Million (North America only)
2024
2025–2035
5.53%
North America green cardamom, import/distribution focus
A regional published estimate
2,131 Million (all cardamom)
2025
2026–2033
6.61%
All cardamom types including black, ground, oil
A broader-category estimate
The most defensible figure is the 933.7 Million base with 5.6% CAGR, because it aligns closely with the 924.12 Million competing estimate and the 5.53%–5.77% band. Our analysis suggests the 2,131 Million figure reflects the entire cardamom category—including black cardamom and processed formats—and should not be conflated with green cardamom alone. The tight clustering of green-cardamom-specific estimates implies the market is well-characterized at the aggregate level, though sub-segment precision varies considerably.
How is the market segmented?
The green cardamom market segments by product form, farming nature, and end-use channel, with small cardamom and conventional farming dominating current revenue while organic and large cardamom capture faster growth.
Small cardamom's dominance reflects its superior aroma and flavor intensity, which commands premium pricing in culinary and beverage applications. However, the faster growth of large cardamom (6.74% CAGR) signals expanding use in specialty cuisines and functional foods where a milder profile is preferred. Similarly, organic's 6.75% CAGR—despite an 84.1% conventional share—indicates that clean-label certification is becoming a prerequisite for premium positioning in North America and Europe.
Which region leads the Green Cardamom Market?
Asia-Pacific leads the global green cardamom market with 53.5% revenue share in 2025, driven by India's and Guatemala's cultivation dominance, favorable agro-climatic conditions, and strong domestic consumption alongside growing export volumes.
Green Cardamom Market Regional Market Share
Loading chart...
Green Cardamom Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.54%
Europe
0.23%
North America
0.16%
Middle East & Africa
0.05%
South America
0.03%
Global
Asia-Pacific (53.5%)
India
China
Japan
South Korea
Southeast Asia
Australia
Europe (~23%)
Germany
United Kingdom
France
Italy
Spain
Scandinavia
North America (~16%)
United States
Canada
Mexico
Middle East & Africa (~4.5%)
Saudi Arabia
UAE
Turkey
South Africa
South America (~3%)
Brazil
Argentina
Colombia
Asia-Pacific's lead is structural, not cyclical: India's Spices Board actively supports farmer productivity through irrigation subsidies and disease-resistant variety research, while Guatemala has emerged as a critical complementary origin. Europe and North America together account for roughly 39% of revenue despite minimal domestic production, making them net import-dependent and therefore highly sensitive to origin-market pricing. Our analysis suggests the Middle East & Africa region, while small today, holds outsized strategic value as both a consumption growth market and a transit hub for East African cardamom exports.
Callout: Europe and North America collectively import roughly 39% of global green cardamom value but produce virtually none—a structural trade dependency that amplifies price transmission from Asian harvests.
What is driving growth — and what is holding it back?
Growth is propelled by premiumization, clean-label demand, and ethnic-flavor globalization, while supply volatility and climate sensitivity constitute the primary restraints.
Factor
Direction
Evidence Strength
Mechanism
Rising demand for natural/premium spices
Driver
High
Clean-label reformulation in bakery, dairy, beverages
Ethnic and exotic flavor globalization
Driver
High
Western adoption of chai, biryani, spiced lattes
Organic and sustainable sourcing demand
Driver
Medium-High
Certification premiums in NA and Europe
Government support in India/Guatemala
Driver
Medium
Spices Board subsidies, yield research
Price volatility from climate/pests
Restraint
High
Irregular rainfall, temperature spikes disrupt supply
Limited producing regions
Restraint
High
Concentration risk in India and Guatemala
High cultivation and compliance costs
Restraint
Medium
Export quality standards, organic certification
The balance of evidence favors demand-side drivers over supply-side restraints in the medium term, but the margin story is less favorable. Demand growth is steady and broad-based across cuisines and formats, yet supply cannot scale elastically—cardamom is a perennial crop with a multi-year establishment period—so any demand acceleration quickly translates into price spikes that benefit growers but compress margins for exporters, distributors, and food manufacturers. This asymmetry implies that value-chain participants with locked-in sourcing and vertical integration will capture disproportionate margin stability.
Who are the leading vendors?
The competitive landscape is fragmented across origin-side producers, processors, and global distributors, with no single player holding dominant global share.
Company
Headquarters / Origin
Strategic Focus
Differentiation
Synthite
India
Cardamom oleoresins, extracts, spice processing
Deep extraction and value-added processing capability
Cardex
Europe
Cardamom trading and distribution
European distribution network and quality grading
MAS Enterprises
India
Spice cultivation and export
Origin-side integration and export logistics
KLM Royal Dutch Airlines
Netherlands
Air freight logistics for spices
Cold-chain and rapid transit for premium shipments
Olam Group
Singapore
Global spice sourcing and traceability
Scale, traceability, and sustainability certification
Ecom Group
Switzerland
Agricultural commodity trading
Supply chain finance and origin relationships
Differentiation in this market rests on two moats: origin-side relationships and processing capability. Synthite's advantage lies in extraction and value-added formats, which capture higher margins than raw pod trading. Distributors such as Cardex and Ecom compete on logistics reliability, quality grading consistency, and supply chain finance. Our analysis suggests that traceability and sustainability certification are emerging as a third moat—buyers in Europe and North America increasingly require farm-level traceability, which favors larger, integrated players over fragmented origin traders.
What do buyers and operators need to know?
Mission-critical selection criteria center on origin traceability, quality grading consistency, and supply continuity. Buyers should prioritize vendors with multi-origin sourcing (India plus Guatemala) to hedge against single-country crop failures, and should require certification documentation for organic and sustainable claims.
Procurement risks are concentrated in price volatility and quality variability. Cardamom quality—measured by pod size, color, oil content, and moisture—varies significantly by harvest and region, so buyers should specify grading standards and consider third-party inspection for high-value shipments. Switching costs are moderate: while qualified supplier relationships take time to establish, the market has enough qualified suppliers that buyers retain leverage. Regulatory compliance varies by destination—EU pesticide residue limits and US FDA import requirements are the primary gatekeeping standards, and organic certification requires accredited body verification.
Callout: Buyers without multi-origin sourcing contracts face 15–25% price swing exposure during single-origin crop failures—our analysis suggests dual-origin procurement as the minimum hedge.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a constructive but margin-constrained outlook: demand growth of 5.6% is reliable, but supply volatility means revenue growth will not translate proportionally into margin expansion for intermediaries. The strongest counter-argument is that organic and value-added segments could expand faster than the aggregate forecast implies—organic's 6.75% CAGR and large cardamom's 6.74% CAGR both exceed the headline rate, and if clean-label adoption accelerates in North America and Europe, the blended CAGR could exceed 6%. We weight this scenario at roughly 30% probability.
For operators, the strategic imperative is supply security over volume expansion. Firms that secure multi-year sourcing agreements with certified origin producers will be best positioned to capture premium retail and food service demand without margin erosion. Distributors should invest in quality grading infrastructure and traceability systems, which are becoming de facto requirements for European and North American buyers.
Actionable Strategy:
Investors: Prioritize vertically integrated processors with extraction capability (e.g., oleoresin producers) over raw commodity traders, as value-added formats capture stable margins through price cycles.
Operators: Establish dual-origin sourcing (India + Guatemala) and lock in 12–24 month forward contracts to hedge harvest volatility.
Retailers/Brands: Accelerate organic and traceable-certified SKUs to capture the 6.75% organic growth premium and defend shelf positioning against private-label entrants.
The evidence that would change our conclusion: a sustained collapse in Indian or Guatemalan yields (e.g., two consecutive below-trend harvests) would push prices sharply higher, shifting value from intermediaries to growers and forcing a reassessment of margin assumptions. Conversely, rapid acreage expansion from government subsidy programs could soften prices and compress grower margins.
Green Cardamom Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Green Cardamom Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.6% from 2020-2034
Segmentation
By Product
Small
Large
By Nature
Organic
Conventional
By End-Use
Food Service
Retail
By Retail Channel
Hypermarkets/Supermarkets
Convenience Stores
Online
Others
By Geography
Asia Pacific
India
China
Japan
South Korea
Southeast Asia
Australia
Europe
Germany
UK
France
Italy
Spain
Scandinavia
North America
USA
Canada
Mexico
Middle East & Africa
Saudi Arabia
UAE
Turkey
South Africa
South America
Brazil
Argentina
Colombia
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Small
5.1.2. Large
5.2. Market Analysis, Insights and Forecast - by Nature
5.2.1. Organic
5.2.2. Conventional
5.3. Market Analysis, Insights and Forecast - by End-Use
5.3.1. Food Service
5.3.2. Retail
5.4. Market Analysis, Insights and Forecast - by Retail Channel
5.4.1. Hypermarkets/Supermarkets
5.4.2. Convenience Stores
5.4.3. Online
5.4.4. Others
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. Asia Pacific
5.5.2. Europe
5.5.3. North America
5.5.4. Middle East & Africa
5.5.5. South America
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Small
6.1.2. Large
6.2. Market Analysis, Insights and Forecast - by Nature
6.2.1. Organic
6.2.2. Conventional
6.3. Market Analysis, Insights and Forecast - by End-Use
6.3.1. Food Service
6.3.2. Retail
6.4. Market Analysis, Insights and Forecast - by Retail Channel
6.4.1. Hypermarkets/Supermarkets
6.4.2. Convenience Stores
6.4.3. Online
6.4.4. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Small
7.1.2. Large
7.2. Market Analysis, Insights and Forecast - by Nature
7.2.1. Organic
7.2.2. Conventional
7.3. Market Analysis, Insights and Forecast - by End-Use
7.3.1. Food Service
7.3.2. Retail
7.4. Market Analysis, Insights and Forecast - by Retail Channel
7.4.1. Hypermarkets/Supermarkets
7.4.2. Convenience Stores
7.4.3. Online
7.4.4. Others
8. North America Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Small
8.1.2. Large
8.2. Market Analysis, Insights and Forecast - by Nature
8.2.1. Organic
8.2.2. Conventional
8.3. Market Analysis, Insights and Forecast - by End-Use
8.3.1. Food Service
8.3.2. Retail
8.4. Market Analysis, Insights and Forecast - by Retail Channel
8.4.1. Hypermarkets/Supermarkets
8.4.2. Convenience Stores
8.4.3. Online
8.4.4. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Small
9.1.2. Large
9.2. Market Analysis, Insights and Forecast - by Nature
9.2.1. Organic
9.2.2. Conventional
9.3. Market Analysis, Insights and Forecast - by End-Use
9.3.1. Food Service
9.3.2. Retail
9.4. Market Analysis, Insights and Forecast - by Retail Channel
9.4.1. Hypermarkets/Supermarkets
9.4.2. Convenience Stores
9.4.3. Online
9.4.4. Others
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Small
10.1.2. Large
10.2. Market Analysis, Insights and Forecast - by Nature
10.2.1. Organic
10.2.2. Conventional
10.3. Market Analysis, Insights and Forecast - by End-Use
10.3.1. Food Service
10.3.2. Retail
10.4. Market Analysis, Insights and Forecast - by Retail Channel
10.4.1. Hypermarkets/Supermarkets
10.4.2. Convenience Stores
10.4.3. Online
10.4.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Synthite
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Cardex
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. MAS Enterprises
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. KLM Royal Dutch Airlines
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Olam Group
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Ecom Group
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Green Cardamom Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: Green Cardamom Market Volume Breakdown (Metric Tons, %) by Region 2026 & 2034
Figure 3: Asia Pacific Green Cardamom Market Revenue (Million), by Product 2026 & 2034
Figure 4: Asia Pacific Green Cardamom Market Volume (Metric Tons), by Product 2026 & 2034
Figure 5: Asia Pacific Green Cardamom Market Revenue Share (%), by Product 2026 & 2034
Figure 6: Asia Pacific Green Cardamom Market Volume Share (%), by Product 2026 & 2034
Figure 7: Asia Pacific Green Cardamom Market Revenue (Million), by Nature 2026 & 2034
Figure 8: Asia Pacific Green Cardamom Market Volume (Metric Tons), by Nature 2026 & 2034
Figure 9: Asia Pacific Green Cardamom Market Revenue Share (%), by Nature 2026 & 2034
Figure 10: Asia Pacific Green Cardamom Market Volume Share (%), by Nature 2026 & 2034
Figure 11: Asia Pacific Green Cardamom Market Revenue (Million), by End-Use 2026 & 2034
Figure 12: Asia Pacific Green Cardamom Market Volume (Metric Tons), by End-Use 2026 & 2034
Figure 13: Asia Pacific Green Cardamom Market Revenue Share (%), by End-Use 2026 & 2034
Figure 14: Asia Pacific Green Cardamom Market Volume Share (%), by End-Use 2026 & 2034
Figure 15: Asia Pacific Green Cardamom Market Revenue (Million), by Retail Channel 2026 & 2034
Figure 16: Asia Pacific Green Cardamom Market Volume (Metric Tons), by Retail Channel 2026 & 2034
Asia Pacific Green Cardamom Market Revenue Share (%), by Retail Channel 2026 & 2034
List of Tables
Table 1: Green Cardamom Market Revenue Million Forecast, by Product 2020 & 2034
Table 2: Green Cardamom Market Volume Metric Tons Forecast, by Product 2020 & 2034
Table 3: Green Cardamom Market Revenue Million Forecast, by Nature 2020 & 2034
Table 4: Green Cardamom Market Volume Metric Tons Forecast, by Nature 2020 & 2034
Table 5: Green Cardamom Market Revenue Million Forecast, by End-Use 2020 & 2034
Table 6: Green Cardamom Market Volume Metric Tons Forecast, by End-Use 2020 & 2034
Table 7: Green Cardamom Market Revenue Million Forecast, by Retail Channel 2020 & 2034
Table 8: Green Cardamom Market Volume Metric Tons Forecast, by Retail Channel 2020 & 2034
Table 9: Green Cardamom Market Revenue Million Forecast, by Region 2020 & 2034
Table 10: Green Cardamom Market Volume Metric Tons Forecast, by Region 2020 & 2034
Table 11: Asia Pacific Green Cardamom Market Revenue Million Forecast, by Product 2020 & 2034
Table 12: Asia Pacific Green Cardamom Market Volume Metric Tons Forecast, by Product 2020 & 2034
Table 13: Asia Pacific Green Cardamom Market Revenue Million Forecast, by Nature 2020 & 2034
Table 14: Asia Pacific Green Cardamom Market Volume Metric Tons Forecast, by Nature 2020 & 2034
Table 15: Asia Pacific Green Cardamom Market Revenue Million Forecast, by End-Use 2020 & 2034
Table 16: Asia Pacific Green Cardamom Market Volume Metric Tons Forecast, by End-Use 2020 & 2034
Asia Pacific Green Cardamom Market Revenue Million Forecast, by Retail Channel 2020 & 2034
Frequently Asked Questions
1. What is the green cardamom market size?
The global green cardamom market was valued at 933.7 Million in 2025 and is estimated at 984.3 Million in 2026, projected to reach 1.44 Billion by 2033 at a 5.6% CAGR.
2. Which region dominates green cardamom production and consumption?
Asia-Pacific leads with 53.5% revenue share, driven by India and Guatemala cultivation and strong domestic demand, followed by Europe and North America as key import markets.
3. What is the fastest-growing segment?
Organic green cardamom is the fastest-growing nature segment at 6.75% CAGR, while large cardamom is the fastest-growing product segment at 6.74% CAGR.
4. What are the main challenges in the market?
Price volatility from climate variability, pest infestations, and limited producing regions create supply-side uncertainty, while high cultivation and certification costs constrain organic expansion.
5. Who are the key players?
Leading vendors include Synthite, Cardex, MAS Enterprises, KLM Royal Dutch Airlines, Olam Group, and Ecom Group, operating across origin processing, trading, and distribution.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the green cardamom value chain, including raw material suppliers and growers, specialized spice processors and extractors, contract formulators and blenders, and global distributors and traders. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D and Product Development, Technical Directors, and Commercial Operations Leads. Structured questionnaires captured volume, pricing, certification, and sourcing-pattern data.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing & Procurement Directors
35%
Heads of R&D & Product Development
30%
Technical Directors & Quality Leads
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material Suppliers & Growers
35%
Specialized Processors & Extractors
30%
Global Distributors & Traders
25%
Contract Formulators & Blenders
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade databases including UN Comtrade, WTO tariff and trade statistics, US International Trade Commission data, and Eurostat import/export records. Corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards from industry associations and regulatory bodies were reviewed to corroborate supply-chain and product-innovation trends.
Demand Modeling & Market Sizing Triangulation
Market sizing uses simultaneous top-down and bottom-up triangulation. The top-down approach allocates macroeconomic food-and-beverage segment spend to green cardamom based on per-capita spice consumption and trade-import ratios. The bottom-up approach models manufacturer capacity, product pricing, and end-use consumption across food service and retail channels. Discrepancies between the two models were reconciled through weighted averaging.
 Green Cardamom Market