 Metal Cans Market
 Size, Share & Forecast to 2033
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 186
Shweta Thorat
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Metal Cans Market
Shweta Thorat
Research Associate

| Year | Market Size |
|---|---|
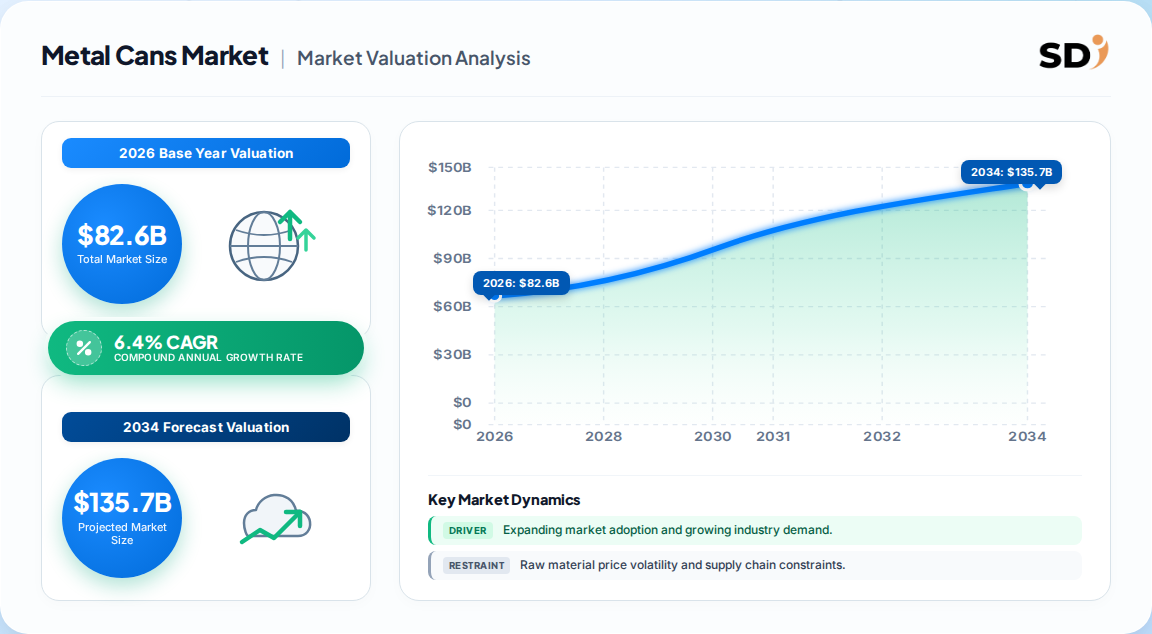
| 2025 | 77.80 B |
| 2026 | 82.60 B |
| 2027 | 87.90 B |
| 2028 | 93.50 B |
| 2029 | 99.50 B |
| 2030 | 105.9 B |
| 2031 | 112.7 B |

The metal cans market encompasses rigid packaging containers manufactured primarily from aluminum and steel for food, beverages, and industrial products. These cans provide barrier protection, shelf stability, and recyclability, and are produced in two-piece and three-piece formats with easy-open or peelable closures for retail and foodservice channels.
This analysis covers the global metal cans market across aluminum and steel materials, two-piece D&I, two-piece DRD, and three-piece products, EOE and POE closure types, and food and beverage applications. This analysis does not cover metal closures and caps as standalone products, aerosol cans, metal drums and pails, or foil-based flexible packaging.
The metal cans market is estimated at 82.6 Billion in 2026, with published estimates converging on a 6.0–7.1% CAGR range depending on whether the scope is all-metal cans, aluminum cans only, or food and beverage cans specifically.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 77.8 Billion | 2025 | 2033 | 6.4% | All metal cans (aluminum + steel), food and beverage | One published estimate |
| 53.7 Billion | 2025 | 2035 | 5.0% | Aluminum cans only, beverage-weighted | A competing analysis |
| 47.7 Billion | 2024 | 2034 | 7.1% | Food and beverage metal cans, all materials | A competing analysis |
| 27.6 Billion | 2026 | 2031 | 1.5% (historical) | US metal can and container manufacturing revenue | IBISWorld (US industry data) |
Our analysis suggests the 77.8 Billion (2025) all-metal-cans figure is the most defensible anchor for total-market sizing because it captures both aluminum beverage cans and steel food cans. The aluminum-only estimate of 53.7 Billion in 2025 implies aluminum represents roughly 69% of total metal cans value, which sits close to the 67–75% share range reported across sources. The food and beverage-only estimate (47.7 Billion in 2024) is narrower in scope and excludes industrial and aerosol segments, explaining its lower base. The IBISWorld US figure is a manufacturing revenue measure, not a global market value, and should not be compared directly.
Segmentation is anchored on material, product format, closure type, and application, with aluminum and two-piece D&I formats dominating value because they serve high-volume beverage lines.
| Parent Segment | Children | 2025 Share |
|---|---|---|
| By Material | Aluminum, Steel | Aluminum 74.5% |
| By Product | 2-Piece D&I, 2-Piece DRD, 3-Piece | 2-Piece D&I 70.4% |
| By Closure Type | Easy-Open End (EOE), Peel-Off End (POE) | EOE 78.6% |
| By Application | Food, Beverages | Beverages 77.2% |
Aluminum's dominance is structural: it is lighter, corrosion-resistant, and near-infinitely recyclable, making it the default for carbonated soft drinks, beer, and energy drinks. Steel retains a defensible position in food cans because its rigidity withstands heat sterilization and its magnetic properties aid sorting in recycling streams.
North America leads the global metal cans market with 32.1% revenue share in 2025, followed by Asia Pacific, which is the fastest-growing region and is projected to gain share through 2033 on urbanization and packaged beverage demand.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.23% |
| Asia-Pacific | 0.33% |
| South America | 0.06% |
| Middle East & Africa | 0.06% |
The North America lead reflects mature beverage canning infrastructure and high per-capita canned beverage consumption. Asia Pacific's faster CAGR is driven by urbanization concentrating consumers around formal retail and cold-chain networks, plus capacity additions in India and Southeast Asia. Our analysis suggests the more important regional signal is capacity localization: can makers that pair new lines with local recycling collection avoid exposure to primary aluminum and electricity cycles.
Growth is driven by beverage volume stability, recyclability credentials, lightweighting economics, and urbanization; restraint comes from volatile aluminum and steel costs, tariff exposure, and regulatory re-specification costs for can coatings.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Carbonated soft drinks and beer demand | Driver | High | Pressure-resistant, light-protective cans protect high-volume beverage utilization |
| Recyclability preference | Driver | High | Aluminum recyclability narrative influences brand and retailer packaging decisions |
| High recycling efficiency | Driver | Medium | Secondary aluminum uses substantially less energy, reducing input cost exposure |
| Lightweighting | Driver | Medium | Lower container weight improves payload efficiency in long-haul beverage distribution |
| Urbanization | Driver | High | Concentrates consumers around retail and refrigeration, expanding packaged occasions |
| Metal price volatility and tariffs | Restraint | High | 25–50% US levies raise can-maker costs and can push brands toward plastic alternatives |
| BPA coating ban (EU) | Restraint | High | Requires re-qualification of can linings and reformulation timelines through 2028 |
The balance favors growth, but the composition of growth is shifting from volume to mix. Standard carbonated soft drink and beer volumes protect line utilization; energy, functional, and premium ready-to-drink products drive demand for sleek, slim, and large formats that carry higher decoration and changeover complexity. The BPA ban is the most under-priced restraint: EU Regulation 2024/3190 bans BPA in food contact materials from 20 January 2025, with transitional relief for single-use coated articles for fruit, vegetables, and processed fish until 20 July 2028. Suppliers with validated BPA-free epoxy or alternative linings gain a compliance-driven advantage.
The metal cans market is moderately concentrated, with the top five aluminum can makers holding 58.5% of that segment in 2025 and Ball Corporation leading at 16.7% share.
| Company | Segment Focus | Notable Strength |
|---|---|---|
| Ball Corporation | Aluminum beverage cans | Broad standard, sleek, slim, and large-format portfolio; global line footprint |
| Crown Holdings | Beverage and food cans | Aerosol and specialty can capability; broad geographic coverage |
| Silgan Containers | Steel food cans | North American food can leadership and long-tenured retail relationships |
| Canpack | Aluminum and steel cans | European and emerging-market capacity depth |
| CCL Industries | Decorated cans and labels | Premium decoration and digital printing capability |
Differentiation rests on line efficiency across format proliferation, recycled-content access, and coating compliance. Ball's multi-format portfolio lets brands run mainstream and premium SKUs on a common platform, while Silgan's steel food can position is defended by sterilization compatibility. The 1995 EU merger decision in Crown Cork & Seal/CarnaudMetalbox, which required divestiture of five tinplate aerosol plants representing about 22% of the EEA market, remains a reminder that aerosol and food can sub-segments carry distinct competition dynamics from beverage cans.
Buyers should prioritize suppliers that can document recycled-content specifications, validated BPA-free linings, and multi-format line flexibility. Procurement risk is concentrated in metal cost pass-through: aluminum and steel price swings, amplified by tariffs, can move can costs faster than retail price adjustments, compressing margins for small brands. Switching costs are high because can format changes require filling-line changeover, seamer adjustment, and re-qualification, so multi-year supply agreements with indexed metal pricing are common. Regulatory compliance is the sharpest selection criterion in Europe: the BPA ban affects epoxy linings on metal food and drink cans, and buyers must verify that transitional stocks are exhausted before the 2026–2028 deadlines. Operators should also evaluate collection and recycling infrastructure in faster-growing markets, because capacity without secondary-metal access remains exposed to primary aluminum cycles.
The balance of evidence favors sustained expansion at a mid-single-digit to low-double-digit CAGR, with the all-metal-cans estimate of 77.8 Billion in 2025 growing to 127.8 Billion by 2033 as the most defensible planning base. The strongest counter-argument is that tariff-driven cost inflation and plastic substitution could cap volume growth in price-sensitive food categories, particularly in the US where canned food producers face 9–15% price increases. We judge this a margin and mix risk rather than a demand-destroying risk, because beverage formats remain structurally tied to aluminum for pressure and light protection.
Our analysis suggests the second-order effect most buyers miss is the coating transition. The EU BPA ban forces re-qualification of can linings on a fixed timeline, which temporarily raises conversion costs but also resets supplier selection in favor of vendors with validated alternatives. Combined with recycled-content targets such as the Can Manufacturers Institute's 70% US aluminum beverage-can recycling goal by 2030, procurement is shifting from price-only to compliance-and-circularity scoring.
What would change this conclusion: a sharper-than-expected collapse in beverage volumes, or a US-EU regulatory divergence that delays BPA alternatives beyond 2028, would compress the forecast toward the lower end of the 5.0–7.1% CAGR range.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
The global metal cans market was valued at 77.8 Billion in 2025 and is estimated at 82.6 Billion in 2026. It is projected to reach 127.8 Billion by 2033, growing at a 6.4% CAGR over the forecast period.
Aluminum dominates with 74.5% revenue share in 2025, driven by its light weight, corrosion resistance, and near-infinite recyclability. Steel retains strong demand in food cans where rigidity and heat sterilization resistance are essential.
North America led with 32.1% revenue share in 2025, supported by mature beverage canning infrastructure. Asia Pacific is the fastest-growing region, driven by urbanization and expanding packaged beverage consumption.
EU Regulation 2024/3190 bans BPA in food contact materials from 20 January 2025, including epoxy can linings. Transitional relief extends to 20 July 2026 for most articles and 20 July 2028 for single-use coated fruit, vegetable, and fish packaging.
Ball Corporation leads aluminum beverage cans with 16.7% share in 2025. The top five players, including Crown Holdings, Silgan Containers, Canpack, and CCL Industries, collectively hold 58.5% of that segment.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research is built on a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the value chain, including aluminum and steel suppliers, specialized can producers, coating and lining formulators, and global distributors. Interviewees spanned VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, formulation, and commercialization decisions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement Directors | 35% |
| Heads of R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Aluminum & Steel Suppliers | 30% |
| Specialized Can Producers | 40% |
| Coating & Lining Formulators | 20% |
| Global Distributors | 10% |
We validated findings against official multilateral trade and standards databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and 10-K submissions, patent databases, and recognized non-profit technical standards and industry associations. Regulatory timelines, including EU food contact material rules, were cross-checked against official EU sources.
We applied simultaneous Top-Down macro-economic and industry segment allocation and Bottom-Up manufacturer capacity, product pricing, and end-use consumption modeling. This triangulation reconciles divergent published estimates and isolates the definitional differences driving scope gaps.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |