Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Stickers by Application (Individual, Food & Beverages, Health and Beauty, Chemical, Others), by Types (Die Cut Stickers, Kiss Cut Stickers), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Aug 27, 2026|Base Year : 2025|Pages : 122
The Die Cut Stickers Market is the primary revenue engine, capturing a majority share of the global Stickers Market in 2024. Consumer product brands continue to shift from plain labels to custom die cut formats for packaging differentiation, lifting average order values. E-commerce expansion, direct-to-consumer unboxing experiences, and short-run promotional sticker campaigns are the three macro catalysts reinforcing demand. At the same time, health and beauty brands are adopting premium kiss cut formats, though the Kiss Cut Stickers Market grows from a smaller base and carries higher unit costs.
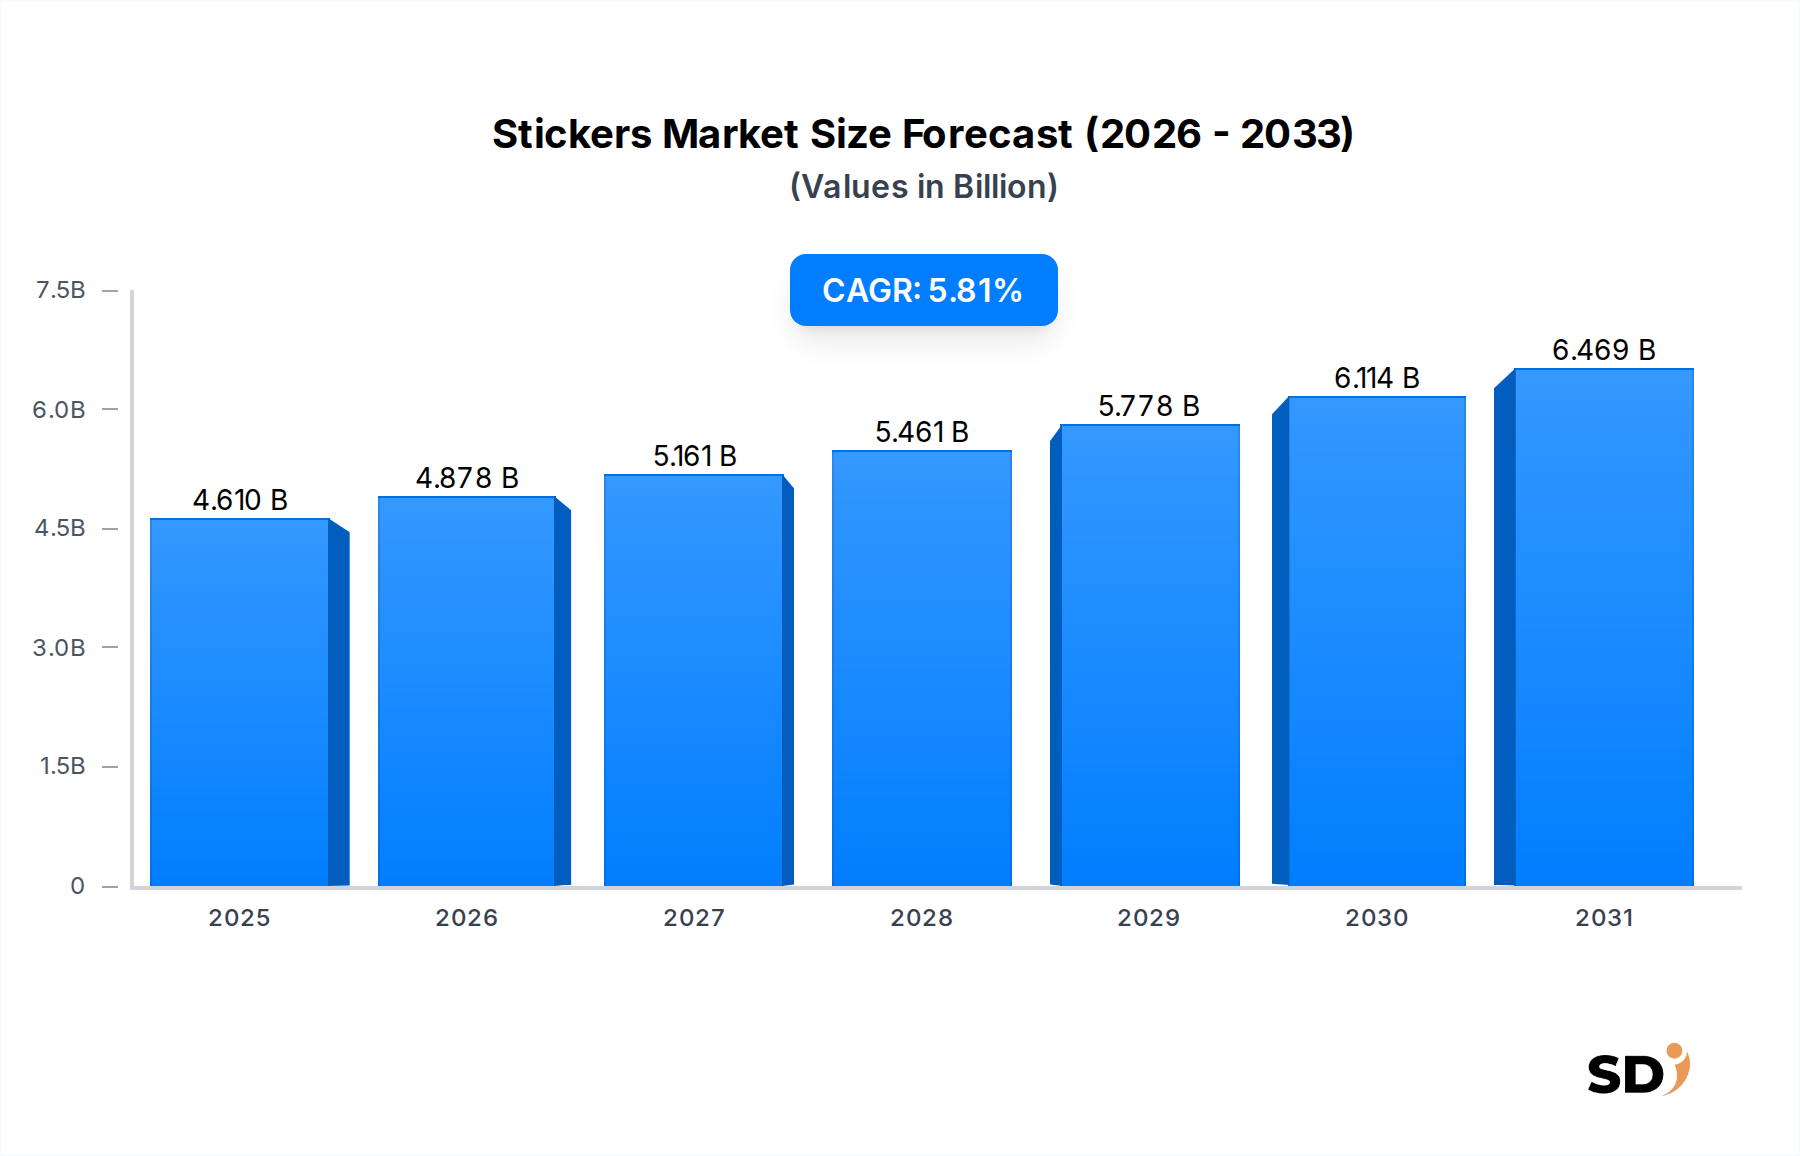
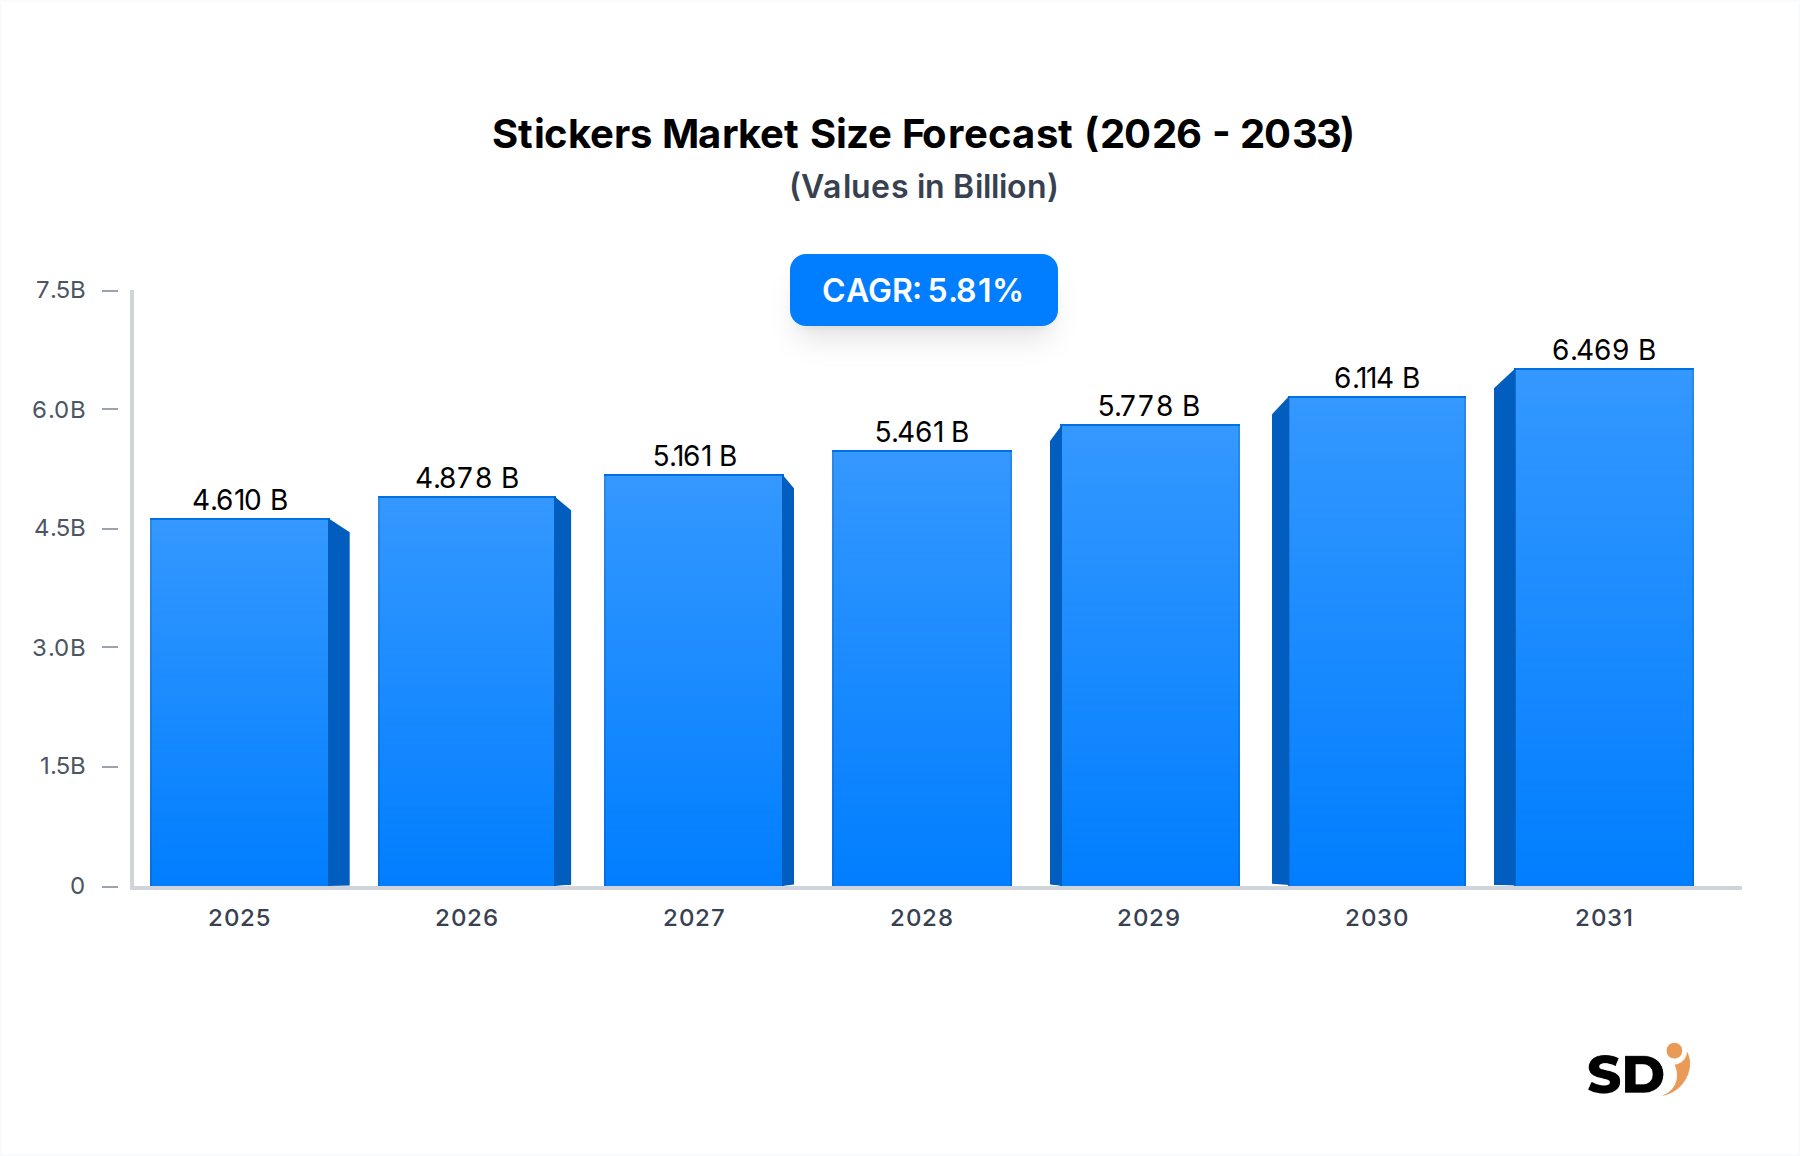
Stickers Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
4.610 B
2025
4.878 B
2026
5.161 B
2027
5.461 B
2028
5.778 B
2029
6.114 B
2030
6.469 B
2031
A central finding is the accelerating substitution of older pressure-sensitive labels with recyclable and lightweight facestocks. Buyers are prioritizing adhesive performance, printability, and end-of-life recyclability simultaneously. This shifts value toward integrated converters who control both adhesive formulation and finishing. The Self-Adhesive Label Market overlaps significantly with stickers, yet stickers are gaining share because of their decorative and interactive qualities. Businesses increasingly use sticker-based QR codes and tamper-evident features, linking the sticker category to broader digital engagement strategies. Supply chain pressure from mineral oil and paper prices persists, but raw material hedging and thin-film alternatives are stabilizing gross margins. The Food & Beverage Labeling Market within the sticker ecosystem is forecast to outperform the global average due to new beverage launches and clean-label packaging regulations.
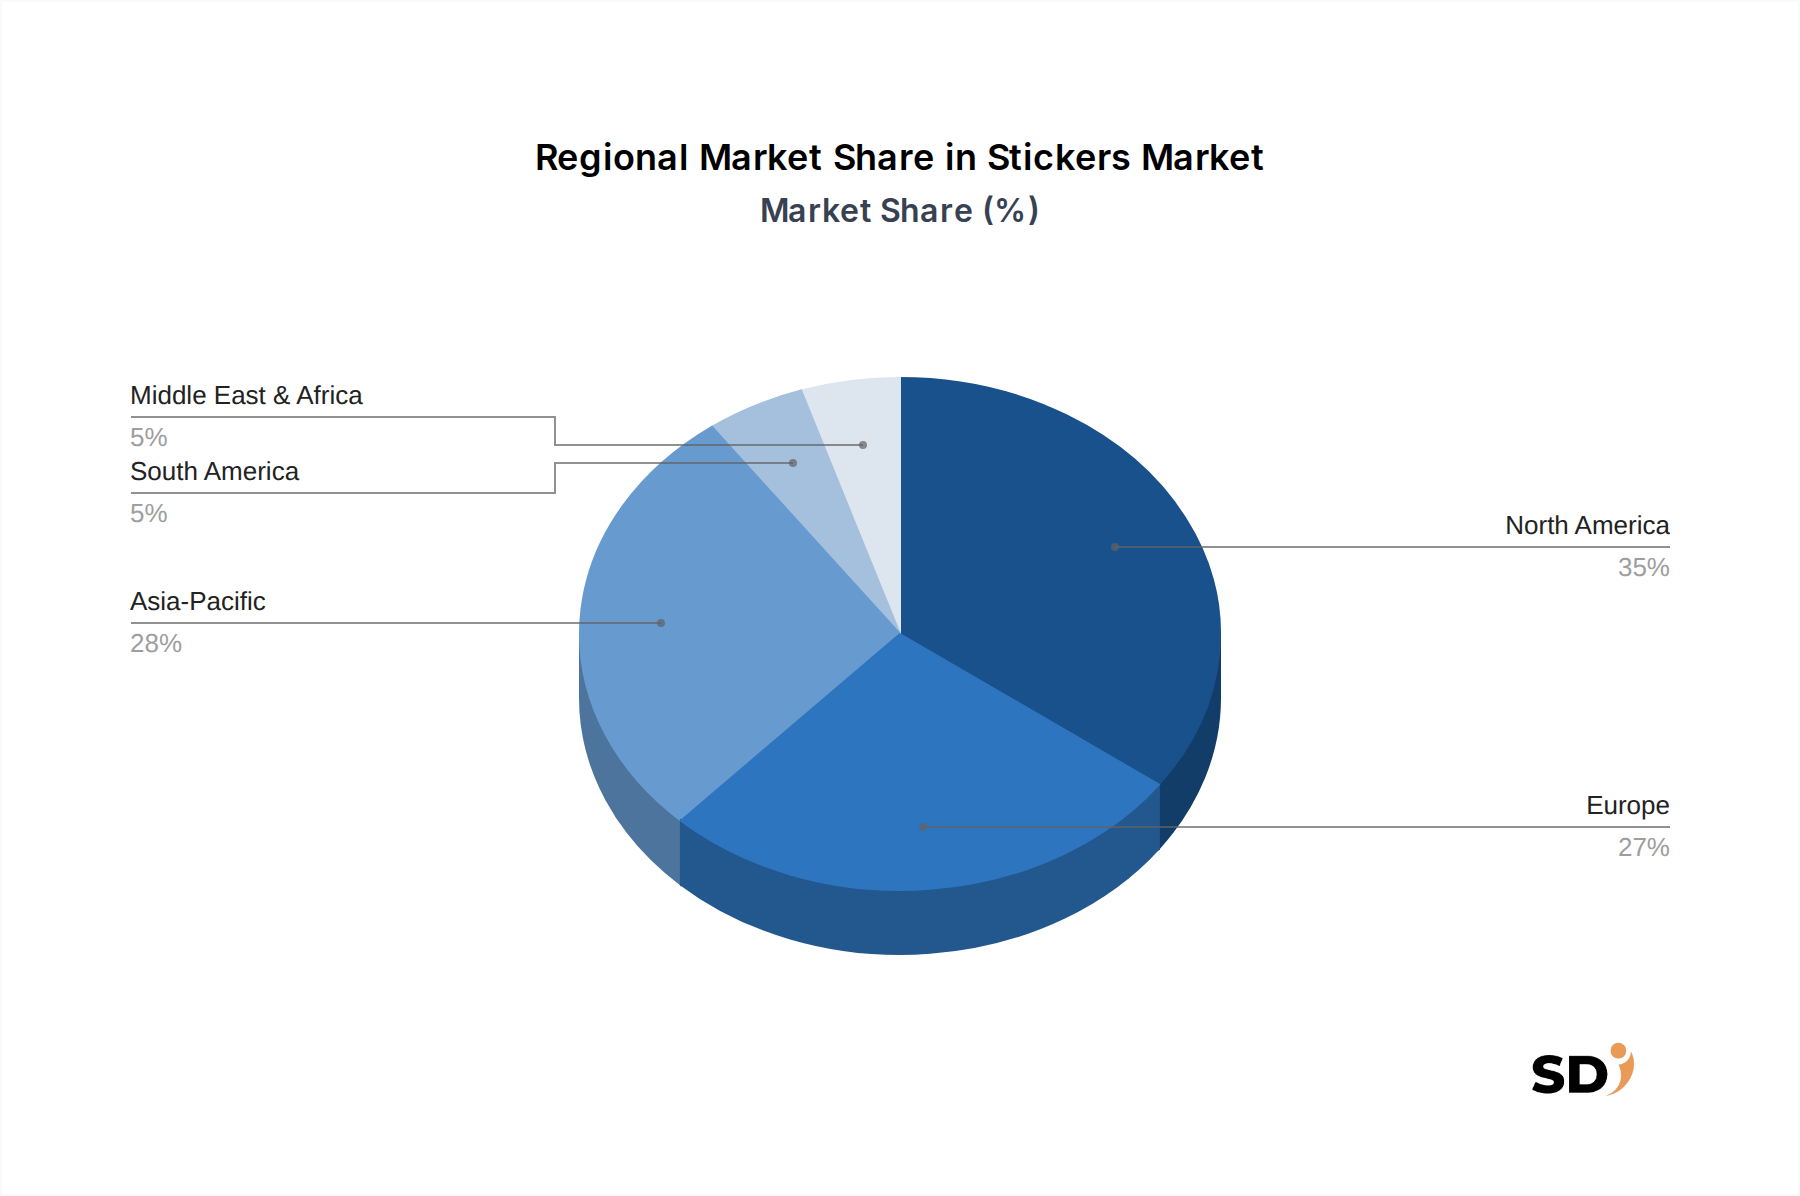
The estimated 5.81% CAGR over the forecast horizon implies a cumulative value increase of roughly 76% when measured from the 2024 base. North America, the largest regional market, contributes roughly 35% of global demand, with Europe and Asia-Pacific following closely. The shift toward sustainable and digitally printed stickers is forcing vendors to reorganize production around shorter, more complex order profiles. This will create consolidation opportunities for converters with in-house design and inline finishing capabilities, while marginal players face margin compression.
Segment Deep-Dive: Die Cut Stickers Dominance in Stickers Market
Die Cut vs. Kiss Cut Economics
Die cut stickers hold the largest share in the Types segment, representing approximately 62% of global revenue. The Die Cut Stickers Market benefits from lower per-unit material waste, faster roll-to-roll processing, and compatibility with high-speed applicators. Die cut formats are standard in food & beverage, health and beauty, and chemical drum labeling. In contrast, the Kiss Cut Stickers Market uses a silicone liner and adhesive layer that remains uncut, allowing easy peel of multiple stickers on one sheet. Kiss cut products command a 15–25% price premium because of the secondary kiss-cut operation and liner materials. However, kiss cut is favored for retail shelf labels, product inserts, and promotional sheet packs.
Application Share Shifts
Within applications, Food & Beverages accounts for over 30% of die cut sticker revenue. Beverage bottle label replacement cycles, limited edition can designs, and fresh produce stickers support steady demand. Health and beauty is the fastest-growing application for die cut stickers, expanding near 7.2% annually. Premium skincare and cosmetics brands prioritize intricate contours, foil stamping, and soft-touch laminates. The Health and Beauty Packaging Market relies on die cut stickers to achieve complex shapes with minimal adhesive bleed.
Material and Substrate Dynamics
Material selection in the Die Cut Stickers Market is shifting toward recycled paper and film facestocks. The Paper Sticker Materials Market is benefiting from the reintroduction of matt and natural kraft paper options that meet recyclability guidelines. However, filmic substrates dominate for moisture-prone environments such as chemical drums and personal care bottles. Adhesive chemistry remains a critical consideration; the Pressure Sensitive Adhesive Market supplies acrylic, rubber, and silicone systems that must withstand temperature extremes and surface energy variations. Large-format digital presses are enabling short-run die cut sticker production with same-day turnaround, stimulating niche orders. This aligns with the Digital Printing Packaging Market, where color consistency and low waste profiles are decisive.
Margin and Competitive Pressures
Die cut sticker converters operate with 18–25% gross margins, depending on volume and liner type. Material accounts for 50–60% of cost of goods sold, making procurement expertise essential. The shift to custom die shapes increases tooling and makeready costs, but digital platemaking reduces minimum order quantities. Intense price competition from low-cost Asian producers pressures standard rectangular formats; differentiation now comes from adhesive certification, artwork management, and integrated label application services. Share is expanding in favor of large-capacity converters who can absorb raw material inflation and offer sustainability documentation.
Primary Market Drivers & Growth Restraints in Stickers Market
Demand Catalysts
E-commerce packaging volumes continue to drive sticker consumption as parcel counts rise. The Sustainable Packaging Market is pushing adhesive providers to eliminate PVC and reduce liner siliconization. Regulatory deadlines in Europe for label recyclability are accelerating the switch from filmic to washable adhesive systems. Beverage and cosmetics brands are increasing sticker use for anti-counterfeiting: serialized QR codes, holographic foil, and tamper-evident die cuts. These features add value while supporting premium pricing.
Operational Bottlenecks
Raw material price volatility is the primary restraint. Pulp, film resin, and silicone prices fluctuate with energy costs, reducing predictability for long-term contracts. Skilled labor shortages in print finishing limit production capacity in mature North American and European markets. Compliance with food-contact and chemical labeling rules extends lead times for new product approvals. Additionally, the Digital Printing Packaging Market is growing quickly, but capital costs for high-throughput digital inkjet presses remain a barrier for mid-sized converters. Higher-performance adhesives from the Pressure Sensitive Adhesive Market enable thinner coatings but raise material costs. Sticker demand is still fragmented across thousands of small buyers, preventing the scale economies seen in other packaging categories.
Avery Dennison Corporation: A leading pressure-sensitive adhesive label supplier, investing in recyclable facestocks and intelligent label technologies for the Stickers Market.
CCL Industries Inc.: A global label converter with strong food and beverage shelves, known for high-volume die cut and roll-fed solutions.
UPM Raflatac: A self-adhesive label paper and film producer, emphasizing carbon-neutral materials and circular economy product lines.
3M Company: A diversified materials company supplying specialty adhesives, reflective films, and graphic sticker materials for industrial and consumer uses.
Multi-Color Corporation: A full-service label provider focused on beverage, health, and beauty end markets, with proprietary printing and finishing capabilities.
Huhtamaki: A packaging manufacturer using its foodservice and flexible packaging network to serve sticker and label demand across European markets.
Strategic Milestones & Recent Developments in Stickers Market
January 2023: Avery Dennison launched a recycled-content PET liner for pressure-sensitive labels, reducing landfill dependence in North America.
June 2023: CCL Industries completed the acquisition of a specialty film converter in Europe, expanding its linerless label capacity.
September 2023: UPM Raflatac introduced a carbon-neutral paper label facestock across its European portfolio, aligning with net-zero commitments.
March 2024: The FDA released updated guidance on food-contact adhesives, prompting label makers to review migration testing for new adhesive families.
July 2024: 3M expanded its adhesive-coated film portfolio for outdoor sticker applications, offering higher UV resistance and surface energy performance.
October 2024: A coalition of European beverage brands piloted fully washable adhesive labels for PET bottle recycling, aiming for 90% label removal rates.
Regional Market Analysis & Growth Corridors for Stickers Market
North America is the most mature regional market, holding roughly 35% of global value in 2024. Demand centers in the United States, where e-commerce conversion, craft beverage launches, and health & beauty shelf resets drive high SKU count stickers. Regional CAGR is projected at 4.9% as market penetration plateaus. Europe follows with a 27% value share and a 5.6% CAGR, influenced by circular economy regulations and the transition to recyclable label materials. Germany, France, and the United Kingdom lead, while Nordics push PVC-free specifications.
Asia-Pacific is the fastest-growing region, with a forecast CAGR of 7.4%, driven by China's scale in die cut sticker production and India's expanding consumer packaged goods sector. The region holds 28% of demand, and regional capacity additions are shifting export flows toward Southeast Asia. LAMEA, combining South America with the Middle East and Africa, accounts for roughly 10% of global value, growing at 5.2% CAGR. Food export labeling requirements and health authority registrations in Brazil and South Africa define compliance-driven demand. The fastest-growing geography is Asia-Pacific; the most mature is North America. Trade corridors from China to the United States and intra-ASEAN supply routes are expanding, while Europe focuses on regional sourcing for compliance reasons.
Regulatory & Policy Landscape: Stickers Market
In Europe, EU REACH restricts phthalates, lead, and certain plasticizers in pressure-sensitive adhesives. Label stocks must meet EN 643 for paper and Framework Directive 94/62/EC for packaging waste.
In North America, FDA 21 CFR 175.105 regulates adhesives in food-contact sticker applications. ASTM D6199 and the Sustainable Green Printing Partnership provide voluntary certifications that retailers increasingly require.
In Asia-Pacific, China's GB 9685 standard limits chemical additives in food-contact materials, and India's Bureau of Indian Standards is drafting similar label material guidelines.
Recent policy changes include California Proposition 65 litigation concerning heavy metals in label inks, and the EU's proposed Packaging and Packaging Waste Regulation, which sets recyclability criteria for labels and sleeves by 2030.
Compliance impact is two-sided: regulation raises certification cost and lead time, but it also creates barriers to entry and premium pricing for certified sticker suppliers. Converters are now using digital product passports to document material provenance, especially for European cross-border shipments.
Export, Cross-Border Trade & Tariff Impact on Stickers Market
China remains the largest exporter of die cut and kiss cut stickers, with annual export value estimated at USD 1.8 billion. Major destinations include the United States, Germany, Japan, and the United Kingdom. Tariff policy under Section 301 imposed 25% duties on certain Chinese-origin label products, driving a redistribution of orders toward Vietnam, Thailand, and India. These Southeast Asian suppliers benefit from lower labor costs and improved print quality but still rely on Chinese raw materials for film and adhesive.
Europe is a net importer of finished rolls from Turkey, Vietnam, and China, while intra-EU trade is growing because of recyclability requirements. The United States is a significant net importer, but domestic converters have recovered share through just-in-time service and digital printing agility. Tariff uncertainty remains a risk; a broader 10% global import duty scenario could raise US sticker costs by 8–12%, based on 2024 landed cost models. The most active trade corridors are Shenzhen to Los Angeles, Ningbo to Rotterdam, and Mumbai to Dubai. Non-tariff barriers, including mandatory recycling labels and chemical declarations under REACH, add two to three weeks of documentation time for cross-border shipments.
Stickers Segmentation
1. Application
1.1. Individual
1.2. Food & Beverages
1.3. Health and Beauty
1.4. Chemical
1.5. Others
2. Types
2.1. Die Cut Stickers
2.2. Kiss Cut Stickers
Stickers Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Stickers REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.81% from 2020-2034
Segmentation
By Application
Individual
Food & Beverages
Health and Beauty
Chemical
Others
By Types
Die Cut Stickers
Kiss Cut Stickers
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Individual
5.1.2. Food & Beverages
5.1.3. Health and Beauty
5.1.4. Chemical
5.1.5. Others
5.2. Market Analysis, Insights and Forecast - by Types
5.2.1. Die Cut Stickers
5.2.2. Kiss Cut Stickers
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Individual
6.1.2. Food & Beverages
6.1.3. Health and Beauty
6.1.4. Chemical
6.1.5. Others
6.2. Market Analysis, Insights and Forecast - by Types
6.2.1. Die Cut Stickers
6.2.2. Kiss Cut Stickers
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Individual
7.1.2. Food & Beverages
7.1.3. Health and Beauty
7.1.4. Chemical
7.1.5. Others
7.2. Market Analysis, Insights and Forecast - by Types
7.2.1. Die Cut Stickers
7.2.2. Kiss Cut Stickers
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Individual
8.1.2. Food & Beverages
8.1.3. Health and Beauty
8.1.4. Chemical
8.1.5. Others
8.2. Market Analysis, Insights and Forecast - by Types
8.2.1. Die Cut Stickers
8.2.2. Kiss Cut Stickers
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Individual
9.1.2. Food & Beverages
9.1.3. Health and Beauty
9.1.4. Chemical
9.1.5. Others
9.2. Market Analysis, Insights and Forecast - by Types
9.2.1. Die Cut Stickers
9.2.2. Kiss Cut Stickers
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Individual
10.1.2. Food & Beverages
10.1.3. Health and Beauty
10.1.4. Chemical
10.1.5. Others
10.2. Market Analysis, Insights and Forecast - by Types
10.2.1. Die Cut Stickers
10.2.2. Kiss Cut Stickers
11. Competitive Analysis
11.1. Company Profiles
11.1.1. StickerYou
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. StandOut Stickers
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Data Graphics Inc
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Comgraphx
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Websticker
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Sticker Mule
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Stickers Stickers
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Inc.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. StickerCanada
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. PsPrint
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Medford Technologies
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Inc
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Go Decal
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. StickerGiant
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. JoinPrint
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Sticker Robot
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Stickerfly
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Resource Label Group
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. LLC 7.60
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Graphicsland
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Inc.
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. Freely Creative
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. Inc
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. Kartdavid Limited
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. Medford Technologies
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Stickers Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: Stickers Volume Breakdown (K, %) by Region 2026 & 2034
Figure 3: North America Stickers Revenue (billion), by Application 2026 & 2034
Figure 4: North America Stickers Volume (K), by Application 2026 & 2034
Figure 5: North America Stickers Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Stickers Volume Share (%), by Application 2026 & 2034
Figure 7: North America Stickers Revenue (billion), by Types 2026 & 2034
Figure 8: North America Stickers Volume (K), by Types 2026 & 2034
Figure 9: North America Stickers Revenue Share (%), by Types 2026 & 2034
Figure 10: North America Stickers Volume Share (%), by Types 2026 & 2034
Figure 11: North America Stickers Revenue (billion), by Country 2026 & 2034
Figure 12: North America Stickers Volume (K), by Country 2026 & 2034
Figure 13: North America Stickers Revenue Share (%), by Country 2026 & 2034
Figure 14: North America Stickers Volume Share (%), by Country 2026 & 2034
Figure 15: South America Stickers Revenue (billion), by Application 2026 & 2034
Figure 16: South America Stickers Volume (K), by Application 2026 & 2034
Figure 17: South America Stickers Revenue Share (%), by Application 2026 & 2034
Figure 18: South America Stickers Volume Share (%), by Application 2026 & 2034
Figure 19: South America Stickers Revenue (billion), by Types 2026 & 2034
Figure 20: South America Stickers Volume (K), by Types 2026 & 2034
Figure 21: South America Stickers Revenue Share (%), by Types 2026 & 2034
Figure 22: South America Stickers Volume Share (%), by Types 2026 & 2034
Figure 23: South America Stickers Revenue (billion), by Country 2026 & 2034
Figure 24: South America Stickers Volume (K), by Country 2026 & 2034
Figure 25: South America Stickers Revenue Share (%), by Country 2026 & 2034
Figure 26: South America Stickers Volume Share (%), by Country 2026 & 2034
Figure 27: Europe Stickers Revenue (billion), by Application 2026 & 2034
Figure 28: Europe Stickers Volume (K), by Application 2026 & 2034
Figure 29: Europe Stickers Revenue Share (%), by Application 2026 & 2034
Figure 30: Europe Stickers Volume Share (%), by Application 2026 & 2034
Figure 31: Europe Stickers Revenue (billion), by Types 2026 & 2034
Figure 32: Europe Stickers Volume (K), by Types 2026 & 2034
Figure 33: Europe Stickers Revenue Share (%), by Types 2026 & 2034
Figure 34: Europe Stickers Volume Share (%), by Types 2026 & 2034
Figure 35: Europe Stickers Revenue (billion), by Country 2026 & 2034
Figure 36: Europe Stickers Volume (K), by Country 2026 & 2034
Figure 37: Europe Stickers Revenue Share (%), by Country 2026 & 2034
Figure 38: Europe Stickers Volume Share (%), by Country 2026 & 2034
Figure 39: Middle East & Africa Stickers Revenue (billion), by Application 2026 & 2034
Figure 40: Middle East & Africa Stickers Volume (K), by Application 2026 & 2034
Figure 41: Middle East & Africa Stickers Revenue Share (%), by Application 2026 & 2034
Figure 42: Middle East & Africa Stickers Volume Share (%), by Application 2026 & 2034
Figure 43: Middle East & Africa Stickers Revenue (billion), by Types 2026 & 2034
Figure 44: Middle East & Africa Stickers Volume (K), by Types 2026 & 2034
Figure 45: Middle East & Africa Stickers Revenue Share (%), by Types 2026 & 2034
Figure 46: Middle East & Africa Stickers Volume Share (%), by Types 2026 & 2034
Figure 47: Middle East & Africa Stickers Revenue (billion), by Country 2026 & 2034
Figure 48: Middle East & Africa Stickers Volume (K), by Country 2026 & 2034
Figure 49: Middle East & Africa Stickers Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Stickers Volume Share (%), by Country 2026 & 2034
Figure 51: Asia Pacific Stickers Revenue (billion), by Application 2026 & 2034
Figure 52: Asia Pacific Stickers Volume (K), by Application 2026 & 2034
Figure 53: Asia Pacific Stickers Revenue Share (%), by Application 2026 & 2034
Figure 54: Asia Pacific Stickers Volume Share (%), by Application 2026 & 2034
Figure 55: Asia Pacific Stickers Revenue (billion), by Types 2026 & 2034
Figure 56: Asia Pacific Stickers Volume (K), by Types 2026 & 2034
Figure 57: Asia Pacific Stickers Revenue Share (%), by Types 2026 & 2034
Figure 58: Asia Pacific Stickers Volume Share (%), by Types 2026 & 2034
Figure 59: Asia Pacific Stickers Revenue (billion), by Country 2026 & 2034
Figure 60: Asia Pacific Stickers Volume (K), by Country 2026 & 2034
Figure 61: Asia Pacific Stickers Revenue Share (%), by Country 2026 & 2034
Figure 62: Asia Pacific Stickers Volume Share (%), by Country 2026 & 2034
Table 91: Rest of Asia Pacific Stickers Revenue (billion) Forecast, by Application 2020 & 2034
Table 92: Rest of Asia Pacific Stickers Volume (K) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research constitutes 75% of total effort, with more than 40 structured interviews conducted between Q3 2024 and Q1 2025.
Interview respondents were selected from label converters, facestock and liner producers, adhesive formulators, flexographic and digital press OEMs, and brand-owner packaging functions.
Specific job titles targeted include Label Production Manager, Packaging Procurement Director, Regulatory Affairs Manager for Food-Contact Materials, and Sustainability Packaging Engineer.
Financial data from Bloomberg, Factiva, Hoovers, and PitchBook is used to validate company-level sticker revenues and capital expenditure plans.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement / Purchasing Managers
28%
Production / Operations Directors
22%
Sustainability / Environmental Managers
18%
Regulatory Affairs Specialists
17%
Supply Chain Analysts
15%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Label Converters
35%
Raw Material Suppliers
25%
Brand Owners / End Users
20%
Distributors / Wholesalers
12%
Printing Equipment OEMs
8%
Secondary Research & Industry Benchmarking
Secondary research covers 25% of data inputs, anchored in verified government and association sources including FDA, ECHA, and PMMI.
Trade association benchmarking uses published reports from FTA and EuPIA to validate equipment installation bases and ink/material consumption.
Regulatory frameworks reviewed include REACH, FDA 21 CFR 175.105, China GB 9685, and EU PPWR proposals.
Demand Modeling & Market Estimation
Both top-down and bottom-up approaches are run simultaneously: top-down sizing from the parent packaging market and bottom-up aggregation from sticker product category revenues.
Bottom-up calculations employ unit volume proxies such as number of pressure-sensitive label rolls imported per manufacturing facility, average order size per application, ratio of die-cut volume to kiss-cut volume, and certification lead time in weeks for food-contact adhesive approval.
Demand is modeled across all segments and regions defined in the report: Stickers, by Application (Individual, Food & Beverages, Health and Beauty, Chemical, Others), by Types (Die Cut Stickers, Kiss Cut Stickers), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific), Forecast 2026-2034.
Data Accuracy & Quality Check
Multi-level triangulation reconciles supply-side production estimates, demand-side consumption surveys, trade data, and expert judgement.
Final market figures are validated to an 85–90% accuracy level using our standard confidence interval calculation.
Every report is updated to the date of purchase, with qualitative developments and financial references re-verified within 30 days of publication.
Frequently Asked Questions
1. How do export-import flows shape the stickers market across major trade corridors?
China remains the largest net exporter of self-adhesive labels and stickers, with cross-border shipments exceeding USD 3.2 billion annually. The United States and Germany anchor import demand for die cut stickers, though tariff shifts under the US-China trade relationship have pushed some buyers toward Southeast Asian suppliers. Freight cost volatility continues to influence landed cost calculations for high-volume orders.
2. What are the main barriers to entry for new sticker manufacturers?
Capital-intensive flexographic and digital printing lines create scale thresholds; a mid-size die cut line requires USD 1.5–3 million in equipment. Strong moats also stem from proprietary adhesive formulations and long-term procurement contracts with food and beverage brands. Compliance with FDA and EU food-contact regulations adds certification time of 6–12 months before market entry.
3. Which post-pandemic recovery patterns are visible in the stickers market?
Demand rebounded sharply in 2021–2022 as e-commerce packaging volumes expanded, with global sticker consumption climbing 7.4% in 2022. Structural shifts favor digitized short-run production and plastic-free facestock materials. Hybrid labels with QR codes and RFID integration now represent roughly 12% of new sticker orders.
4. What are the key segments and product types driving sticker market growth?
Die cut stickers dominate the product mix, accounting for about 62% of revenue in 2024. The Food & Beverages application is the largest end-use segment, driven by beverage launches and fresh food labeling. Health and Beauty is the fastest-growing application at an estimated 7.2% CAGR through 2034.
5. What recent developments and product launches are reshaping the stickers market?
In 2023, Avery Dennison launched a line of recyclable PET label facestocks, and CCL Industries expanded its sustainable portfolio through the acquisition of a specialty film converter. UPM Raflatac introduced a carbon-neutral paper label material in 2024. These moves align with brand owner commitments to reduce packaging waste.
6. How does the regulatory environment impact sticker production and sales?
EU REACH restricts specific phthalates and plasticizers used in PVC-based stickers, forcing reformulation of 8–10% of legacy products. FDA 21 CFR 175.105 governs adhesives in food-contact labels, requiring migration testing for each adhesive change. California's Proposition 65 also affects labeling inks containing heavy metals, prompting accelerated adoption of UV-cured and water-based inks.