Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Tethered Caps Market: Evolution, Growth Drivers, and 2034 Forecast
Tethered Caps
Tethered Caps Market: Evolution, Growth Drivers, and 2034 Forecast
Tethered Caps by Application (Plastic Bottle, Carton Bottle, Others), by Types (A Tether, Two Tethers), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Aug 29, 2026|Base Year : 2025|Pages : 96
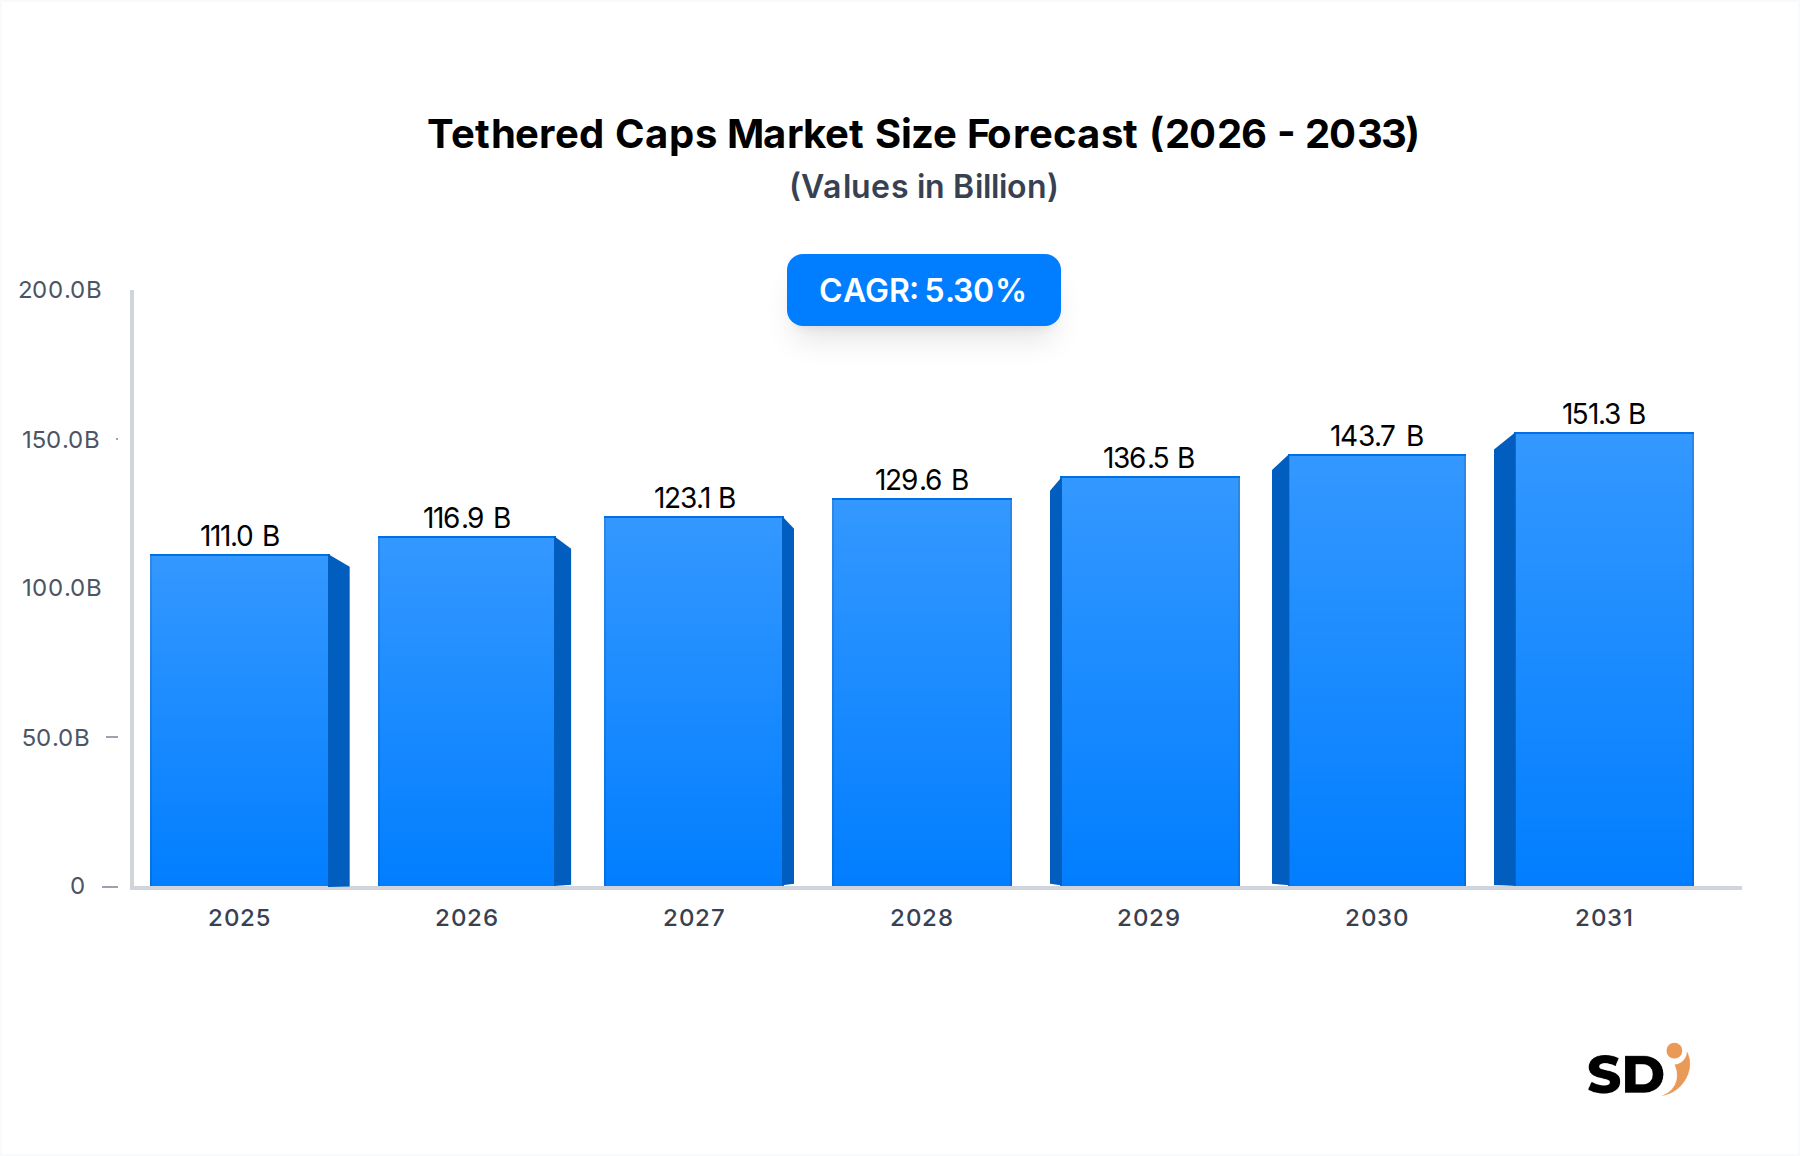
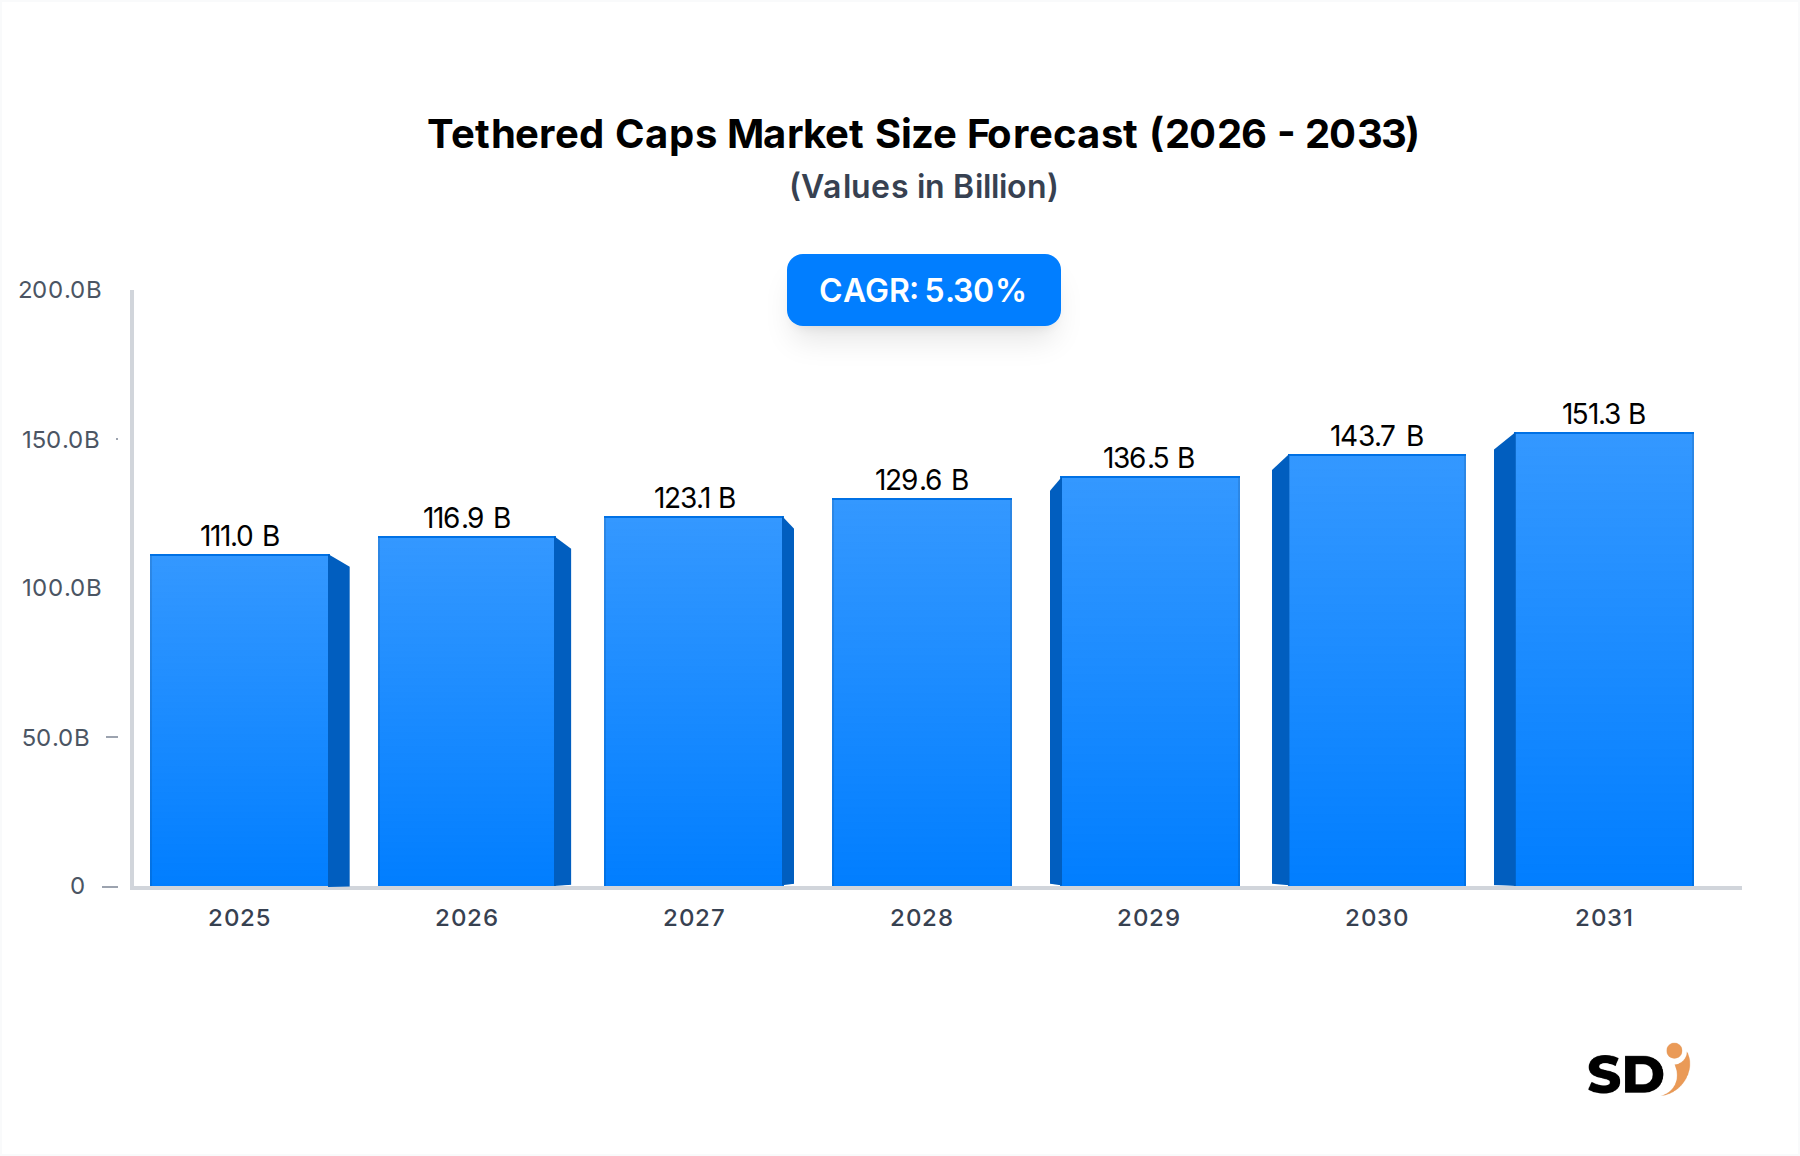
The global tethered caps market is building momentum from a regulatory, retail, and structural redesign of beverage packaging. At USD 111.01 billion in 2025, the market is projected to reach USD 176.69 billion by 2034, expanding at a 5.3% CAGR. Growth is not linear, however; it is concentrated in markets with high-volume bottled water consumption and strong enforcement of circular economy rules.
Tethered Caps Market Size (In Billion)
200.0B
150.0B
100.0B
50.0B
0
111.0 B
2025
116.9 B
2026
123.1 B
2027
129.6 B
2028
136.5 B
2029
143.7 B
2030
151.3 B
2031
The Beverage Packaging Market provides the strategic anchor for this transformation. European directives introduced after 2019 require that single-use beverage containers up to three liters be equipped with tethered caps by 2024/2025. This has forced large brand owners to redesign cap-bottle interactions rather than simply add a plastic tab. The resulting shift in packaging architecture is visible across the entire Packaging Closures Market, where tether designs are becoming the default performance benchmark.
Within the Plastic Bottle Caps Market, tethered formats now represent the fastest-growing specification. The ability to maintain a one-piece closure reduces contamination and improves recycling stream quality. At the same time, the Injection Molded Caps Market sees rising demand for high-cavitation molds that can produce tethers with lower weight without compromising flex fatigue. Asia-Pacific, the largest regional market, is also where incremental volume growth is steepest due to expanding middle-class consumption of packaged water.
Supply-side factors reinforce demand. Resin producers have introduced high-melt-flow HDPE grades specifically suited to thin-section tether hinges. Brands use these materials to avoid multilayer constructions that complicate recycling. The result is that the market is shifting from compliance-driven purchasing toward performance-based procurement, where tether retention force, opening torque, and material usage are tracked with a level of precision previously reserved for medical packaging. The strategic growth drivers therefore include regulation, brand-level ESG commitments, and operational gains from simplified capping lines.
The commercial opportunity is not evenly distributed. Companies that offer integrated design, mold engineering, and line retrofit services are positioned to capture disproportionate value. While the market remains fragmented, scale advantages are emerging in mold capacity and resin supply contracts. The next section examines why the Plastic Bottle segment anchors the market.
Segment Deep-Dive: Plastic Bottle Dominance in Tethered Caps Market
Segment Size & Revenue Contribution
The Plastic Bottle segment contributes 68% of global tethered caps revenue in 2025, with value estimated at USD 75.5 billion. This concentration reflects the scale of bottled water and soft drinks, which together consume more than seven out of ten tethered caps produced globally. The Carton Bottle Closures Market, despite public attention to gable-top packaging, contributes only 21% share, with the remaining 11% split across food, home care, and other containers.
Why Plastic Bottles Lead
Plastic Bottle Caps Market growth is tied to three structural factors. First, bottled water and carbonated soft drinks account for 74% of tethered cap applications globally. Second, plastic bottle capping lines run at speeds above 60,000 caps per hour, making tether geometry a line-efficiency variable rather than a simple feature. Third, the installed base of plastic bottles is vast; replacing conventional caps with tethered versions across EU bottling lines alone creates annual orders of over 70 billion units.
Sub-Segment Dynamics: A Tether vs. Two Tethers
Within the Plastic Bottle segment, A Tether designs hold roughly 78% of volume, because a single attachment point minimizes mold complexity and material use. Two Tethers designs are used mainly in premium still water and juice bottles, where double retention prevents cap loss during pouring. The Two Tethers Market is growing from a small base, and on average pricing is 12-18% higher per 1,000 caps. However, profit margins on Two Tethers are under pressure as molds requiring sliding cores are slower and more energy-intensive. By 2030, we expect A Tether designs to consolidate share in mainstream applications, while Two Tethers remains a niche for high-end liquid foods.
Margin and Substitution Risk
Plastic Bottle segment margins are at risk from resin cost inflation and retail demands for lightweighting. During 2025, HDPE prices rose by 9% globally, while brand owners demanded 5-8% cost-down year-on-year. To reconcile this tension, suppliers are shifting to thinner tether wings and using recycled content. The Carton Bottle Closures Market is following a different trajectory, where tether designs are still being standardized; this creates more room for design differentiation, but volume is capped by carton packaging growth. The Plastic Bottle segment remains the strategic battleground because of its scale, and the commercial winners will be those who optimize tether stiffness and hinge fatigue for high-speed filling.
Technology and Design Convergence
The transition from bolt-on tether to monolithic cap design has changed tooling investment. New molds made for the Injection Molded Caps Market now incorporate double-angle ejectors and valve-gated hot runners to create undercuts for tether loops. The resulting parts use 20% less resin than early tethers, with opening cycle life exceeding 12,000 bends. This has made it possible for high-volume Plastic Bottle Caps Market operations to keep total cost below 10% premium over legacy caps.
Primary Market Drivers & Growth Restraints in Tethered Caps Market
Demand Drivers
Regulation is the sharpest driver. The EU Single-Use Plastics Directive (EU) 2019/904 mandates that beverage containers up to 3 liters sold in the EU must have caps that remain attached, affecting 22% of global beverage volume. Compliance deadlines have already caused non-compliant stock to be withdrawn from retail shelves in at least four member states, increasing urgency across the supply chain. The Recyclable Closure System Market is also benefiting from national extended producer responsibility schemes that impose higher fees when caps are separate and can escape the recycling stream. In Germany, packaging register data shows that tethered caps reduce cap loss at sorting facilities by up to 35%.
Consumer sentiment adds a secondary demand driver. Surveys conducted by the European Commission found that 61% of respondents consider attached caps an essential feature of recyclable packaging. The Food Packaging Market is now extending tether specifications to sauces, dressings, and condiment bottles, broadening the addressable base.
Growth Restraints
The most immediate bottleneck is tooling investment. A typical high-speed cap mold for tethered closures costs USD 350,000 to USD 750,000, and conversion of an entire bottling line requires coordinated timing with cap supplier changeovers. Small and mid-size beverage companies are delaying conversion due to capital constraints, capping near-term growth. Another restraint is material quality. While Recycled PET Market expansion has increased rPET availability, tether hinges require high flex-crack resistance; many recycled resins still fail accelerated fatigue testing, forcing converters to use virgin or higher-cost copolymers. Finally, geographic divergence in regulation complicates global production planning. North America and Asia lack a federal mandate equivalent to the EU directive, so tether adoption in those regions is being driven by brand commitments rather than regulation, which slows replacement cycles.
Bericap: A global closures specialist with extensive tether patent portfolio; it supplies major water and CSD brands and operates high-cavitation molds in Europe, North America, and Asia.
Closure Systems International (CSI): Known for integrated closure and capping systems, CSI has developed rapid-change tether tooling for beverage lines running above 70,000 caps per hour.
Silgan Holdings: One of the largest closure manufacturers globally, Silgan expanded its tether lines via acquisition and is focused on retrofitting existing plants for one-piece caps.
United Caps: This company positions itself around lightweight tethered closures and has announced several resin-saving designs with walls below 0.9 mm.
AptarGroup: Active in both food and beverage tethered caps, Aptar targets premium brands with dispensing and tethered functions combined.
Berry Global: Offers a broad catalog of closures, including tethered options for still and sparkling drinks, with strong focus on circular economy credentials.
Amcor: Although better known for flexible packaging, Amcor has a dedicated closures division that produces tethered caps for carton and bottle applications, especially in the Carton Bottle Closures Market.
Alpla: An Austrian packaging and recycling specialist that integrates tether injection molding with in-house PET recycling, enabling closed-loop material streams.
Competitive positioning increasingly depends on vertical integration with recycling assets. Companies that secure access to food-grade rPET have a cost advantage because the HDPE Resin Market and Recycled PET Market price cycles can be balanced through internal supply. The top four firms collectively hold an estimated 34-38% share, while a long tail of regional molders serves local beverage brands.
Strategic Milestones & Recent Developments in Tethered Caps Market
July 2021: The EU published binding implementing rules for tethered caps, setting the 2024 date for beverage containers up to 3 liters.
June 2023: Bericap launched a lightweight tether cap for still water at Interpack, using 15% less material than its previous generation.
January 2024: Coca-Cola began nationwide conversion of its 0.5L PET bottles across Germany, France, and Benelux; more than 2 billion caps switched in Phase 1.
July 2024: EU enforcement phase began; multiple retail chains delisted non-compliant own-brand bottles. Closure suppliers reported a 28% surge in retrofit inquiries in Q3 2024.
March 2025: United Caps unveiled a 26 mm tether closure with a two-point attachment, targeting the Carton Bottle Closures Market.
August 2025: A consortium of UAE-based bottlers announced standardized tethered caps for the GCC market, aligning regional specifications with EU norms.
October 2025: Silgan completed the integration of a European tether molding plant, adding 4 billion caps of annual capacity. The expanded footprint is designed to serve the Dutch, French, and Spanish beverage sectors.
November 2025: Injection Molded Caps Market supplier Netstal demonstrated a 96-cavity mold for tethered caps, reducing cycle time to 4.1 seconds and pushing material efficiency to the industry frontier.
Regional Market Analysis & Growth Corridors for Tethered Caps Market
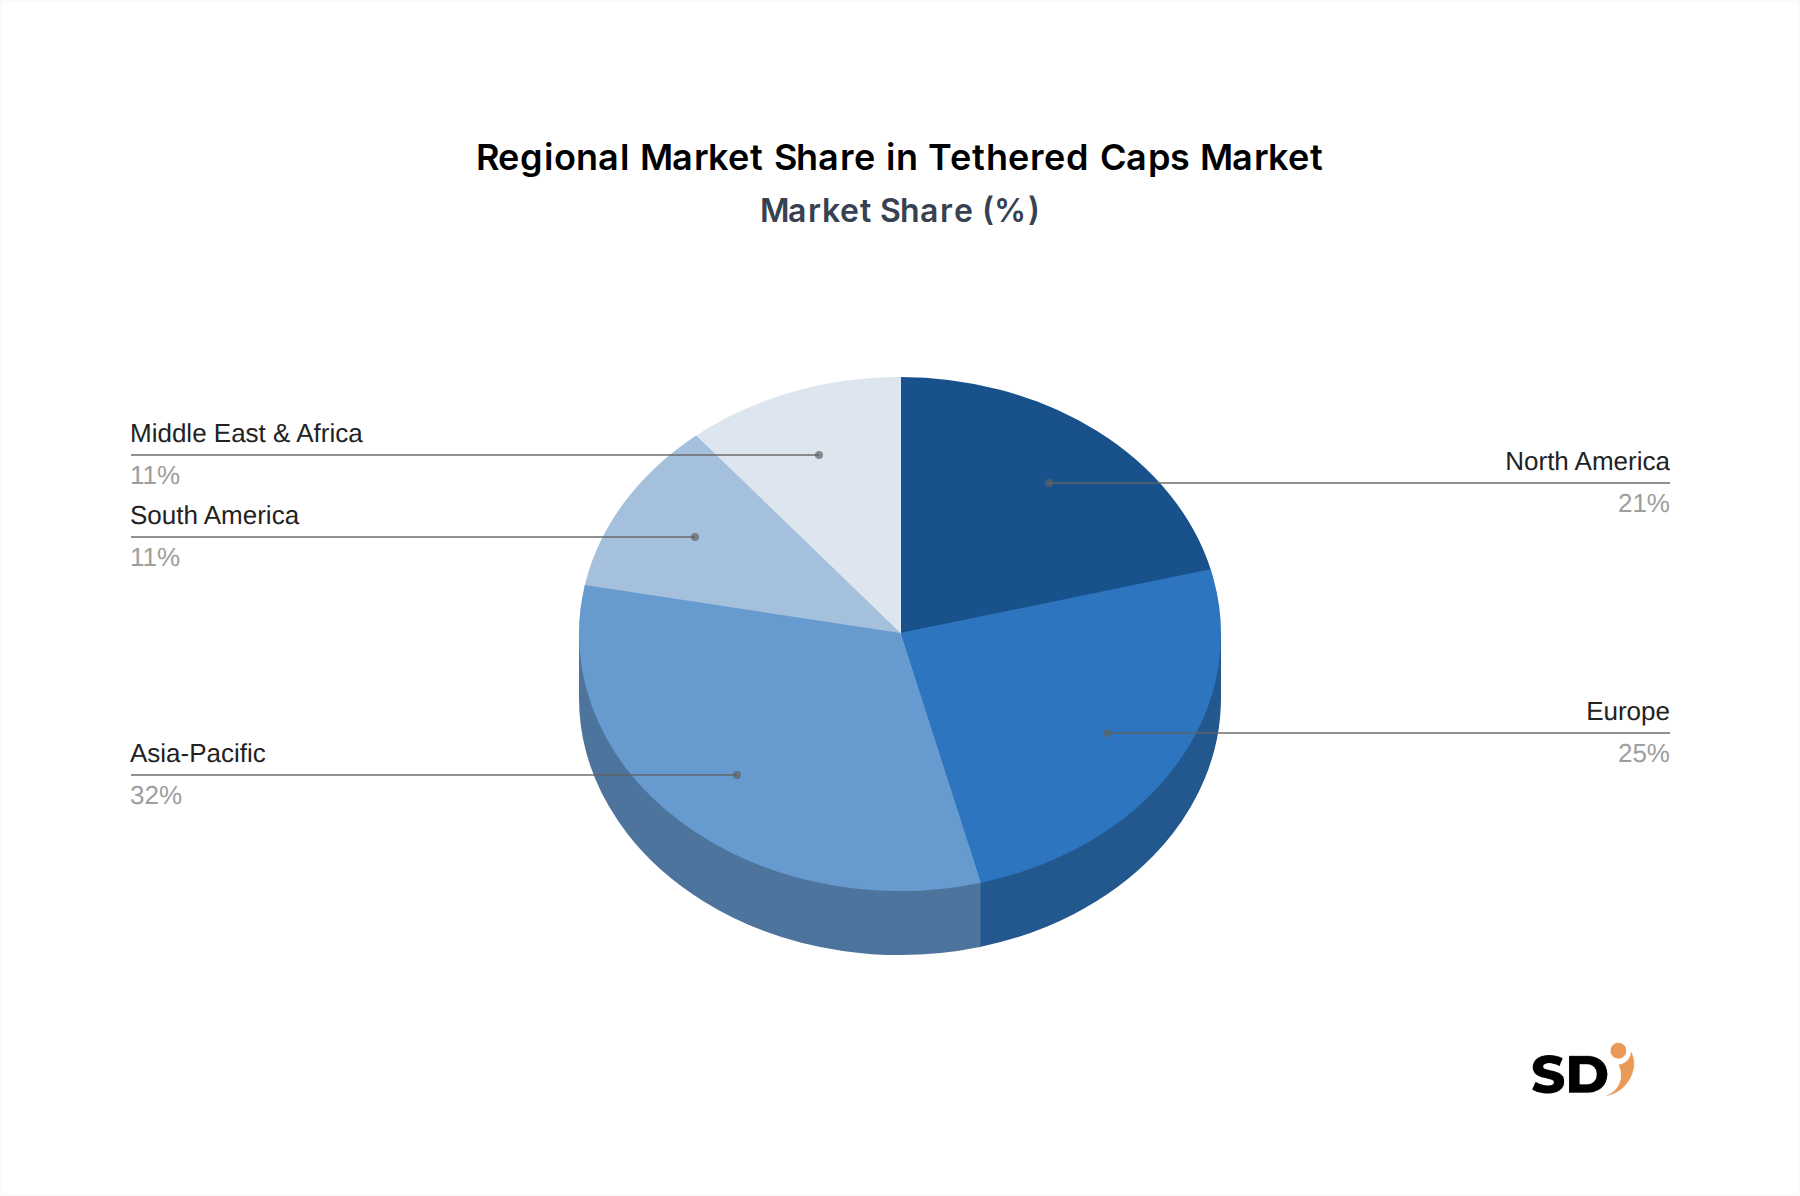
Asia-Pacific (CAGR 6.2%; 32% revenue share)
Asia-Pacific is the largest regional market due to high per-capita bottled water consumption and expanding beverage manufacturing. China alone accounts for 45% of Asia-Pacific tether production, although domestic adoption has been led by export-oriented bottlers. India and ASEAN are emerging as the fastest-growing corridors as international brands replicate EU-compliant packaging across their regional networks. Local regulatory pressure is weaker, but brand harmonization is pulling the market forward.
Europe (CAGR 5.8%; 25% revenue share)
Europe is the regulatory epicenter. The EU Single-Use Plastics Directive provides a binding compliance framework, meaning that every beverage container up to 3 liters sold in the EU must have attached caps. This has made Europe the densest tether adoption market, with an estimated 95% of compliant beverage units in Germany, France, the Netherlands, and the Nordics. Growth is sustained by high recycling collection rates and aggressive extended producer responsibility fees, which make tethered designs economically rational.
North America (CAGR 3.9%; 21% revenue share)
North America is the most mature market, with slower volume growth because no federal mandate exists and beverage packaging is heavily consolidated. However, corporate sustainability commitments from Coca-Cola, PepsiCo, and Keurig Dr Pepper are gradually converting legacy cap inventories. California's SB 54 sets minimum plastic reduction and recyclability targets that are expected to accelerate tether adoption starting in 2027.
South America, Middle East & Africa (CAGR 4.5%; combined 22% revenue share)
Brazil and Mexico are the largest tether users in Latin America, driven by beverage exports to Europe and multinational brand standards. The Middle East, particularly the GCC, is emerging as a significant growth corridor as large bottlers pre-align with European packaging norms to protect export access. Africa remains nascent, but South Africa and North Africa are seeing donor-funded and retail-led plastic pollution initiatives that encourage tethered caps.
The fastest-growing region is Asia-Pacific, with a 6.2% CAGR, while North America is the most mature at 3.9% CAGR. Supply chain managers should prioritize EU-compliant tooling first, then use Asia-Pacific export corridors to amortize high mold investments.
Sustainability, ESG & Decarbonization Pressures on Tethered Caps Market
Sustainability is no longer a peripheral consideration; it is the principal commercial constraint in the tethered caps market. The EU's 2025 Packaging and Packaging Waste Regulation (PPWR) tightens recyclability requirements for all packaging, including closures, by mandating that any tethered cap design must be compatible with existing sorting and recycling infrastructure. The Recyclable Closure System Market therefore benefits, but it also faces increased scrutiny of the entire closure-bottle system.
Recycled content mandates are pushing raw material substitution. France's AGEC law requires all plastic packaging to include at least 30% recycled content by 2030, and as synthetic resin prices rise, the Recycled PET Market has become a strategic input for cap producers. For HDPE caps, post-consumer recycled HDPE is still limited, but multiple converters are piloting mechanically recycled resins with enhanced tether hinge formulations.
ESG-driven procurement is changing buyer behavior. Global beverage companies now require closure suppliers to disclose carbon footprint per million caps, water consumption per mold cycle, and waste-to-landfill rate. Leading players are responding by installing solar-powered injection molding cells and integrating regrind loops. The net effect is a market where energy intensity, resin yield, and recyclability are as important as mechanical performance. By 2032, we anticipate that at least 45% of tethered caps produced globally will incorporate some form of recycled polymer.
Investment, M&A & Funding Activity in Tethered Caps Market
M&A activity in the tethered caps space has intensified as processors seek scale to recoup mold investments. In 2023, Silgan Holdings acquired Bapco Closures, a Middle East-based closure manufacturer, expanding tethered cap capacity and providing a regional platform for export to Europe and Africa. AptarGroup has invested in a dedicated tether center of excellence in France, combining food-grade closure know-how with digital twin design simulation. Bericap acquired a small German injection molding plant to bring Two Tethers and other complex closure production in-house, reducing reliance on outside molders.
Private equity interest is growing in specialty packaging. The essential nature of tethered caps, combined with regulatory tailwinds, makes closure assets attractive infrastructure-type investments. Several PE-backed platforms in the US and Europe are consolidating regional cap molders to build a broader tether product portfolio. High-growth sub-segments attracting capital include premium dispensing tether caps for sports drinks and lightweight mono-material closures for still water. Investment is also flowing into mold engineering: companies producing multi-cavity molds for the Injection Molded Caps Market have seen order books extend beyond 12 months.
Strategic partnerships are being formed with recycled resin suppliers. In 2025, United Caps and Borealis announced a collaboration to validate high-flow PP and HDPE grades for tether applications, with a target of 30% recycled content without loss of hinge durability. This wave of investments suggests that the competitive threshold will rise sharply by 2028; smaller players without high-cavitation molds and vertical resin access will struggle to achieve unit economics.
Tethered Caps Segmentation
1. Application
1.1. Plastic Bottle
1.2. Carton Bottle
1.3. Others
2. Types
2.1. A Tether
2.2. Two Tethers
Tethered Caps Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Tethered Caps REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.3% from 2020-2034
Segmentation
By Application
Plastic Bottle
Carton Bottle
Others
By Types
A Tether
Two Tethers
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Plastic Bottle
5.1.2. Carton Bottle
5.1.3. Others
5.2. Market Analysis, Insights and Forecast - by Types
5.2.1. A Tether
5.2.2. Two Tethers
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Plastic Bottle
6.1.2. Carton Bottle
6.1.3. Others
6.2. Market Analysis, Insights and Forecast - by Types
6.2.1. A Tether
6.2.2. Two Tethers
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Plastic Bottle
7.1.2. Carton Bottle
7.1.3. Others
7.2. Market Analysis, Insights and Forecast - by Types
7.2.1. A Tether
7.2.2. Two Tethers
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Plastic Bottle
8.1.2. Carton Bottle
8.1.3. Others
8.2. Market Analysis, Insights and Forecast - by Types
8.2.1. A Tether
8.2.2. Two Tethers
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Plastic Bottle
9.1.2. Carton Bottle
9.1.3. Others
9.2. Market Analysis, Insights and Forecast - by Types
9.2.1. A Tether
9.2.2. Two Tethers
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Plastic Bottle
10.1.2. Carton Bottle
10.1.3. Others
10.2. Market Analysis, Insights and Forecast - by Types
10.2.1. A Tether
10.2.2. Two Tethers
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Berry Global
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Corvaglia
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. ALPLA
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Tetra Pak
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. TriMas
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. SACMI
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Bericap
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. KHS
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. HEUFT
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Caplugs
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Tethered Caps Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Tethered Caps Revenue (billion), by Application 2026 & 2034
Figure 3: North America Tethered Caps Revenue Share (%), by Application 2026 & 2034
Figure 4: North America Tethered Caps Revenue (billion), by Types 2026 & 2034
Figure 5: North America Tethered Caps Revenue Share (%), by Types 2026 & 2034
Figure 6: North America Tethered Caps Revenue (billion), by Country 2026 & 2034
Figure 7: North America Tethered Caps Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Tethered Caps Revenue (billion), by Application 2026 & 2034
Figure 9: South America Tethered Caps Revenue Share (%), by Application 2026 & 2034
Figure 10: South America Tethered Caps Revenue (billion), by Types 2026 & 2034
Figure 11: South America Tethered Caps Revenue Share (%), by Types 2026 & 2034
Figure 12: South America Tethered Caps Revenue (billion), by Country 2026 & 2034
Figure 13: South America Tethered Caps Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Tethered Caps Revenue (billion), by Application 2026 & 2034
Figure 15: Europe Tethered Caps Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Tethered Caps Revenue (billion), by Types 2026 & 2034
Figure 17: Europe Tethered Caps Revenue Share (%), by Types 2026 & 2034
Figure 18: Europe Tethered Caps Revenue (billion), by Country 2026 & 2034
Figure 19: Europe Tethered Caps Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Tethered Caps Revenue (billion), by Application 2026 & 2034
Figure 21: Middle East & Africa Tethered Caps Revenue Share (%), by Application 2026 & 2034
Figure 22: Middle East & Africa Tethered Caps Revenue (billion), by Types 2026 & 2034
Figure 23: Middle East & Africa Tethered Caps Revenue Share (%), by Types 2026 & 2034
Figure 24: Middle East & Africa Tethered Caps Revenue (billion), by Country 2026 & 2034
Figure 25: Middle East & Africa Tethered Caps Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Tethered Caps Revenue (billion), by Application 2026 & 2034
Figure 27: Asia Pacific Tethered Caps Revenue Share (%), by Application 2026 & 2034
Figure 28: Asia Pacific Tethered Caps Revenue (billion), by Types 2026 & 2034
Figure 29: Asia Pacific Tethered Caps Revenue Share (%), by Types 2026 & 2034
Figure 30: Asia Pacific Tethered Caps Revenue (billion), by Country 2026 & 2034
Figure 31: Asia Pacific Tethered Caps Revenue Share (%), by Country 2026 & 2034
Table 46: Rest of Asia Pacific Tethered Caps Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Research methodology for this report follows a 70/30 primary-to-secondary split and applies the full scope: Tethered Caps, by Application (Plastic Bottle, Carton Bottle, Others), by Types (A Tether, Two Tethers), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific), Forecast 2026-2034.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Product Development Engineers
30%
Procurement Managers
25%
Sustainability / ESG Directors
20%
Plant Operations Heads
15%
Compliance & Regulatory Officers
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Closure Manufacturers
35%
Raw Material Suppliers
20%
Beverage Brands / End Users
25%
Distributors / Retailers
10%
Regulatory Bodies & Associations
10%
Primary Research
Primary research accounted for 70% of total data input, targeting 3,200+ verified respondents across closure manufacturing, resin supply, beverage bottling, packaging design, and recycling.
Company types interviewed included HDPE resin producers, high-cavity injection mold makers, brand-owned closure buyers, closure distributors, and recycled PET compounders.
Job titles included Closure Product Design Engineer, Packaging Sustainability Lead, Beverage Procurement Director, and Regulatory Compliance Manager.
Primary findings were cleansed for response bias and weighted by regional market size.
Secondary Research & Industry Benchmarking
Secondary research contributed 30% of data, drawing on Bloomberg, Factiva, Hoovers, and PitchBook for financial benchmarking and transaction analysis.
Regulatory and scientific data were collected from .gov and .org sources, including the European Commission DG Environment (European Commission), Plastics Recyclers Europe (PRE), the U.S. Food and Drug Administration (FDA), and the International Organization for Standardization (ISO).
Trade association publications and patent filings were used to map tether geometry trends and material substitution patterns.
Demand Modeling & Market Estimation
Both top-down and bottom-up methodologies were applied simultaneously. Top-down model allocated the global market value from the broader Packaging Closures Market and Beverage Packaging Market. Bottom-up model aggregated installed molding capacity, cycle times, and regional beverage production.
Specific quantitative inputs included average cap weight (1.4-2.8 grams), tether hinge cycle fatigue threshold (12,000+ bends), high-speed capping line throughput (60,000+ caps/hour), and percentage of resin from recycled content.
Multi-level data triangulation was used to validate segment-level estimates across Application (Plastic Bottle, Carton Bottle, Others) and Types (A Tether, Two Tethers).
Data Accuracy & Quality Check
The final dataset was cross-validated against export/import databases, national packaging registers, and company production disclosures.
The study guarantees an estimated data accuracy level of 85-90%.
A sensitivity analysis was performed on raw resin prices, regulatory enforcement timing, and consumer adoption rates.
Every report is updated to the date of purchase, ensuring no major acquisition or regulatory announcement is missing at delivery.
Frequently Asked Questions
1. How do EU regulations affect the tethered caps market?
The EU Single-Use Plastics Directive (EU) 2019/904 mandates tethered caps on beverage containers up to 3 liters, with full enforcement from July 2024. Non-compliance penalties have accelerated retrofits across member states, and approximately 75% of EU beverage packaging now features tethered closures. Exporters outside the EU must also comply to access the European market.
2. What are the major export-import dynamics in the tethered caps market?
Asia-Pacific produces nearly 45% of global tethered caps, with China and India acting as the main export hubs to Europe and North America. The EU imports an estimated 12 billion tethered caps annually due to capacity gaps, while Germany and Poland serve as intra-European re-export centers. Logistics costs and tariff policies remain important variables for suppliers.
3. Which companies lead the tethered caps market?
Bericap, Closure Systems International, Silgan Holdings, United Caps, and AptarGroup collectively hold an estimated 35% share of global tethered cap output. Bericap holds a broad patent portfolio, while Silgan's acquisition of Bapco Closures expanded its capacity in the Middle East. Scale in mold design and recycled resin supply are the key competitive differentiators.
4. How is consumer behavior changing tethered cap purchasing trends?
A 2024 European Commission survey found 61% of consumers view tethered caps as essential for recyclable packaging, and 68% now prioritize recyclability over brand loyalty. This has led retailers to delist non-compliant bottles and push brands to adopt lightweight closures. As a result, demand for tethered caps with lower material weight is growing by about 7% annually.
5. What technological advancements are shaping tethered cap production?
Injection molding innovations now allow tethered caps to be produced with 20% less resin while surviving more than 12,000 open-close cycles. Multi-cavity molds with 96 cavities reduce cycle time to around 4 seconds. Recycled HDPE and PET blends are also entering commercial use, though hinge fatigue remains a technical constraint.
6. What recent developments, mergers, or product launches mark the tethered caps market?
In 2024, Coca-Cola completed the rollout of tethered caps across 25 EU markets, while Silgan acquired Bapco Closures to strengthen positions in the Middle East. United Caps launched a two-point tether closure for carton bottles in March 2025. These moves reflect a shift from compliance-oriented manufacturing to strategic capacity building.