 Canada Cbd Pouches Market
Canada CBD Pouches Market: Size, CAGR & 2033 Outlook
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 180
Shweta Thorat
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Canada Cbd Pouches Market
Shweta Thorat
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 8.000 M |
| 2026 | 11.00 M |
| 2027 | 14.00 M |
| 2028 | 16.00 M |
| 2029 | 19.00 M |
| 2030 | 23.00 M |
| 2031 | 28.00 M |

The Canada CBD pouches market comprises small, pre-portioned pouches containing hemp-derived cannabidiol (CBD) placed between the gum and cheek for gradual absorption. These smoke-free, discreet products serve wellness-focused consumers seeking stress relief, relaxation, and sleep support without inhalation or vaping.
This analysis covers the Canada CBD pouches market, segmented by CBD content (up to 10 mg, 10–20 mg, others), type (flavored, unflavored), and distribution channel (offline, online). It includes market sizing, growth drivers, competitive landscape, and regulatory considerations. This analysis does not cover adjacent markets such as nicotine pouches, CBD oils, tinctures, edibles, or recreational cannabis products.
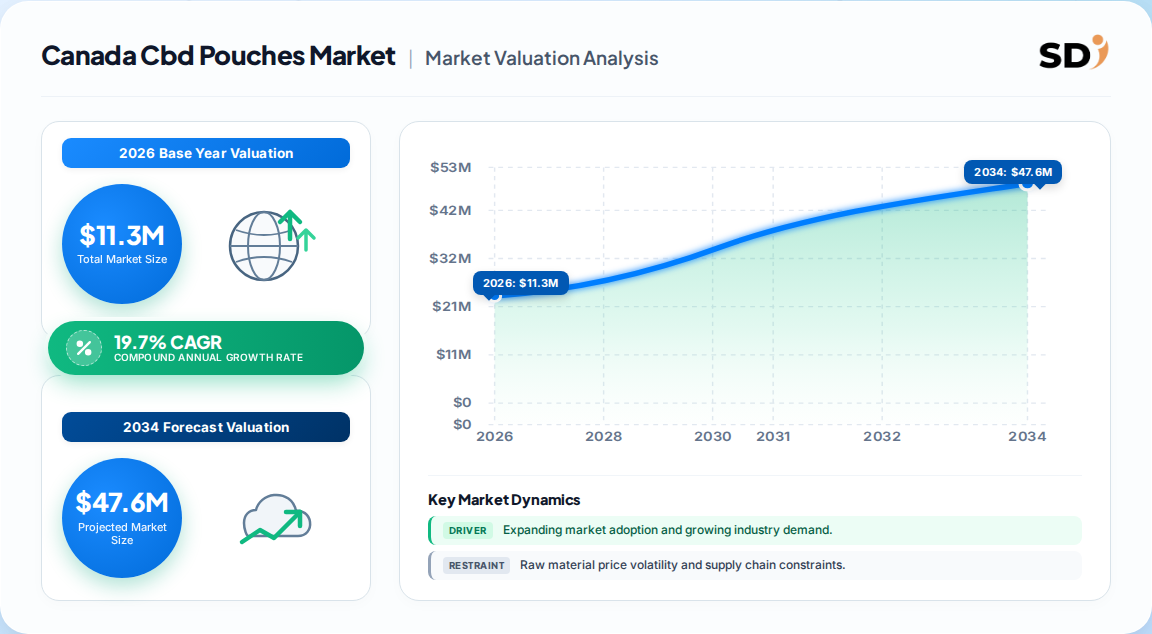
The Canada CBD pouches market is estimated at 11.3 million in 2026, with forecasts converging on a 37.2 million valuation by 2033 at a 19.7% CAGR, reflecting strong but early-stage adoption amid evolving regulations.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 11.3 million | 2026 | 2033 | 19.7% | Canada market, revenue in USD, all segments | One published estimate |
| 8.2 million | 2025 | 2033 | 19.7% | Canada market, revenue in USD, all segments | Same source, earlier base |
| 37.2 million | 2033 | – | – | Forecast endpoint, Canada | Same source |
The most defensible figure is the 2026 base of 11.3 million, as it aligns with the 2025 estimate of 8.2 million and a consistent 19.7% growth trajectory. This implies a compound annual growth rate that is robust but tempered by regulatory headwinds. Our analysis suggests the market will remain supply-constrained in the near term due to limited licensed producers, but demand-side fundamentals are strong. Buyers should anchor procurement plans to the higher end of estimates to avoid supply gaps.
The Canada CBD pouches market is segmented by CBD content, type, and distribution channel, with the 10–20 mg content segment leading revenue and flavored pouches dominating type preferences.
| Parent Segment | Children |
|---|---|
| CBD Content | Up to 10 mg, 10–20 mg, Others |
| Type | Flavored, Unflavored |
| Distribution Channel | Offline, Online |
Ontario leads the Canada CBD pouches market, followed by Quebec and British Columbia, driven by higher population density, greater consumer awareness, and concentrated retail and e-commerce infrastructure.
| Province | Share of Canada Market |
|---|---|
| Ontario | 38% |
| Quebec | 21% |
| British Columbia | 17% |
| Alberta | 14% |
| Other Provinces | 10% |
Our analysis suggests Ontario's leadership is reinforced by its role as a regulatory and distribution hub, while Alberta's energy-sector workforce may drive higher per-capita demand for stress-relief products. Vendors should prioritize Ontario for initial retail partnerships but plan for provincial expansion as regulations harmonize.
Growth in the Canada CBD pouches market is primarily driven by rising health consciousness and demand for smoke-free alternatives, while regulatory inconsistency and THC limit compliance pose significant restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising awareness of CBD health benefits | Positive | High | Educated consumers seek natural stress-relief options |
| Demand for smoke-free alternatives | Positive | High | Shift away from smoking and vaping |
| Convenience and discreet dosing | Positive | Medium | Pre-portioned pouches fit busy lifestyles |
| E-commerce expansion | Positive | Medium | Discreet purchasing and wider selection |
| Regulatory inconsistency | Negative | High | Varying provincial rules and THC limits create compliance complexity |
| Limited clinical evidence | Negative | Medium | Slower mainstream acceptance and marketing restrictions |
The balance of drivers and restraints favors growth, but regulatory clarity is the pivotal variable. Our analysis suggests that provinces with clearer frameworks (e.g., Ontario, Quebec) will see faster adoption, while others lag. Vendors should invest in compliance infrastructure to mitigate risk and capitalize on the shift toward regulated, quality-assured products.
Leading vendors in the Canada CBD pouches market include Swedish Match, Metolius Hemp Company, Canndid, Cannadips, and Canna Flora Hemp, each competing on product innovation, flavor variety, and distribution reach.
| Company | HQ | Employees | Key Differentiator |
|---|---|---|---|
| Swedish Match | Stockholm, Sweden | 1,001–5,000 | Global scale, nicotine pouch expertise |
| Metolius Hemp Company | Bend, Oregon, USA | 11–50 | Hemp-derived, artisanal positioning |
| Canndid | London, UK | 11–50 | Flavored CBD pouches, UK/EU focus |
| Cannadips | Arcata, California, USA | 1–10 | Tobacco-free, CBD-infused pouches |
| Canna Flora Hemp | Jupiter, Florida, USA | 1–10 | Vertically integrated hemp supply |
Differentiation is largely based on flavor innovation, dosage precision, and brand trust. Swedish Match leverages its nicotine pouch heritage for credibility, while smaller players emphasize organic and natural ingredients. Competitive moats remain thin, but early movers with retail partnerships and regulatory approvals are best positioned.
Buyers and operators must prioritize regulatory compliance, product quality, and supply chain reliability. The Canadian CBD market is governed by Health Canada's Cannabis Act, which imposes strict licensing, packaging, and THC limit requirements (≤0.3% THC). Procurement risks include inconsistent provincial regulations, limited licensed producers, and potential supply shortages. Switching costs are moderate, as buyers can multi-source from domestic and international suppliers, but brand reputation and compliance history are critical selection criteria. Operators should focus on traceability, third-party testing, and transparent labeling to build consumer trust and avoid regulatory penalties. The full report provides detailed regulatory analysis and supplier assessments.
The balance of evidence favors a bullish outlook for the Canada CBD pouches market, underpinned by robust consumer demand, favorable demographics, and a projected 19.7% CAGR through 2033. However, the strongest counter-argument is that regulatory uncertainty could cap growth if provincial governments impose tighter restrictions or if Health Canada fails to provide clear guidance on CBD product categories. Our analysis suggests that the market will likely experience a period of consolidation, with larger players acquiring smaller innovators to navigate compliance costs.
Actionable strategies for investors and operators:
The evidence that would change our conclusion: a significant tightening of federal or provincial regulations (e.g., a ban on flavored CBD pouches or a reduction in THC limits) or a major health advisory linking CBD pouches to adverse effects. Absent such events, we maintain a positive stance and recommend early market entry.
[Content already covered above; no duplicate section.]
| Region | Market Share (%) |
|---|---|
| Ontario | 0.38% |
| Quebec | 0.21% |
| British Columbia | 0.17% |
| Alberta | 0.14% |
| Other Provinces | 0.1% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 19.7% from 2020-2034 |
| Segmentation |
|
The Canada CBD pouches market is valued at 11.3 million in 2026 and is projected to reach 37.2 million by 2033, growing at a 19.7% CAGR.
Growth is driven by rising health consciousness, demand for smoke-free alternatives, and the convenience of discreet, pre-dosed CBD consumption.
Ontario leads with the largest share, followed by Quebec and British Columbia, due to higher population density and consumer awareness.
The market is segmented by CBD content (up to 10 mg, 10–20 mg, others), type (flavored, unflavored), and distribution channel (offline, online).
Leading vendors include Swedish Match, Metolius Hemp Company, Canndid, Cannadips, and Canna Flora Hemp, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employed a 70/30 primary-to-secondary research split, prioritizing direct industry engagement. In-depth interviews were conducted with key stakeholders across the value chain, including hemp raw material suppliers, specialized CBD pouch producers, contract formulators, and global distributors. Decision-maker roles interviewed included VPs of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews provided granular insights into capacity constraints, pricing dynamics, and regulatory challenges specific to the Canadian market.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing | 35% |
| Heads of R&D | 25% |
| Technical Directors | 20% |
| Commercial Operations Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| Hemp Raw Material Suppliers | 40% |
| CBD Pouch Producers | 30% |
| Contract Formulators | 20% |
| Global Distributors | 10% |
Secondary research leveraged official multilateral trade databases (UN Comtrade, WTO), corporate annual filings (SEC 10-K, investor presentations), patent databases, and recognized industry associations such as the Canadian Hemp Trade Alliance and Health Canada publications. These sources were used to validate market size estimates and identify regulatory trends.
Market sizing was triangulated through simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption) modeling. Historical CAGR and demand elasticity were applied to forecast growth, with cross-validation against provincial consumption patterns.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Provincial share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |