Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Flame Retardants Aerospace Plastics Market 2026 Outlook
Flame Retardants Aerospace Plastics Market 2026 Outlook
Flame Retardants Aerospace Plastics Market
Flame Retardants Aerospace Plastics Market 2026 Outlook
Flame Retardants Aerospace Plastics Market by Polymer Type (Epoxies, Polycarbonate, Thermoset Polyimide, ABS, CFRP, PEEK), by Product Type (Antimony Oxide, Aluminium Trihydrate, Magnesium Hydroxide, Organophosphates, Boron Compounds), by Flame Retardant Type (Metal Hydroxide, Phosphorus-based, Melamine-based, Boron Compounds), by Aircraft Component (Interior Panels & Floorings, Wiring & Cables, Fuselage, Engine Pylons, Access Doors, Wing Edges), by Aircraft Class (Heavy Aircraft, Military, General Aviation), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Taiwan), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (UAE, Turkey, Saudi Arabia, South Africa) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 226
USD 33.4 million — the 2024 global market for flame retardants dedicated to aerospace plastics, growing 6.9% annually to reach USD 57.2 million by 2032, per one published estimate.
Antimony oxide led product demand with ~36.6% share in 2025, while phosphorus-based chemistries are the fastest-growing product family at roughly 4.0% CAGR.
Carbon-fibre-reinforced polymer (CFRP) accounts for ~40.9% of polymer-type consumption; interior panels and floorings captured ~52.4% of component demand.
North America holds ~35.3% of global value, Europe ~32%, and Asia-Pacific is the fastest-growing region at approximately 3.9% CAGR through 2031.
Leading vendors include Clariant, BASF, LANXESS, DuPont, Huber Engineered Materials, Albemarle and Budenheim, with halogen-free reformulation now the principal competitive axis.
Regulatory tightening (FAR 25.853 revisions, EASA halon guidance) and China's September 2024 antimony trioxide export curbs are the two forces most likely to reprice the market before 2028.
Why this matters for decision-makers: qualification cycles of 2–3 years mean procurement teams that lock in halogen-free, antimony-light formulations now will avoid a structural supply and compliance squeeze after 2027.
Flame Retardants Aerospace Plastics Market Size (In Million)
40.0M
30.0M
20.0M
10.0M
0
33.00 M
2024
34.00 M
2025
35.00 M
2026
36.00 M
2027
37.00 M
2028
38.00 M
2029
39.00 M
2030
Flame Retardants Aerospace Plastics Market Size (In Million)
Year
Market Size
2024
33.00 M
2025
34.00 M
2026
35.00 M
2027
36.00 M
2028
37.00 M
2029
38.00 M
2030
39.00 M
What is the Flame Retardants Aerospace Plastics Market?
Flame retardants for aerospace plastics are additive chemistries — antimony oxide, aluminium trihydrate, phosphorus and boron compounds — formulated into aircraft polymers such as epoxy, polycarbonate, thermoset polyimide and CFRP to meet cabin and structural fire-safety standards. The market measures additive value consumed by aerospace plastics converters and OEM tier suppliers.
Scope: what this report covers and excludes
This analysis covers flame-retardant additives consumed in aerospace-grade plastics across interior components, fuselage, flooring, engine pylons, access doors and wing edges, for heavy, military and general aviation aircraft. It measures additive value, not finished plastic or composite value. This analysis does not cover general industrial flame-retardant plastics, construction or electronics applications, nor non-aerospace composite markets.
How big is the market for Flame Retardants Aerospace Plastics Market?
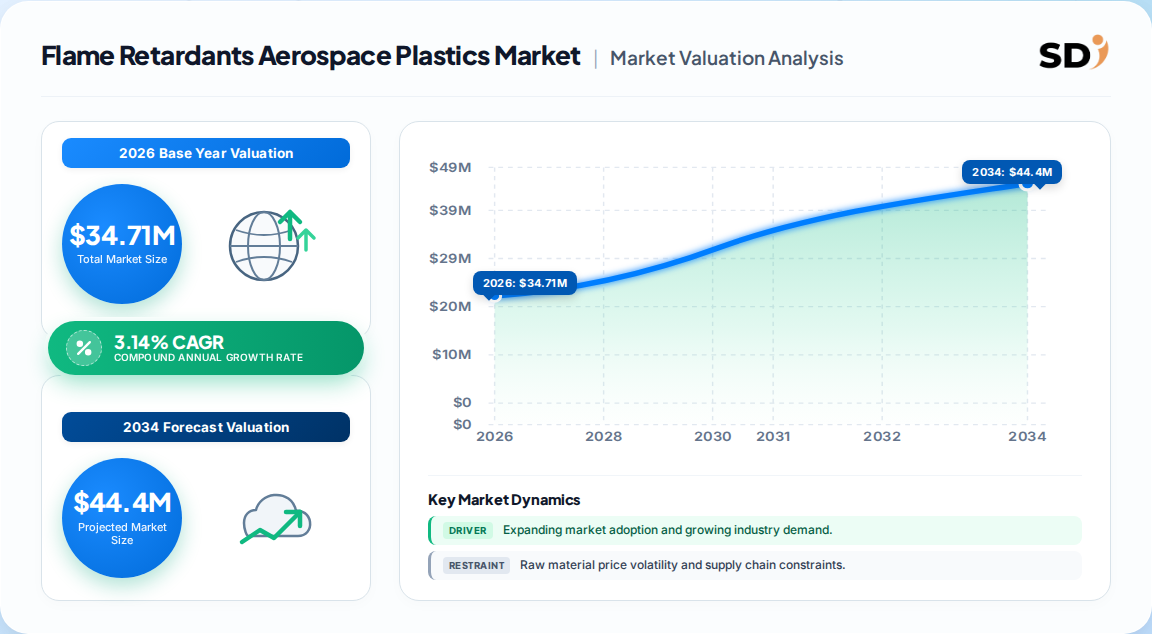
Estimates cluster tightly around USD 33–35 million for 2024–2026, but forecast CAGRs diverge sharply — from 2.99% to 6.9% — largely because publishers use different base years and different definitions of what counts as an aerospace plastic additive.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 33.4 million
2024
2032
6.9%
Additives for aerospace plastics, all platforms
One published estimate
USD 34.41 million
2025
2034
2.99%
Additive value, segmented by polymer and aircraft type
A competing analysis
USD 33.65 million
2025
2031
3.14%
Additives by product, polymer, aircraft component
A competing analysis
Our analysis suggests the 3.0–3.1% range is more defensible for near-term planning: it is corroborated by two independent publishers and aligns with 2–3 year qualification drag and modest aircraft build-rate growth. The 6.9% figure likely reflects a narrower base year or a more aggressive composite-adoption assumption. Buyers should plan on the conservative case and treat upside as option value.
How is the market segmented?
Segmentation is best understood along four non-geographic axes — polymer type, product chemistry, aircraft component and aircraft class — because each carries different qualification, pricing and regulatory risk.
Which region leads in Flame Retardants Aerospace Plastics Market?
North America leads with roughly 35% of global value, narrowly ahead of Europe at ~32%, but Asia-Pacific is the fastest-growing region at approximately 3.9% CAGR — a gap that will narrow the lead over the forecast horizon.
Asia-Pacific — China, Japan, India, South Korea, Taiwan
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — UAE, Turkey, Saudi Arabia, South Africa
The regional split is less about aircraft demand than about where formulation and qualification sit. Europe's share is anchored by Airbus's multi-country manufacturing footprint, while North America's reflects Boeing's build rates and a dense tier-supplier base. Our analysis suggests Asia-Pacific's growth premium is a composite-fabrication story, not yet an additive-innovation story — meaning regional volume gains may not translate into regional margin gains.
What is driving growth — and what is holding it back?
Stringent fire-safety regulation is the single largest growth driver, adding roughly 0.8 percentage points to CAGR, followed by rising aircraft production and the shift to lightweight composite airframes. The main drags are antimony supply concentration and toxicological scrutiny of legacy brominated systems.
Factor
Direction
Evidence strength
Mechanism
Stricter cabin/structural fire tests
Driver
High
More additive loading per part to pass heat-release and smoke criteria
Aircraft build-rate recovery
Driver
High
Boeing 737 at 38/month; 787 rising toward 7/month
Lightweight composite airframes
Driver
Medium-high
20–30% weight savings vs aluminium raise additive content per airframe
Halogen-free transition
Driver
Medium
Phosphorus and metal-hydrate reformulation creates replacement demand
Antimony oxide price/supply risk
Restraint
High
China export curbs on antimony trioxide reset raw-material economics
Substitute materials reduce flame-retardant need in some structures
The balance favors growth but not uniform growth. Volume rises with airframe counts and composite content; value is being redistributed away from halogenated antimony-heavy systems toward phosphorus, nitrogen and metal-hydrate packages. The second-order effect is margin compression for suppliers who cannot reformulate, and pricing power for those who can.
Who are the leading vendors?
Clariant, BASF, LANXESS, DuPont, Huber Engineered Materials, Albemarle and Budenheim are the most frequently cited suppliers, with Clariant the most active on halogen-free capacity expansion in the 2025–2026 period.
Company
Known positioning
Notable signal
Clariant
Halogen-free Exolit OP portfolio
Daya Bay expansion and FUHUA JV for halogen-free capacity
BASF
Broad additive portfolio
Aerospace-qualified flame-retardant systems
LANXESS
Phosphorus-based flame retardants
Automotive and aerospace fire safety
DuPont
High-performance polymer additives
Legacy aerospace specification positions
Huber Engineered Materials
Aluminium trihydrate and mineral fillers
Cost-competitive metal-hydroxide supply
Albemarle
Brominated chemistries
Strong position but exposed to regulatory exit risk
Budenheim
Phosphorus and specialty additives
Niche high-performance formulations
The competitive moat is not chemistry IP alone — it is qualification. Once an additive is written into an OEM specification, switching costs are high and cycles are long. That protects incumbents but slows halogen-free substitution, which is precisely where challengers can win share by pre-qualifying with tier suppliers.
What do buyers and operators need to know? (Decision Support)
Selection criteria should weight qualification status above unit price. An additive that is 15% cheaper but requires a fresh 24–36 month qualification is more expensive in program terms. Buyers should confirm that the formulation is already referenced in an OEM- or tier-level specification before negotiating.
Procurement risk is concentrated in antimony. China's September 2024 export curbs on antimony trioxide have made single-source dependency a material program risk. Operators should model a dual-sourcing scenario across antimony and aluminium trihydrate or phosphorus alternatives, and stress-test cost pass-through.
Regulatory compliance is a moving target. FAA heat-release criteria for transport-category aircraft and EASA halon-replacement timelines indirectly raise the bar for interior plastics. OEMs increasingly design to the most demanding global rule set, so a formulation compliant in one region may not travel. Switching costs are therefore high and rising.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the conservative 3.0–3.1% CAGR case for volume planning, with meaningful upside optionality from composite adoption and halogen-free replacement. The strongest counter-argument is that accelerated composite content in narrow-body replacements could push growth toward the 6.9% figure — but qualification drag makes that unlikely to materialize before 2029.
Our analysis suggests the market's real story is mix shift, not headline growth. Value is migrating from antimony-heavy halogenated systems to phosphorus, nitrogen and metal-hydrate packages, and from commodity additive supply to specification-locked supply. Suppliers who treat halogen-free reformulation as a compliance cost will lose share; those who treat it as a pre-qualification land-grab will win the next specification cycle.
Actionable Strategy
Investors: favor suppliers with already-qualified halogen-free portfolios and multi-region manufacturing over brominated-heavy incumbents.
Operators: dual-source antimony and lock in phosphorus or ATH alternatives before 2028 to de-risk export-curb exposure.
Tier suppliers: begin qualification of PFAS-free, halogen-free systems now — the 2–3 year cycle means decisions made in 2026 determine 2029 specification positions.
What would change our conclusion: a step-change in CFRP content per airframe, or a faster-than-expected regulatory ban on brominated systems, would justify revising the growth outlook upward toward the higher published CAGR.
1. How big is the flame retardants for aerospace plastics market?
The market was valued at approximately USD 33.4 million in 2024 and is projected to reach USD 57.2 million by 2032, growing at around 6.9% CAGR according to one published estimate. Conservative estimates place growth nearer 3% annually.
2. Which region dominates the flame retardants for aerospace plastics market?
North America leads with roughly 35% of global value, followed closely by Europe at about 32%, anchored by Boeing and Airbus supply chains respectively. Asia-Pacific is the fastest-growing region at approximately 3.9% CAGR.
3. What are the key drivers of the flame retardants for aerospace plastics market?
Stringent fire-safety regulations for cabin and structural plastics, rising aircraft production rates, and the shift toward lightweight composite airframes are the primary drivers. The transition to halogen-free chemistries is creating additional replacement demand.
4. Who are the leading companies in the flame retardants for aerospace plastics market?
Clariant, BASF, LANXESS, DuPont, Huber Engineered Materials, Albemarle and Budenheim are the most frequently cited suppliers, with Clariant notably expanding halogen-free capacity at its Daya Bay facility in 2025 and 2026.
5. What is the biggest risk in the flame retardants for aerospace plastics market?
Antimony oxide supply concentration and China's September 2024 export curbs represent the most acute near-term risk, compounded by toxicological scrutiny of legacy brominated systems that is accelerating the shift toward phosphorus and metal-hydrate alternatives.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split, prioritizing direct industry engagement over desk research. In-depth interviews were conducted with stakeholders across the value chain, including raw material and antimony suppliers, specialized flame-retardant formulators, contract blenders serving aerospace tier suppliers, and global specialty chemical distributors. Interviewees were drawn from decision-maker designations including VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring both technical and commercial perspectives inform the dataset.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
40%
Procurement & Sourcing Directors
35%
Quality & Regulatory Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Chemical Producers
45%
Formulators & Blenders
35%
Distributors & Traders
20%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade and standards databases including UN Comtrade, WTO tariff schedules, US ITC trade data and Eurostat chemical trade flows. Corporate annual filings (10-K, SEC submissions, investor presentations), patent databases, and recognized non-profit technical standards bodies and industry associations were reviewed to benchmark capacity, pricing and specification trends.
Demand Modeling & Market Sizing Triangulation
We triangulate simultaneously via a Top-Down approach — allocating macroeconomic and aerospace segment output to flame-retardant intensity — and a Bottom-Up approach modeling manufacturer capacity, product pricing and end-use consumption by polymer and component type. Divergences between the two are reconciled through expert review.
 Flame Retardants Aerospace Plastics Market