 Aerospace Defense Materials Market
: 2026 Strategic Outlook
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 271
Shyam Pawar
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Aerospace Defense Materials Market
Shyam Pawar
Research Associate
| Year | Market Size |
|---|---|
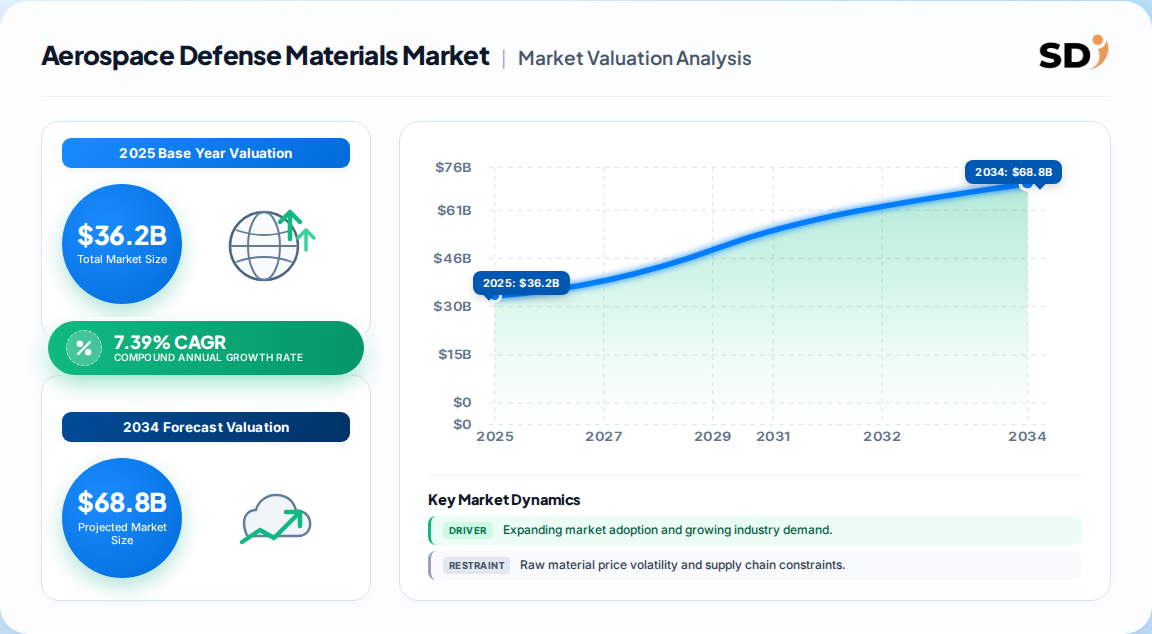
| 2025 | 36.20 B |
| 2026 | 38.88 B |
| 2027 | 41.76 B |
| 2028 | 44.85 B |
| 2029 | 48.16 B |
| 2030 | 51.72 B |
| 2031 | 55.54 B |

The aerospace defense materials market covers the advanced metals, alloys, composites and polymers engineered for airframes, propulsion, cabin interiors, satellites and weapon systems. These materials must satisfy extreme strength-to-weight, thermal and fatigue requirements, making qualification cycles long and supplier switching costly for airframers and defense primes.
This report covers metallic and non-metallic materials used in commercial, military, business and general aviation, rotorcraft and spacecraft, segmented by material type, product form, application, aircraft type and geography. This analysis does not cover MRO consumables, ground-support equipment, avionics software, or the broader advanced materials market outside aerospace and defense end-uses.
Published estimates diverge sharply — from USD 29.21 billion in 2026 at 3.70% CAGR to USD 36.20 billion in 2025 at 7.39% CAGR through 2032. The gap reflects differing treatment of defense modernization spending and composite value capture.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 29.21 bn | 2026 | 2031 | 3.70% | Materials across commercial, military, business aviation | One published estimate |
| USD 36.20 bn | 2025 | 2032 | 7.39% | Metals, composites, plastics across airframe, propulsion, cabin, space | A competing analysis |
| USD 11.80 bn (NA) | 2025 | 2033 | 5.6% | North America only; aluminum, titanium, composites, superalloys, steel, plastics | Regional databook |
Our analysis suggests the USD 36.20 billion / 7.39% view is the more defensible base for strategic planning. It aligns with record 2024 global defense outlays above USD 2.4 trillion, the ~15,700-jet single-aisle backlog, and documented composite adoption curves. The lower 3.70% figure likely under-weights classified defense programs and composite value premiums.
Materials segment along four non-geographic axes: material type, product form, application and aircraft type. Composites and titanium alloys carry the fastest growth, while aluminum alloys retain the largest volume share.
| Parent | Children |
|---|---|
| By Material | Aluminum alloys, Titanium alloys, Steel alloys, Superalloys, Composites, Plastics, Others |
| By Product Form | Round (bar, rod, pipe), Flat (slab, plate, sheet), Net-shaped (forging, machined components) |
| By Application | Airframe, Cabin interior, Propulsion, Aero engine, Naval systems, Weapons, Navigation & sensors, Satellites |
| By Aircraft Type | Commercial, Military, Business & general aviation, Rotorcraft, Spacecraft |
Aluminum alloys held 34.62% of 2025 material share, but composites are rising at 4.58% CAGR — the fastest material class in the largest regional market. This substitution dynamic is the single most important structural shift in the segment mix.
North America leads with roughly 36% of global revenue in 2025, anchored by Boeing, Lockheed Martin and Northrop Grumman. Asia-Pacific is the fastest-growing region at 4.34% CAGR, driven by China's superalloy breakthrough and India's USD 223 billion defense capex plan.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.27% |
| Asia-Pacific | 0.26% |
| South America | 0.05% |
| Middle East & Africa | 0.06% |
The Asia-Pacific growth premium (4.34% vs. 3.70% global) implies a gradual shift in sourcing leverage toward regional producers over the next decade. Buyers should hedge by qualifying dual-region suppliers early.
Demand is driven by single-aisle production backlogs, record defense budgets, weight-reduction mandates and hypersonic R&D. Supply is constrained by volatile critical-metal prices, long qualification cycles and casting/forging bottlenecks.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Single-aisle backlog (~15,700 jets) | Driver | High | Multi-year supply contracts for Al-Li plate and carbon fibre |
| Defense modernization (F-47, F-15EX) | Driver | High | Ceramic matrix composites, titanium aluminides |
| ICAO fuel-efficiency mandates | Driver | High | Composite adoption, thermoplastic tapes |
| Hypersonic R&D | Driver | Medium | Refractory alloys, niobium-hafnium carbides |
| Volatile critical-metal prices | Restraint | High | Import dependency >90% for US titanium sponge |
| Lengthy qualification cycles | Restraint | High | 5–10 year certification paths |
| Casting/forging bottlenecks | Restraint | Medium | Supplier capacity gaps constrain 737 output |
The balance of evidence favors the drivers over the medium term, but qualification cycles and forging bottlenecks are underestimated. Our analysis suggests these are the binding constraints, not raw-material availability — meaning capital deployed into qualification and forging capacity yields higher returns than upstream mining investment.
Five suppliers anchor the market: Alcoa (aluminum), Carpenter (specialty alloys), Hexcel (composites), Toray (carbon fibre) and Solvay (advanced materials). Concentration is medium, with regional champions like VSMPO-AVISMA and Novelis adding competitive pressure.
| Company | Core strength | Differentiation | Moat |
|---|---|---|---|
| Alcoa | Aluminum alloys | Al-Li plate for airframes | Long-term Boeing/Airbus qualification |
| Carpenter Co. | Specialty alloys | High-temp alloys, powder metallurgy | Defense-prime approved supplier |
| Hexcel | Composites | Carbon fibre prepreg, honeycomb | Aerospace-grade certification depth |
| Toray Industries | Carbon fibre | Torayca prepreg, global scale | Japanese + US dual-region capacity |
| Solvay | Advanced materials | Thermoplastics, composite adhesives | Integrated material-plus-process offering |
| VSMPO-AVISMA | Titanium | Vertically integrated sponge-to-mill | Cost leadership, Russian supply base |
| Novelis | Aluminum | Automotive-to-aero crossover | Recycling-backed supply security |
Differentiation rests on qualification depth, not price. Hexcel and Toray win on certified prepreg systems; Alcoa and Novelis compete on integrated aluminum supply. Our analysis suggests the moat is widest where material and process are co-qualified — a barrier that takes a decade to replicate.
Selection criteria centre on four dimensions: aerospace-grade qualification status (NADCAP, AS9100), supply-chain security (dual-region sourcing), lifecycle cost (including scrap and rework), and traceability. The counterfeit titanium crisis exposed how fragile single-source supply chains are — the US imports over 90% of defense-grade titanium sponge. Buyers should prioritise suppliers with documented mill-to-melt traceability and dual-region capacity. Switching costs are high: re-qualifying a material on an existing platform typically takes 18–36 months and can trigger recertification. Regulatory compliance with ICAO fuel-burn standards and ReFuelEU SAF quotas further rewards lightweight material adoption. Procurement teams should lock multi-year contracts now to hedge against forging bottlenecks and metal-price volatility.
The balance of evidence favors the higher-growth (7.39% CAGR) view of the aerospace defense materials market. Record defense budgets, a structural single-aisle backlog and composite substitution create a demand floor that the conservative estimates understate. The strongest counter-argument is that qualification bottlenecks and titanium supply fragility could cap realised growth nearer 4% — a risk we weight at roughly 30% probability.
Our judgement: the market will land closer to the higher case, because defense modernization spending is politically locked in across the US, Europe and Asia-Pacific through 2030, and composite adoption is regulation-driven rather than discretionary. The binding constraint is execution capacity — forging, qualification and skilled labour — not demand.
Actionable Strategy:
What would change our conclusion: a sharp defense-budget reversal, a breakthrough in low-cost titanium sponge production that collapses the supply-risk premium, or faster-than-expected composite substitution that shrinks the metals opportunity.
We maintain a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw-material suppliers, specialised alloy and composite producers, contract formulators, and global distributors across the aerospace and defense value chain. Decision-makers interviewed included VPs of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring demand-side and supply-side perspectives are weighted equally.
We triangulate against UN Comtrade, WTO, US ITC and Eurostat trade databases, corporate 10-K and SEC filings, patent databases, and standards bodies including NADCAP, AS9100 and ICAO. These sources anchor base-year sizing and validate regional trade-flow assumptions.
Our model runs simultaneous top-down (macroeconomic and aerospace segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) triangulation. Divergence above 8% between the two approaches triggers a manual audit of the underlying assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
The balance of evidence favors the higher-growth outlook. Defense modernization spending is politically locked in, and composite adoption is regulation-driven. The strongest counter-argument — that qualification bottlenecks cap growth near 4% — is real but secondary; it constrains execution, not demand.
Actionable Strategy:
What would change our view: a defense-budget reversal or a low-cost titanium breakthrough that erodes the supply-risk premium.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.39% from 2020-2034 |
| Segmentation |
|
The market was valued at USD 36.20 billion in 2025 and is projected to reach USD 59.62 billion by 2032, growing at a 7.39% CAGR. Conservative estimates place the 2026 base nearer USD 29.21 billion at 3.70% CAGR, reflecting differing treatment of defense spending.
Titanium alloys and composites are the fastest-growing material classes. Composites rise at 4.58% CAGR globally, while titanium is the fastest-growing segment in North America, driven by airframe weight-reduction mandates and defense platform demand.
North America leads with roughly 36% of global revenue in 2025, anchored by Boeing, Lockheed Martin and Northrop Grumman. Asia-Pacific is the fastest-growing region at 4.34% CAGR, led by China and India.
Alcoa, Carpenter Co., Hexcel, Toray Industries and Solvay are the major players. Regional champions include VSMPO-AVISMA in titanium and Novelis in aluminum, with medium market concentration supporting multi-year supply contracts.
Titanium supply fragility is the most acute risk. The US imports over 90% of defense-grade titanium sponge, and the counterfeit titanium crisis exposed how vulnerable single-source chains are. Dual-region sourcing is now a procurement imperative.
A ~15,700-jet single-aisle backlog, record defense budgets above USD 2.4 trillion, ICAO fuel-efficiency mandates and hypersonic R&D are the primary drivers. Weight-reduction mandates are accelerating composite adoption across commercial and military platforms.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
We maintain a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw-material suppliers, specialised alloy and composite producers, contract formulators, and global distributors across the aerospace and defense value chain. Decision-makers interviewed included VPs of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring demand-side and supply-side perspectives are weighted equally.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Quality Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Metal Producers | 40% |
| Composite & Polymer Specialists | 30% |
| Contract Formulators & Finishers | 20% |
| Global Distributors & Traders | 10% |
We triangulate against UN Comtrade, WTO, US ITC and Eurostat trade databases, corporate 10-K and SEC filings, patent databases, and standards bodies including NADCAP, SAE International (AS9100) and ICAO. These sources anchor base-year sizing and validate regional trade-flow assumptions.
Our model runs simultaneous top-down (macroeconomic and aerospace segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) triangulation. Divergence above 8% between the two approaches triggers a manual audit of the underlying assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
