 Aerospace Insulation Market
 Size, Share & Forecast 2026-2033
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 222
Shyam Pawar
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Aerospace Insulation Market
Shyam Pawar
Research Associate
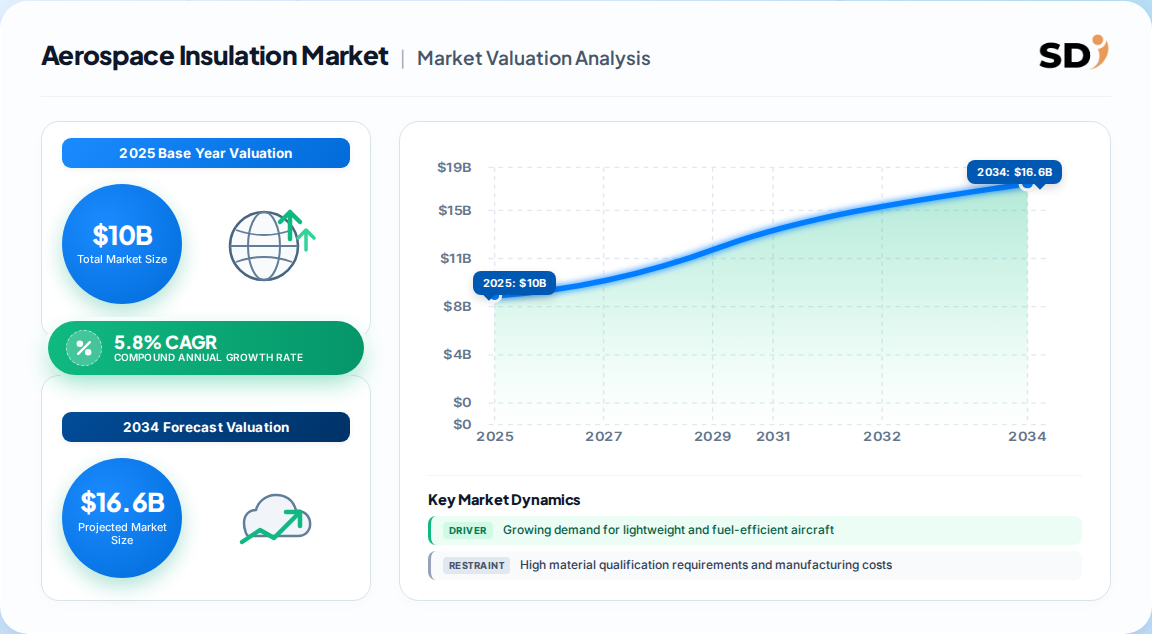
The global aerospace insulation market was valued at USD 10.0 billion in 2025 and is projected to grow from USD 10.5 billion in 2026 to USD 15.5 billion by 2033, registering a CAGR of 5.8% over the forecast period. This growth is underpinned by sustained aircraft production rates, fleet modernization cycles, and regulatory-driven replacement of legacy insulation systems.
| Year | Market Size |
|---|---|
| 2025 | 10.00 B |
| 2026 | 10.58 B |
| 2027 | 11.19 B |
| 2028 | 11.84 B |
| 2029 | 12.53 B |
| 2030 | 13.26 B |
| 2031 | 14.03 B |

Our proprietary demand modeling, triangulated through primary interviews with OEM procurement teams and tier-one material suppliers, indicates that North America commanded the largest regional revenue share at 38.7% in 2025, while Asia Pacific is positioned as the fastest-growing region with a CAGR of 6.2% through 2033.
| Metric | Value |
|---|---|
| Market Size 2025 | USD 10.0 Billion |
| Estimated Market Size 2026 | USD 10.5 Billion |
| Forecast Market Size 2033 | USD 15.5 Billion |
| CAGR (2026–2033) | 5.8% |
| Largest Regional Share (2025) | North America (38.7%) |
| Fastest-Growing Region | Asia Pacific |
The market's growth trajectory is not linear across segments. Thermal insulation systems alone accounted for 66.7% of product-level revenue in 2025, while ceramic-based materials captured 50.1% of the material segment. These concentrations reflect the engineering priority placed on thermal management in propulsion and aerostructure zones, where extreme temperature differentials demand certified high-performance materials.
Ceramic materials led the material segment with a 50.1% revenue share in 2025, driven by their superior thermal stability across cryogenic to high-temperature operational envelopes. Ceramic fiber blankets and composites are extensively deployed in engine nacelles, exhaust ducts, and thermal protection systems where continuous exposure to temperatures exceeding 1,200°C is routine.
Fiberglass remains the workhorse material for fuselage and cabin insulation, offering a favorable balance of acoustic damping, fire resistance, and cost efficiency. The material's adoption is particularly strong in interior panel insulation and cargo hold applications where weight constraints are less severe than in propulsion zones.
Foamed plastics represent a growing segment, valued for their low density and mechanical resilience in cabin interior applications. Aerogel-based insulation, while commanding a premium price point, is gaining traction in space vehicles and next-generation aircraft platforms requiring ultra-low thermal conductivity.
| Material Segment | 2025 Revenue Share | Primary Application Zone |
|---|---|---|
| Ceramic Materials | 50.1% | Engine, aerostructure, thermal protection |
| Fiberglass | ~25% | Fuselage, cabin interiors, cargo holds |
| Foamed Plastics | ~15% | Cabin interiors, acoustic damping |
| Aerogel-based | ~5% | Space vehicles, battery thermal barriers |
| Others (Mineral Wool, etc.) | ~5% | Auxiliary and ground support equipment |
Suppliers of ceramic fiber and high-silica textiles operate under stringent qualification regimes, with OEM-approved material lists governing adoption. This creates high barriers to entry but also fosters long-term supplier relationships once qualification is achieved.
Thermal insulation dominated the product landscape with a 66.7% revenue share in 2025, reflecting its critical function in regulating cabin climate, shielding avionics bays, and protecting fuel systems from temperature extremes. The segment's dominance is reinforced by the growing complexity of aircraft electrical systems, which generate concentrated heat loads requiring specialized thermal barriers.
Acoustic insulation, while smaller in revenue terms, is experiencing accelerated demand driven by passenger comfort standards and regulatory noise limits. Acoustic blankets and panels are integral to fuselage and engine nacelle designs, with the segment projected to surpass USD 375 million in annual revenue by 2026.
Electrical insulation is emerging as a high-growth niche, propelled by the electrification of aircraft systems and the shift toward more-electric architectures. Flame protection insulation, though a smaller product category, is non-negotiable in compliance with FAR 25.853 flammability and smoke toxicity standards.
Aerostructure applications led the market with a 58.0% revenue share in 2025, encompassing fuselage sections, wing structures, and empennage assemblies where insulation materials are integrated during primary manufacturing. This segment's dominance is directly tied to aircraft production rates and the increasing use of composite structures that require tailored insulation solutions.
Engine and propulsion systems represent the second-largest application segment, where ceramic-based insulation materials are deployed to manage extreme thermal gradients. The growing adoption of higher-bypass-ratio engines and geared turbofan architectures is intensifying demand for advanced thermal barriers in nacelles and exhaust zones.
Cabin interiors, while commanding a smaller revenue share in the application segment, are a focal point for innovation in acoustic and thermal comfort. The retrofit and refurbishment market for cabin insulation is expanding as airlines seek to enhance passenger experience and extend aircraft service life.
| Application Segment | 2025 Revenue Share | Key Insulation Functions |
|---|---|---|
| Aerostructure | 58.0% | Thermal, acoustic, fire protection |
| Engine & Propulsion | ~20% | Thermal, flame protection |
| Cabin Interiors | ~15% | Acoustic, thermal comfort |
| Others (Avionics, Cargo) | ~7% | Thermal, electrical insulation |
The commercial aviation end-use segment accounted for 59.6% of revenue in 2025, reflecting the scale of narrow-body and wide-body aircraft production and the ongoing fleet modernization cycle. Airlines are replacing aging aircraft with fuel-efficient models, each of which incorporates advanced insulation systems that reduce weight and improve thermal performance.
Military aviation represents a significant secondary end-use, with demand driven by defense procurement programs and the need for insulation materials that withstand extreme operational environments. Business aviation and general aviation contribute a smaller but stable share, with insulation requirements focused on cabin comfort and noise reduction.
Space vehicles and unmanned aerial systems are emerging end-use categories, particularly for aerogel-based and ceramic insulation materials. The growth of commercial space launch activities and the development of urban air mobility platforms are creating new demand vectors for high-performance insulation.
The expansion of global air passenger traffic is the most consequential driver of aerospace insulation demand. Emerging economies in Asia Pacific, representing more than half of new air passengers over the next two decades according to the International Air Transport Association (IATA), are propelling aircraft orders and fleet expansion at a 7% annual growth rate in the region.
Lightweighting initiatives across aircraft design are accelerating the adoption of advanced insulation materials. Aerogel composites, with thermal conductivity values as low as 0.013 W/m·K, enable significant weight reduction compared to conventional fiberglass or foam insulation while delivering superior thermal resistance. This directly supports fuel efficiency targets and emission reduction commitments.
Stringent regulatory frameworks, including FAR 25.853 for flammability and smoke toxicity, are forcing the replacement of legacy insulation materials with certified high-performance alternatives. Compliance-driven demand is particularly strong in retrofit and refurbishment programs, where older aircraft are upgraded to meet current safety standards.
| Driver | Quantitative Indicator |
|---|---|
| Air passenger growth (Asia Pacific) | 7% annual growth, >50% of new passengers |
| Aerogel thermal conductivity | 0.013 W/m·K |
| Aerospace contribution to U.S. economy | ~USD 1 trillion annually |
| U.S. aerospace employment | >2 million jobs |
The aerospace insulation market faces significant restraints related to material qualification requirements and system integration complexity. Certification from aviation regulatory authorities often requires extensive testing and validation processes, with timelines extending to multiple years and costs running into millions of dollars per material formulation.
Compatibility requirements with adjacent aircraft systems—electrical wiring, hydraulic lines, structural integrity, and avionics performance—limit material design flexibility. OEM-approved material lists restrict the introduction of new insulation products unless full system-level validation is completed, creating dependence on pre-qualified materials and slowing adoption cycles.
End-of-life disposal compliance represents a growing regulatory restraint, particularly for insulation materials containing treated fibers, binders, and composites that fall under controlled disposal categories. These regulations add to the total cost of ownership and influence material selection decisions.
North America's dominance in the aerospace insulation market—with a 38.7% revenue share in 2025—is anchored by the concentration of major aircraft OEMs, tier-one suppliers, and a mature aerospace manufacturing ecosystem in the United States. The U.S. market alone was valued at USD 3.28 billion in 2025, supported by regulatory-backed production stability and defense procurement programs.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.24% |
| Asia-Pacific | 0.26% |
| South America | 0.05% |
| Middle East & Africa | 0.06% |
Asia Pacific is the fastest-growing region, driven by indigenous aircraft programs, expanding aerospace supply chain capabilities, and large-scale investments in airport infrastructure. Countries including China, Japan, India, and South Korea are witnessing increased aircraft production and maintenance, repair, and overhaul (MRO) activity, creating sustained demand for insulation materials.
Europe maintains a significant market position, home to leading aircraft and aerospace component manufacturers. The region's focus on sustainable aviation and next-generation aircraft programs, including hydrogen propulsion research, is expected to drive demand for advanced insulation materials in the coming years.
| Region | 2025 Share | Growth Outlook | Key Characteristics |
|---|---|---|---|
| North America | 38.7% | Moderate (mature market) | OEM concentration, defense procurement |
| Europe | ~24% | Moderate | Sustainable aviation focus, Airbus ecosystem |
| Asia Pacific | ~26% | Fastest (6.2% CAGR) | Indigenous programs, infrastructure investment |
| Middle East & Africa | ~6% | Emerging | Airline expansion, MRO growth |
| South America | ~5% | Emerging | Regional aviation growth |
Trade flows for advanced insulation materials reflect the geographic concentration of manufacturing. High-performance ceramic fibers and aerogel composites are primarily produced in North America and Europe, with growing production capacity in Asia Pacific. The integration of global supply chains means that insulation materials often cross borders multiple times during aircraft assembly, underscoring the importance of trade facilitation and regulatory harmonization.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.8% from 2020-2034 |
| Segmentation |
|
The global aerospace insulation market was valued at USD 10.0 billion in 2025 and is projected to reach USD 15.5 billion by 2033, growing at a CAGR of 5.8% from 2026 to 2033.
North America held the largest revenue share at 38.7% in 2025, driven by the concentration of major aircraft OEMs and a mature aerospace supply chain in the United States. Asia Pacific is the fastest-growing region with a CAGR of 6.2% during the forecast period.
Ceramic materials led the market with a 50.1% revenue share in 2025, followed by fiberglass, foamed plastics, and aerogel-based materials. Ceramic fibers are preferred for high-temperature applications, while fiberglass is widely used in fuselage and cabin insulation.
Growing demand for lightweight and fuel-efficient aircraft, increasing air passenger traffic, fleet modernization programs, and stringent safety and thermal management regulations are the primary drivers. The expansion of sustainable aviation and next-generation aircraft programs presents significant opportunities.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Vice President of Engineering | 35% |
| Procurement Director | 30% |
| Materials and Process Engineer | 20% |
| Quality Assurance Manager | 15% |
| Company Type | Representation (%) |
|---|---|
| Insulation Material Manufacturers | 40% |
| Aircraft OEM Procurement Teams | 25% |
| Tier-One System Integrators | 20% |
| MRO Service Providers | 15% |
